


Fresh guidance and dividend news put SaizeriyaLtd (TSE:7581) in focus, as management outlined earnings expectations through fiscal 2027 and confirmed a higher payout for the year ended August 31, 2026.
The fresh guidance and dividend signals arrive after a strong run in SaizeriyaLtd’s shares, with a 1 month share price return of 21.53% and a year to date share price return of 42.15%. The 1 year total shareholder return has reached 47.14%, and the 5 year total shareholder return is 163.89%, suggesting momentum has been building as investors reassess both growth potential and income appeal around the latest outlook and payout plans.
Spot similar dividend and guidance setups by scanning our hand picked 29 dividend fortresses alongside SaizeriyaLtd’s latest payout and earnings outlook.SaizeriyaLtd now pairs clear earnings guidance and a richer dividend with a share price that has risen sharply in a short period. Is this still a solid deal, or simply a strong business priced at a full tag?
Price-to-Earnings of 34.7x: Is it justified?
Valuation for SaizeriyaLtd now leans heavily on what investors are willing to pay for each yen of profit, with a P/E ratio of 34.7x against a share price of ¥7,790. That level suggests the market is placing a premium on the company relative to some benchmarks, despite the recent strong share price performance.
The P/E ratio captures how much you are paying today for current earnings, which matters a lot for a restaurant operator with visible profit forecasts. For SaizeriyaLtd, this multiple sits in a zone where the market is clearly pricing in continued earnings growth and relatively dependable cash generation rather than treating the business as a low-growth utility-style payer.
Compared to its own peer set, 7581 is described as good value, since its 34.7x P/E sits well below the peer average of 69.1x. That framing points to investors paying roughly half the earnings multiple of similar companies, which can indicate the market is not fully assigning the same earnings expectations to SaizeriyaLtd as it does to those peers.
Relative to the broader JP Hospitality industry, the picture flips. The sector average P/E is 22.2x, which makes SaizeriyaLtd look clearly more expensive than the wider hospitality group. Against an estimated fair P/E of 28.2x, the current 34.7x ratio is also described as expensive, so the market price looks ahead of where the fair ratio suggests it could settle if expectations cooled.
Explore the SWS fair ratio for SaizeriyaLtd.
Result: Preferred multiple of Price-to-Earnings of 34.7x (OVERVALUED)
Still, SaizeriyaLtd faces obvious pressure points if expectations cool, including any disappointment versus guidance or a shift in how investors treat premium P/E valuations.
Find out about the key risks to this SaizeriyaLtd narrative.
Another view on SaizeriyaLtd’s value
The P/E workup presents SaizeriyaLtd as expensive relative to the broader JP Hospitality group, and also as premium priced versus its own fair ratio. A different lens tells a very different story. Our DCF model points to an estimated future cash flow value of ¥11,251.81 per share against a market price of ¥7,790, which implies the shares screen as undervalued on that framework.
This gap reflects two competing stories about SaizeriyaLtd: one tied to earnings multiples and sector comparisons, and the other to long term cash flows and discount rates. Which one carries more weight for you when guidance is already on the table and sentiment is elevated?
Look into how the SWS DCF model arrives at its fair value.
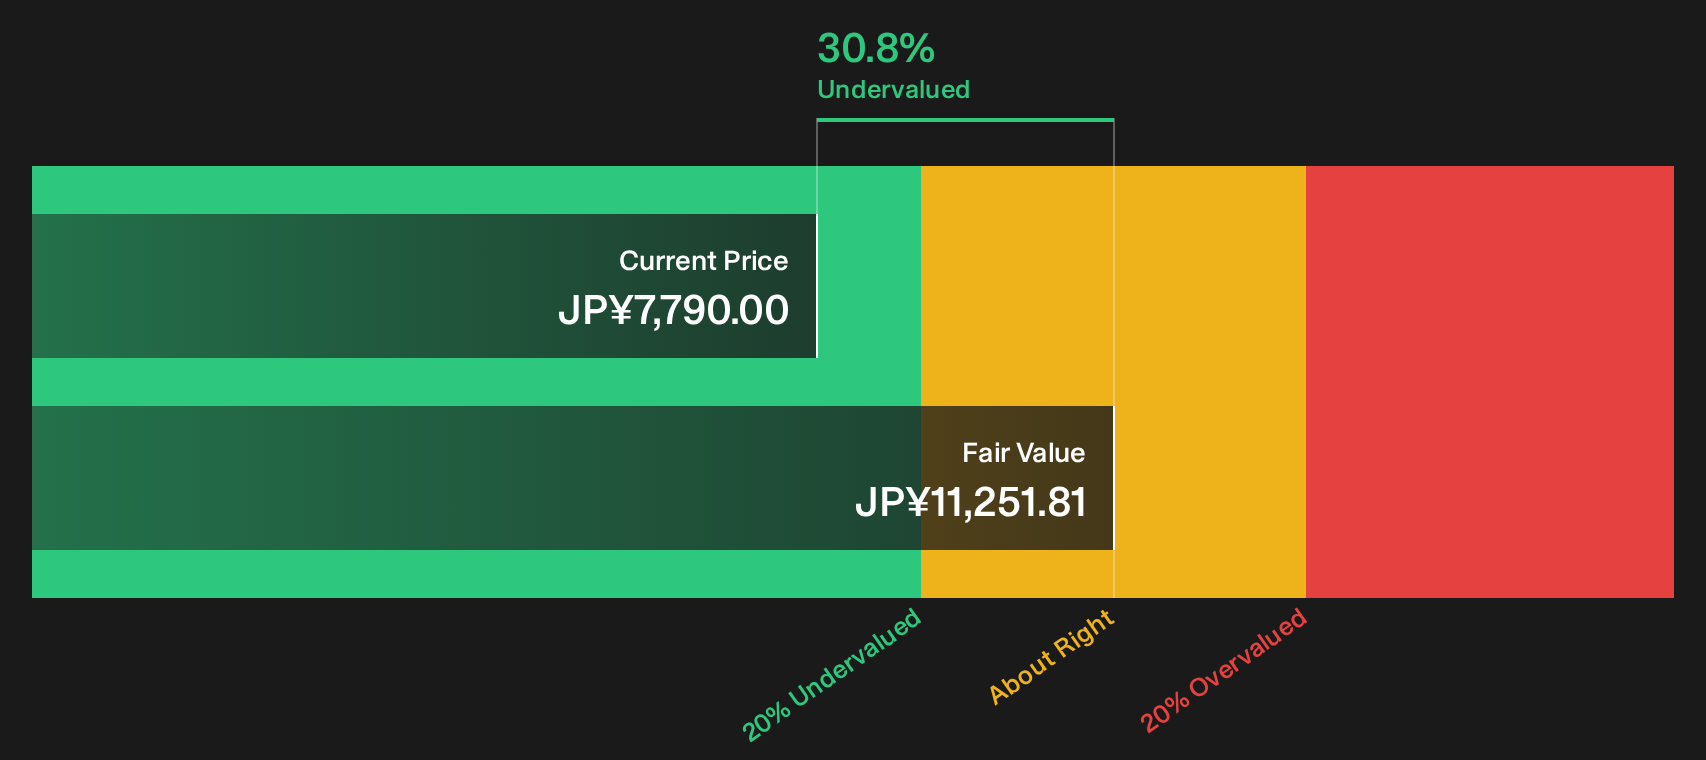
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SaizeriyaLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in SaizeriyaLtd’s valuation story and guidance are clear, so weigh both sides quickly and shape your own view using the 2 key rewards and 1 important warning sign.
Want more ideas beyond SaizeriyaLtd?
If SaizeriyaLtd has sharpened your appetite for fresh opportunities, do not stop here. Broaden your watchlist with other setups that combine quality, value, and income potential.
- Target reliable cash generators by scanning companies with robust balance sheets and consistent fundamentals using our list of solid balance sheet and fundamentals (22 results).
- Explore potentially overlooked value by reviewing a curated 13 high quality undervalued stocks that may align with your return and risk preferences.
- Strengthen your income stream by comparing yield focused opportunities featured in our hand picked 29 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com