


NBT Bancorp (NBTB) heads into its October 27 earnings release with expectations for higher profit and revenue compared with the same quarter last year, after recent commentary became more optimistic on its earnings outlook.
Recent trading has been choppy rather than weak, with NBT Bancorp’s share price slipping around 2% over the past three months, even as the year-to-date share price return sits near 22% and the 3-year total shareholder return is above 80%. This suggests long-term holders have still been rewarded, while short-term momentum has cooled ahead of the earnings update.
Spot similar bank stocks where earnings sentiment and price action are starting to line up by scanning our hand picked list of solid balance sheet and fundamentals (25 results).NBT Bancorp appears to be a solid regional banking platform, and recent long term returns support that view. After this year’s run and the recent pause, is the quality of the business still available at a reasonable price?
Most Popular Narrative: 11% Undervalued
The most followed narrative currently pegs NBT Bancorp’s fair value at $56.83, compared with the recent $50.68 close. This points to a valuation gap that hinges on how durable its earnings mix and capital returns prove to be.
Consistent growth in retirement, wealth and insurance revenues, now above US$32 million per quarter and about 27% of total revenues, shows that NBT Bancorp’s fee based businesses are becoming a larger earnings contributor. This can reduce reliance on spread income and support more stable margins.
See why 15 investors see NBT Bancorp as 11% undervalued.
Result: Fair Value of $56.83 (UNDERVALUED)
Still, the NBT Bancorp narrative leans heavily on upstate and Northeast economic projects, as well as on tech spending that could raise costs without matching customer growth.
Find out about the key risks to this NBT Bancorp narrative.
Another View: NBT Bancorp On Earnings Multiples
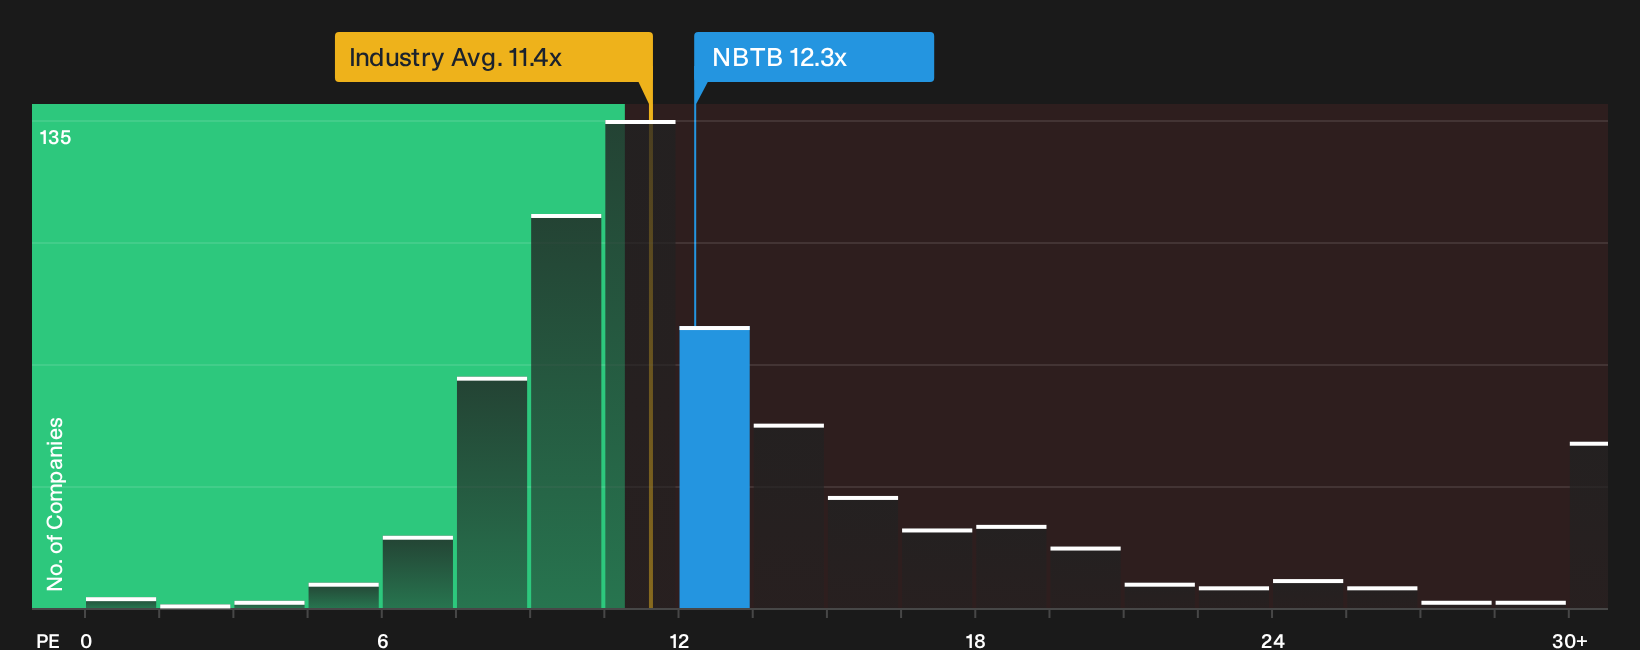
The story looks different when you swap fair value models for simple price tags. NBT Bancorp trades on a P/E of 12.3x, compared with a fair ratio of 11.6x, the US Banks average at 11.5x, and peers around 10.2x. That premium suggests less room for error if growth or returns soften.
For investors who lean on earnings multiples, the question is whether this richer P/E is paying up for quality or instead narrowing the margin of safety.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around NBT Bancorp is mixed, with both confidence and concern in the story. Act quickly, review the full picture, and weigh the 4 key rewards and 1 important warning sign.
Looking For More Ideas Beyond NBT Bancorp?
If NBT Bancorp interests you, do not stop here. Use the Simply Wall Street Screener to surface fresh opportunities before everyone else starts talking about them.
- Target potential mispricings by scanning a focused set of 35 high quality undervalued stocks that pair quality fundamentals with compressed valuations.
- Prioritize resilience by hunting through 32 resilient stocks with low risk scores that show stronger balance sheets and steadier financial profiles.
- Get in early on quieter opportunities by reviewing 20 high quality undiscovered gems that have strong numbers but limited market attention so far.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com