


BMO Capital, Deutsche Bank and Raymond James all reaffirmed their views on C.H. Robinson Worldwide (CHRW) after the latest earnings release, as the logistics group reported quarterly revenue of US$4.93b and net profit of US$186.79m for the June quarter.
C.H. Robinson Worldwide’s share price has slipped over the short term, with the 30-day share price return down 9.24% and the 90-day move down 33.70%, while total shareholder return over the past year is 10.60% and 76.44% over three years. This contrast indicates that the current weakness may be more closely related to shifting sentiment around future earnings than to the longer-run record.
Scan how C.H. Robinson Worldwide compares with logistics peers under pressure by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
The share price slide and mixed analyst views put C.H. Robinson Worldwide at an awkward crossroads. Does that reset leave enough upside to justify the risk, or has the easy part of the three year gain already played out?
Most Popular Narrative: 29% Undervalued
The most followed valuation narrative puts C.H. Robinson Worldwide’s fair value at $194.57 against a last close of $138.85. This frames the current pullback as a sizable discount that rests heavily on execution of its operating model and legal risk management.
Scaling of proprietary digital capabilities and deployment of automated, self serve logistics tools, backed by a data set of around 100 trillion data points and agentic AI, is allowing C.H. Robinson Worldwide to handle much higher quote volumes with similar staffing. This can support future revenue growth and higher operating margins.
See why 6 investors see C.H. Robinson Worldwide as 29% undervalued.
Result: Fair Value of $194.57 (UNDERVALUED)
Still, C.H. Robinson Worldwide faces two clear pressure points: legal liability that could raise insurance and compliance costs, and RXO deal leverage that limits balance sheet flexibility.
Find out about the key risks to this C.H. Robinson Worldwide narrative.
Another View: C.H. Robinson Worldwide Looks Expensive On Earnings
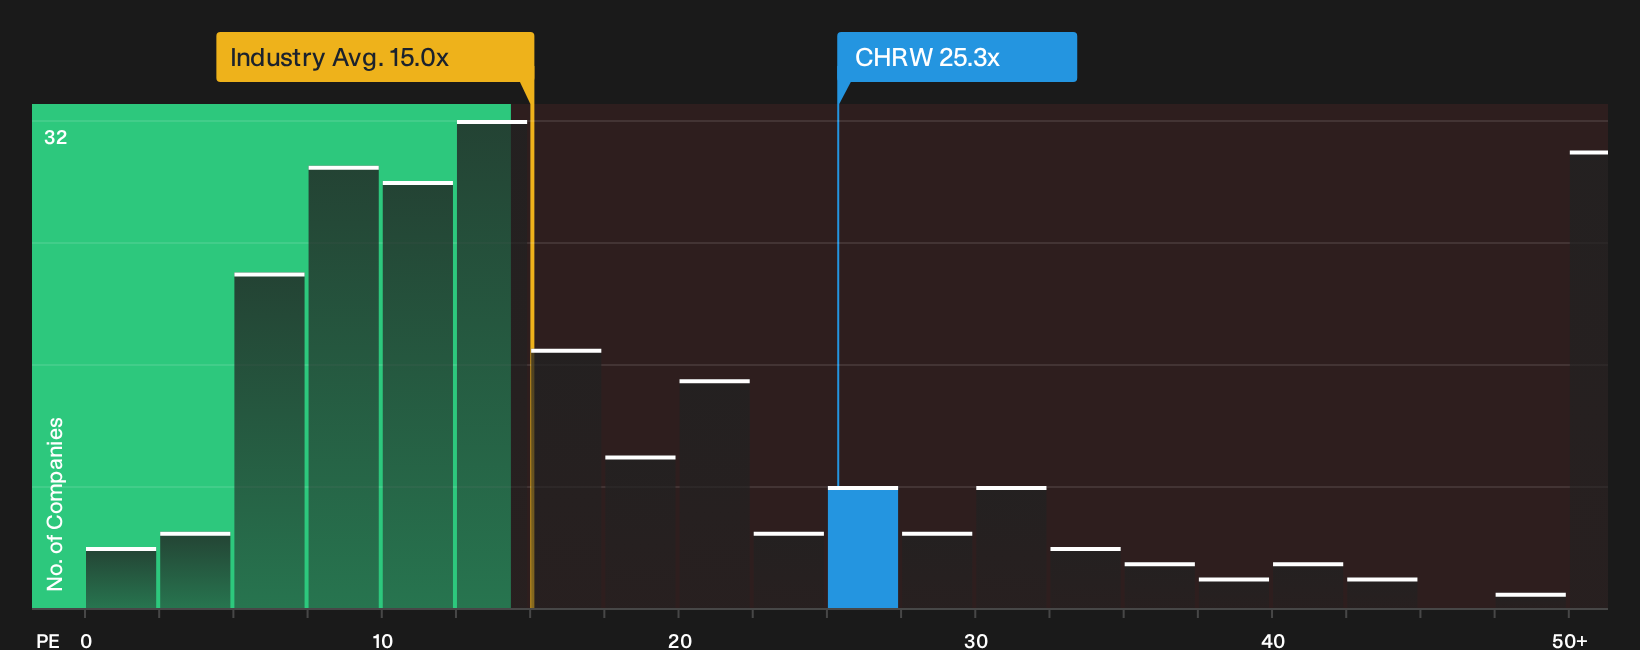
The story changes once the focus shifts from fair value models to simple earnings multiples. C.H. Robinson Worldwide trades on a P/E of 25.3x, while the fair ratio sits at 17.2x and peers cluster closer to 23.8x and the global logistics pack around 15.1x. That richer tag suggests less margin for error if the popular undervalued narrative stumbles, so which signal should carry more weight in your process?
For a closer look at how this earnings multiple compares with the fair ratio and sector peers, take a look at the detailed valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and worry around C.H. Robinson Worldwide feels conflicted, treat it as your cue to move quickly. Test the assumptions in the data, and weigh both the downside and upside case through the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond C.H. Robinson Worldwide?
Do not stop at C.H. Robinson Worldwide. Use the Simply Wall St screener to quickly surface fresh opportunities that match your risk tolerance and portfolio goals.
- Target potential bargains that combine quality and a discount to fair value by reviewing the 35 high quality undervalued stocks.
- Scan the 32 resilient stocks with low risk scores for ideas that focus on resilience and stronger downside protection.
- Spot less crowded opportunities with strong fundamentals by checking the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com