


Aflac’s AI Partnership With bswift
Aflac (AFL) just became the exclusive launch partner for bswift’s new AI-powered carrier configuration tools, in a move focused on cutting manual work and improving accuracy in benefits plan setup.
The technology uses Emma Intelligence to read carrier-specific plan documents, then automatically builds plan structures, rates, and rules for human review, with the goal of streamlining complex voluntary benefit configurations.
Aflac’s partnership news lands after a mixed stretch for the stock, with a 7.65% year to date share price return but a decline of nearly 4% over the past 90 days, while long term total shareholder returns of 63.92% over three years and 133.21% over five years reflect momentum that has rewarded patient holders.
Scan other insurers leaning into AI-driven efficiency with our curated list of 32 resilient stocks with low risk scores that pair operational discipline with balance sheet resilience.
Aflac just rolled out fresh AI news, and the share price has cooled over the past quarter. Does that mix still leave enough upside in the current valuation to favor new capital stepping in?
Most Popular Narrative: 0% Overvalued
Aflac last closed at $118.67, almost exactly in line with the most followed narrative fair value of $118.53. This means the current AI partnership story is riding on a stock that is already priced as if expectations are broadly met rather than reset.
The main factor that has to go right is that Aflac converts its Japan yield-curve repositioning, new savings products, U.S. group and dental/vision expansion, and internal reinsurance into enough profitable growth to offset pressures on third sector and U.S. voluntary premiums.
The current valuation, alongside an Underperform rating and a US$103 price target from one research firm, suggests the market is cautious about Aflac’s ability to grow earnings beyond what capital returns and investment income already support.
See why 43 investors see Aflac as 0% overvalued.
Result: Fair Value of $118.53 (ABOUT RIGHT)
Still, the Japan premium pressure and higher benefit ratios, along with cybersecurity fallout, could easily tilt sentiment against the current Aflac narrative.
Find out about the key risks to this Aflac narrative.
Another View: Aflac Through The Cash Flow Lens
Where analysts broadly see Aflac as fairly priced around $118.53, the SWS DCF model points in a different direction. On that framework, the shares trade about 31% below an estimated future cash flow value of $173.05, which frames today’s price as a potential gap between sentiment and cash generation.
For investors weighing which story to trust more in their own process, it comes down to a simple question. Do you lean more on near term earnings forecasts and P/E bands, or on the cash flows the business could throw off over time, even if consensus expects earnings to decline?
Look into how the SWS DCF model arrives at its fair value.
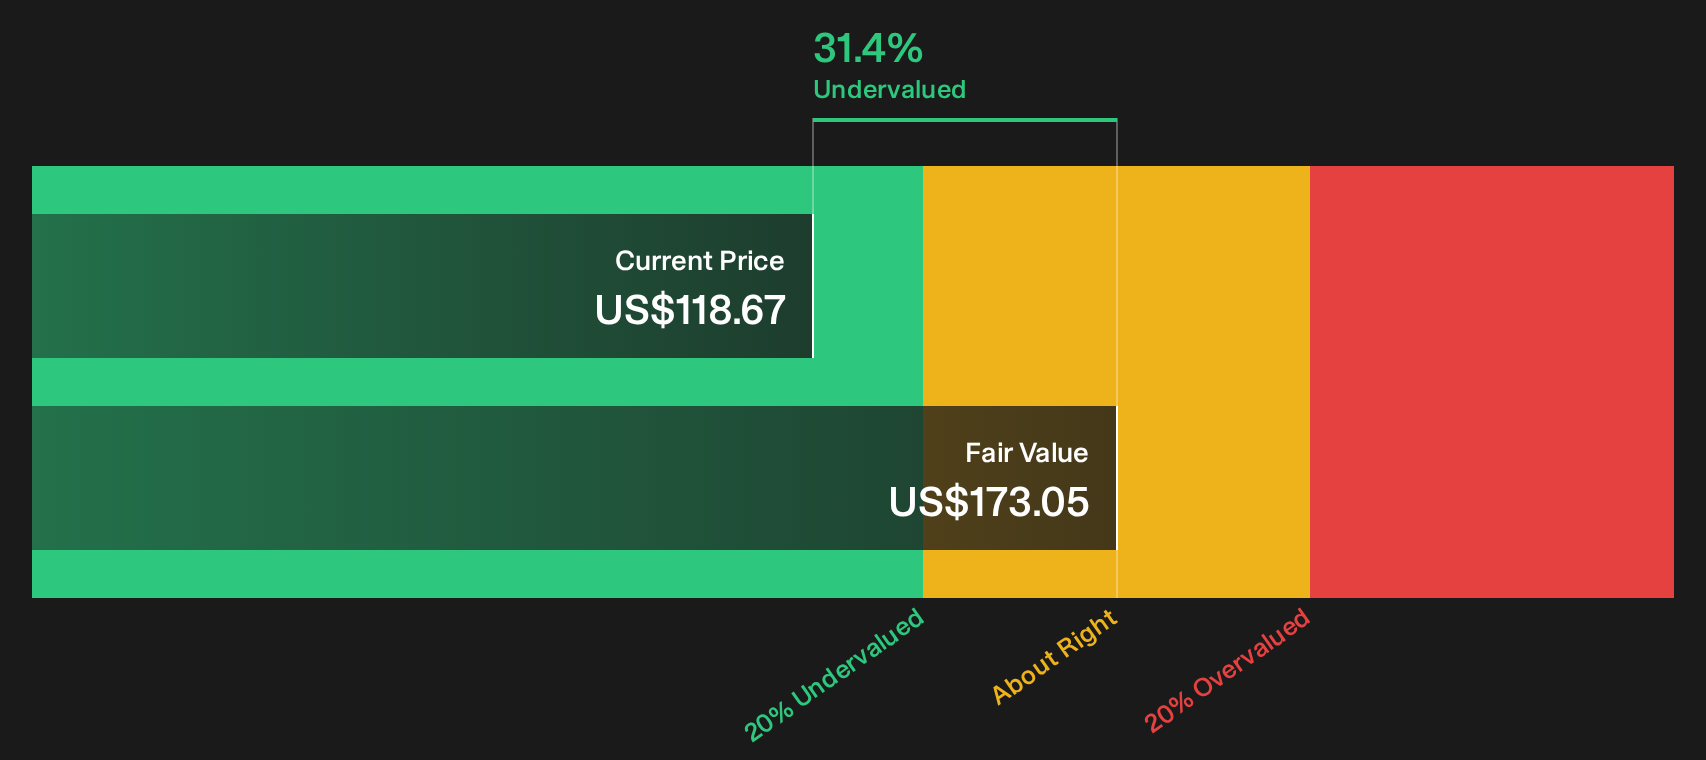
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aflac for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of AI ambition and valuation debate feels finely balanced, move fast and test the numbers yourself to see where you land. To weigh both the potential upsides and the concerns flagged by other investors, start with the 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Aflac?
If Aflac has your attention, do not stop there. Use the Simply Wall Street Screener to pressure test fresh ideas and keep your watchlist ahead of the crowd.
- Target potential mispricing by scanning a focused set of 35 high quality undervalued stocks that combine quality fundamentals with room for sentiment to catch up.
- Build a steadier income stream by reviewing 8 dividend fortresses that aim for higher yields while still prioritizing financial strength.
- Strengthen your downside protection by zeroing in on a list of solid balance sheet and fundamentals (25 results) that can handle shocks better than heavily leveraged peers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com