


Apple (AAPL) shares have been in a major uptrend in 2026, but Ananda Baruah, a senior analyst with Loop Capital, believes it’s likely as far as they go in the near term. Baruah downgraded AAPL this morning to “Hold” and lowered his price target on the iPhone maker to $330, indicating potential downside of about 3% from current levels.
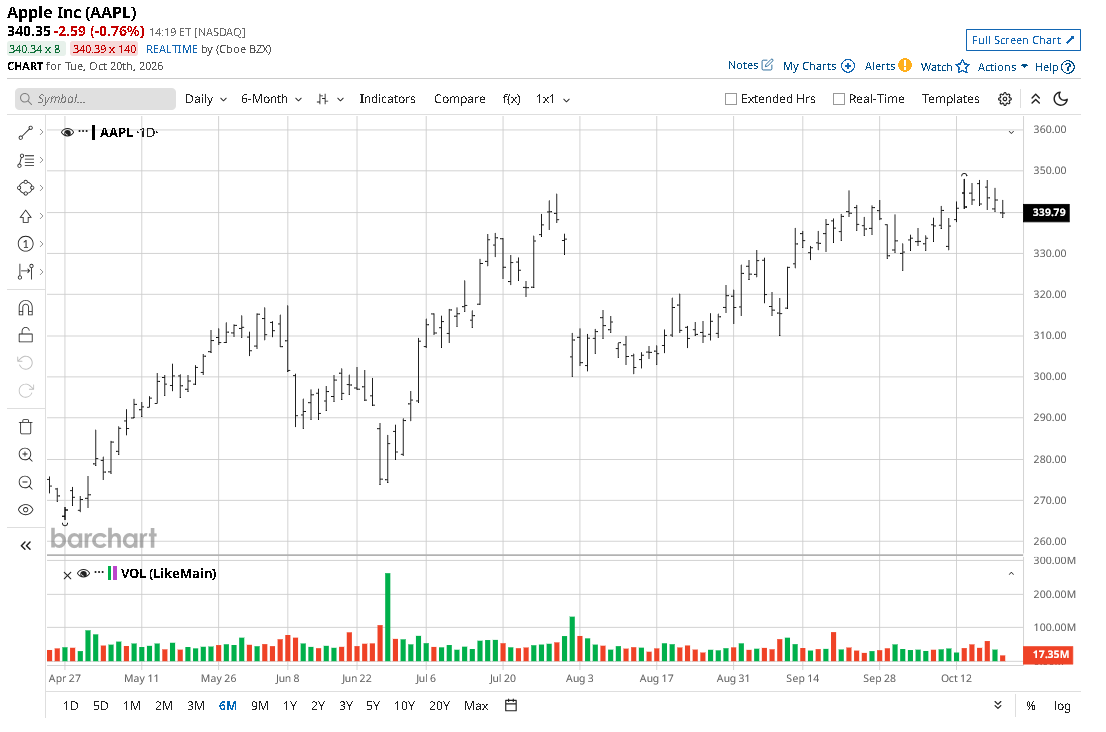
Versus the start of this year, Apple stock is trading up about 25% as of this writing.
Why Baruah Recommends Caution on Apple Stock
In his research report, Baruah had all praise for Apple’s services story, and he retains confidence in the company’s ability to grow its market share over the longer term. But recent signs of weakness in the demand for Apple’s latest iPhone 18 could make it increasingly difficult for its share price to rip higher from here in 2027.
“AAPL also requires a fundamental catalyst reset after its recent price appreciation — particularly given it’s trading at a 5 year valuation highs even as iPhone ships have reduced,” he told clients.
Note that Apple is currently trading at a forward price-to-earnings (P/E) multiple of about 36x.
Technicals Signal Continued Upside in AAPL Shares
According to Baruah, weakness in iPhone sales was initially thought of as supply-related (memory and processors) and not demand-related.
But “that no longer appears to be the case,” he added. Therefore, he is recommending caution in initiating a new position in Apple shares at the current price.
From a technical perspective, however, AAPL looks poised for continued gains heading into 2027. The tech behemoth currently sits firmly above its key moving averages (MAs), with an RSI in the mid-50s indicating significant upside potential before the stock reaches overbought conditions.
A small 0.32% dividend yield makes Apple even more attractive as a long-term holding.
What’s the Consensus Rating on Apple?
Crucially, other Wall Street analysts aren’t particularly bullish on AAPL stock either — at least for the near-term.
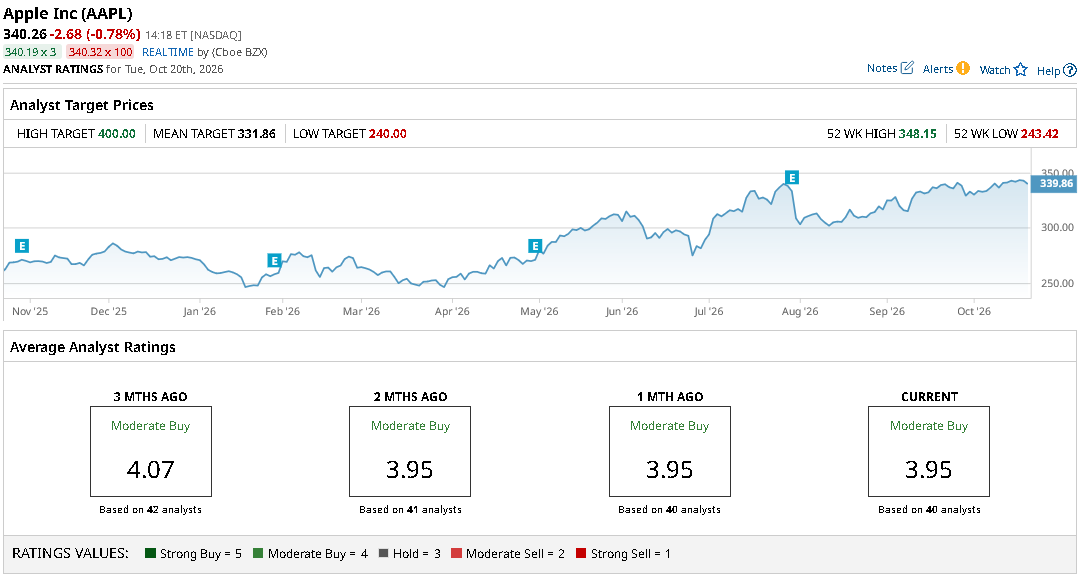
While the consensus rating on Apple remains at “Moderate Buy,” the mean price target of about $331 suggests potential downside of about 3% from the current price.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.