


Kinetik Holdings (KNTK) just paired strong quarterly momentum with income news, affirming a cash dividend of $0.81 per share, or $3.24 on an annualized basis, payable on October 30, 2026.
Recent price action has cooled slightly, with the share price slipping 0.2% over the last day and 1.9% over the week. Even so, Kinetik Holdings still posts a 49.5% year to date share price return and a 60.4% one year total shareholder return, pointing to momentum that has built over time rather than faded.
Compare Kinetik Holdings with a curated group of income plays and strong operators by scanning the 8 dividend fortresses alongside this latest dividend move.
After a near 50% year to date run and a rich cash payout, the temptation is to wait for a pullback. Does Kinetik Holdings still look reasonable value if you buy at today’s price?
Most Popular Narrative: 4.9% Undervalued
On the latest numbers, the most followed narrative pegs Kinetik Holdings at a fair value of $57.31 against a last close of $54.52. This points to modest upside if that view holds. The gap is not huge. Yet it reflects a story built around contract quality, Gulf Coast access and heavy midstream buildout rather than short term trading moves.
Reworked gas processing contracts, including amendments that extend legacy Durango volumes into the mid to late 2030s, expand dedicated acreage by about 25% for at least one large customer, and increase the fee based share above the prior 60% mix, are setting up a larger base of long duration, less commodity sensitive revenue and EBITDA.
See why 9 investors see Kinetik Holdings as 5% undervalued.
Result: Fair Value of $57.31 (UNDERVALUED)
Still, parts of the Kinetik Holdings story remain fragile, with heavy 2026 capex and ongoing Waha price pressure, both capable of unsettling that fair value narrative.
Find out about the key risks to this Kinetik Holdings narrative.
Another View: Kinetik Holdings Looks Expensive On Earnings
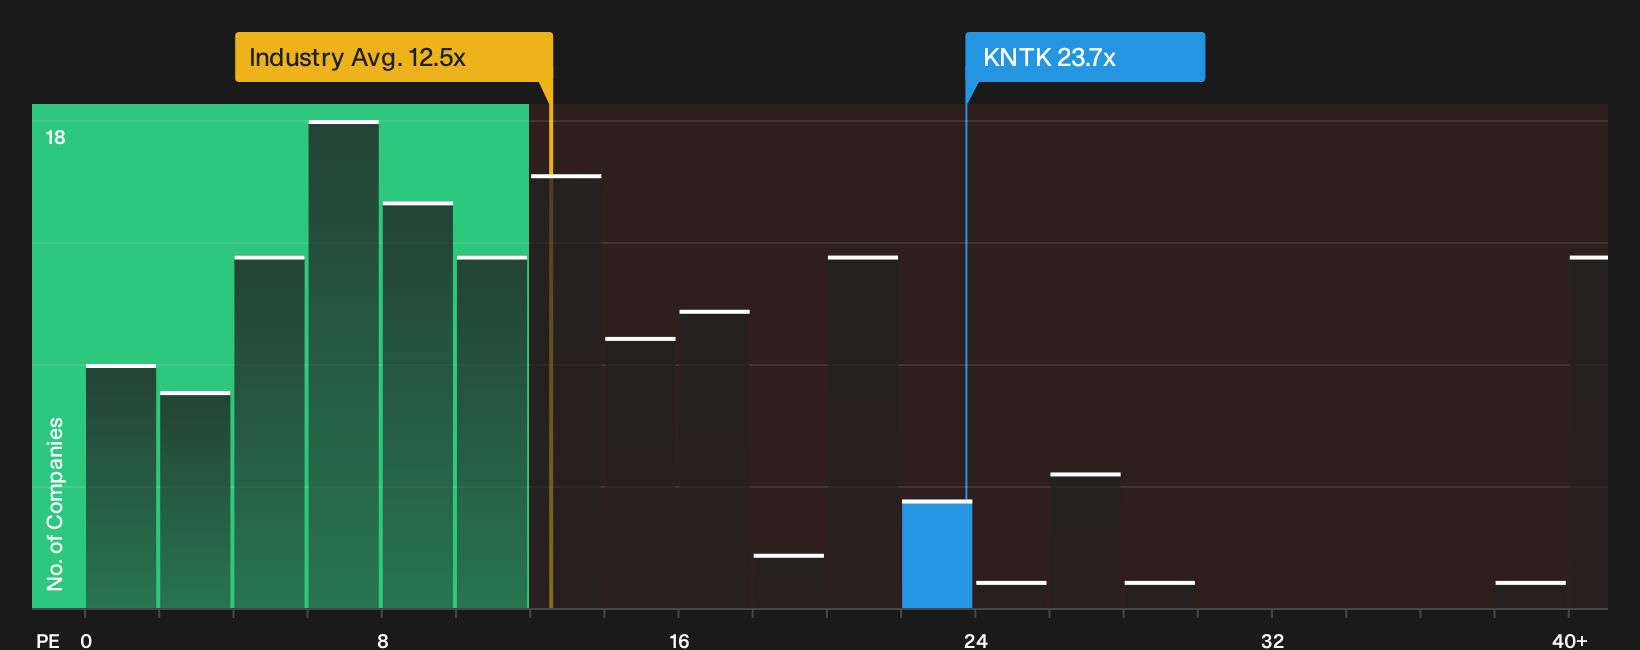
That 4.9% discount to fair value is one story. A different picture appears when you look at Kinetik Holdings through its P/E. The shares trade at 23.7x, compared with 17.3x for peers, 12.5x for the wider US Oil and Gas group and a fair ratio of 17.2x, which points to valuation risk if sentiment cools.
Put simply, the stock looks cheap on narrative fair value but expensive on earnings. Which lens do you trust more when real money is on the line: the story, or the multiple premium to sector and fair ratio See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The split views on Kinetik Holdings make this a live debate, so move fast, review the underlying numbers, and weigh both upside and downside. To see a concise rundown of the current upside case alongside the main red flags in one place, start with the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Kinetik Holdings?
If Kinetik Holdings has you thinking about income, value, and risk, do not stop at a single ticker. Broaden your watchlist now or you will miss opportunities.
- Target resilient payers by reviewing a curated set of income-focused candidates through the 8 dividend fortresses.
- Hunt for potential value opportunities by scanning a focused group of companies that screen well on both quality and price using the 35 high quality undervalued stocks.
- Prioritise capital preservation by filtering for companies with steadier profiles and stronger risk scores via the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com