


- Annaly Capital Management reported its third quarter 2026 results on 20 October, with consensus previously expecting higher net interest income and earnings supported by its mortgage-focused portfolio.
- The company has delivered earnings above consensus in each of the past four quarters, which draws attention to how it manages funding costs against higher short term interest rates.
- We examine how Annaly Capital Management's investment narrative is shaped by expectations for higher net interest income ahead of the earnings release.
Annaly Capital Management Investment Narrative Recap
To own Annaly Capital Management, you need to believe the mortgage finance model can keep generating attractive net interest income through cycles, even when short term funding gets more expensive. The upcoming third quarter 2026 report is mainly a check on how well that spread engine is holding up and whether recent earnings strength remains intact.
The key short term catalyst is how net interest income trends versus rising funding costs. That directly feeds into earnings available for distribution and, by extension, dividend capacity. The biggest near term risk is prolonged rate volatility and hedging costs that compress portfolio returns. This earnings release looks important, not cosmetic, for that thesis.
The most relevant reference point for this setup is Annaly Capital Management's recent track record of earnings coming in above expectations over the last four quarters. That streak drew attention to the firm’s ability to manage funding costs against higher short term rates while still producing solid reported profitability.
This coming quarter tests whether that pattern is sustainable or was helped by one off tailwinds. If higher borrowing costs and wider mortgage spreads start to weigh more heavily on Agency MBS and residential credit returns, the risk side of the story, including dividend coverage and leverage comfort, moves closer to the foreground for income focused holders.
Annaly Capital Management's current earnings are reported at US$1.9b, with analyst consensus pointing to US$2.3b of earnings and US$2.7b of revenue by 2029. That profile implies annual top line growth of 3.7% and an earnings increase of about US$0.4b from today to the 2029 forecast level.
Uncover why Annaly Capital Management's fair value indicates a 31% potential upside to its current price that could narrow quickly.
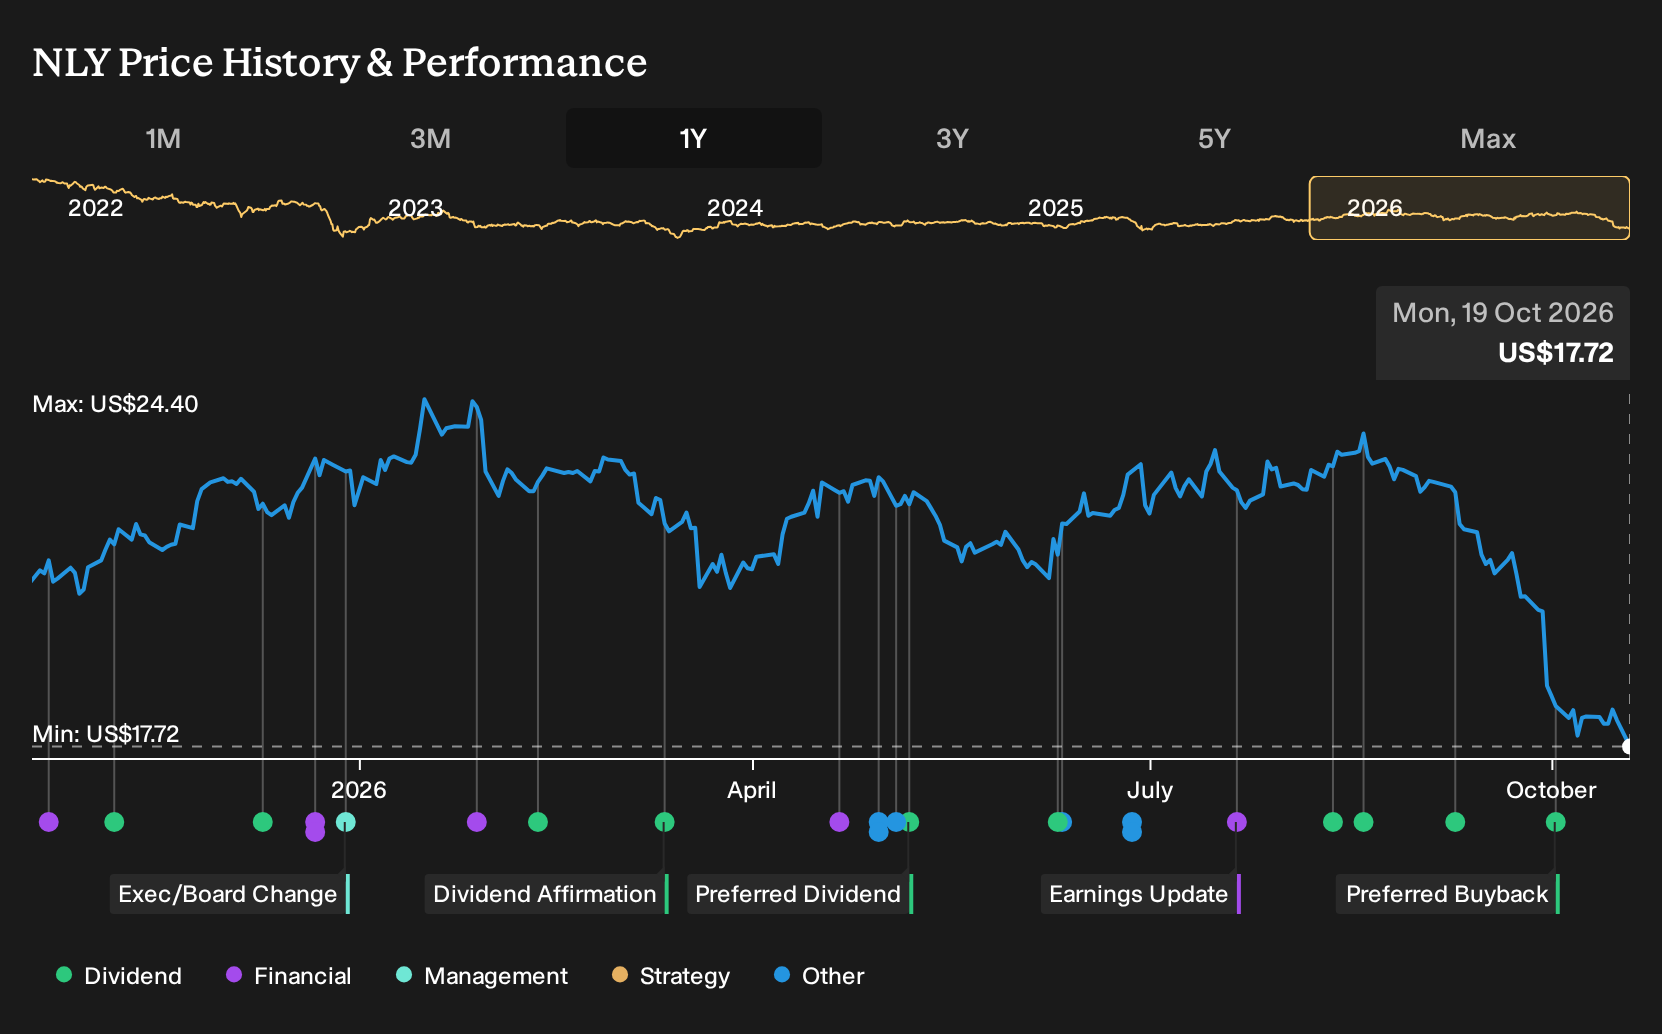
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$24 to just over US$45, so private investors there are clearly not aligned on what Annaly Capital Management is worth. When you factor in rising rate risk, mortgage spread moves, and pre earnings uncertainty, you get a wide field of opinion you can actively explore.
Explore 2 other Annaly Capital Management fair value estimates, including one that indicates potential upside of up to 147% from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Annaly Capital Management research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Annaly Capital Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Annaly Capital Management's overall financial health at a glance.
Looking For More Investment Ideas Beyond Annaly Capital Management?
Once you have a view on Annaly Capital Management, it can help to line it up against other opportunities that match your risk appetite, income goals, and balance sheet preferences. The Simply Wall St screener gives you structured ways to do that comparison rather than relying on headlines or hunches.
- For investors who want companies with strong income potential and balance sheet strength, start with this curated 8 dividend fortresses that targets payouts backed by more robust financial profiles.
- If you are hunting for quality at a reasonable price, scan the 35 high quality undervalued stocks and see which stocks combine solid fundamentals with valuations that may not fully reflect them yet.
- When you want ideas that are off the beaten path but still grounded in financial quality, work through the 20 high quality undiscovered gems to surface lesser known businesses with sturdier numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com