


Amcor has delivered a 22.2% return over the past 3 years, which naturally puts fresh attention on what investors are paying for each dollar of its earnings today. With the share price recently at US$44.73, the key issue is whether that move is still aligned with what the packaging group is actually earning.
- The 22.2% gain over 3 years means anyone looking at Amcor now has to ask if the recent share-price journey is fully backed by its profit power.
- As a mature packaging business that tends to depend on steady volumes and disciplined cost control, shifts in margins or cash conversion can quickly change what looks like a reasonable earnings multiple.
- Your read on Amcor is one view; the desks covering it have another. See what analysts think Amcor's shares could be worth.
The stock's next move may depend on whether the current price fairly reflects Amcor's earnings based on this Fair Ratio lens.
If you are weighing Amcor on its earnings multiple, it can help to compare that picture against a wider set of companies screened for 35 high quality undervalued stocks
Where Does Amcor Sit on Earnings?
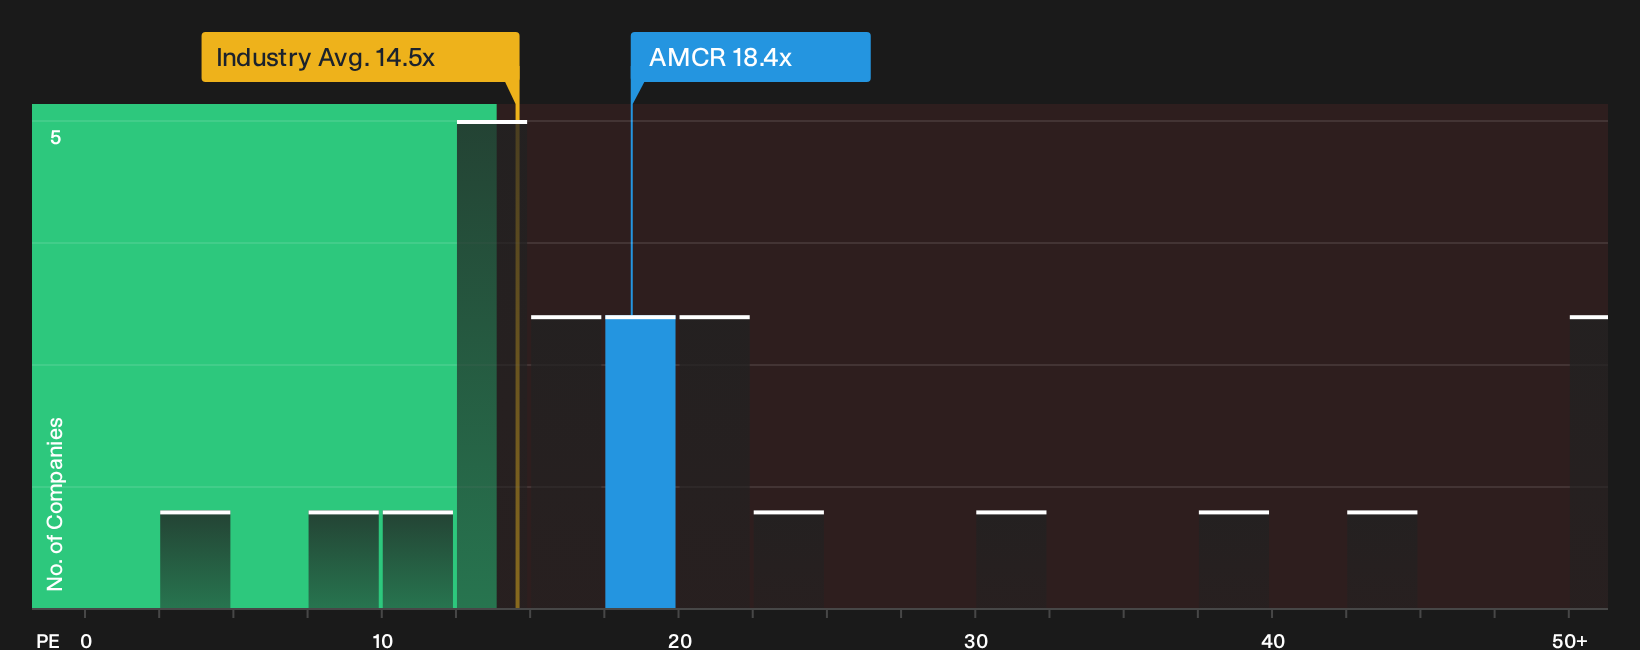
The P/E ratio suits Amcor because earnings remain a key anchor for a mature packaging group where growth tends to be steadier than in more cyclical sectors. On this lens, the stock trades on about 18.7x earnings, which is above the packaging industry average of roughly 14.5x. That puts a premium on the shares relative to the sector, yet the gap to the broader peer group average of about 25.3x is wide enough that the stock does not screen as aggressively priced against global comparables.
The Fair Ratio points to the kind of P/E you might expect given Amcor’s mix of margins, cash generation, size and risk profile. The current multiple sits close to that reference point, which suggests the market is roughly aligning the share price with those underlying economics rather than assigning a clear discount or a rich premium. For anyone assessing whether to build or add to a position, the real question is how comfortable you are with that earnings profile and whether it justifies paying something in this range for each dollar of profit. Explore the numbers behind Amcor's P/E valuation.
The Amcor Narrative: What Would Justify Today's Price?
For Amcor, Simply Wall St Narratives pick up where the valuation puzzle leaves off by spelling out the future growth, margin and earnings paths that would need to play out for the current P/E to look either too low or too high. They sit on the Community page and turn a single ratio or model output into a set of concrete assumptions, so you can watch over time whether Amcor's actual performance lines up with that implied story.
Community views on Amcor split between synergy driven upside and balance sheet caution.
Bull case: 11% undervalued
"The current valuation implies the share price does not fully reflect Amcor’s multi year synergy potential, planned balance sheet de risking and exposure to growing sustainable and advanced packaging markets..."
Discover why this Narrative puts Amcor at 11% undervalued.
Bear case: 795% overvalued
"The shares offer a high yield and appear cheap on asset and normalized earnings metrics, but weak current ROE and high leverage suggest caution until merger synergies clearly lift EPS..."
Explore why this Narrative puts Amcor at 795% overvalued.
An unanswered question for Amcor investors
Valuation only tells you what the market is willing to pay today. Analyst projections sketch out where they think Amcor could be a few years from now and how that lines up with this price. Explore where analysts expect Amcor to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com