


- Interactive Brokers Group reported third quarter net income of US$314 million and nine month net income of US$893 million, along with a higher quarterly dividend of US$0.15 per share payable on December 14, 2026 to shareholders of record on December 1, 2026.
- The combination of higher earnings per share from continuing operations and an increased cash dividend indicates management’s willingness to return more capital while continuing to invest in areas such as cryptocurrency staking on the IBKR platform.
- We will now assess how Interactive Brokers Group's higher dividend could reshape the investment narrative around earnings quality and capital allocation.
Compare Interactive Brokers Group's mix of rising earnings, a higher cash payout and new crypto staking revenue with curated ideas in the 35 high quality undervalued stocks filter, which is built for quality and value-focused investors.
Interactive Brokers Group Investment Narrative Recap
To own Interactive Brokers Group, an investor needs to believe the brokerage can keep attracting active traders and advisors while running a very automated, low cost platform. The recent step up in earnings and higher dividend points to a business that is currently generating enough profit to both reinvest and distribute cash, without changing the core story.
The near term swing factor is still client activity and the level of interest income on cash, margin and securities lending. Competitive pressure on pricing and any sharp cuts in benchmark rates remain the biggest operational risks. The latest results and dividend move are helpful signals, but they do not remove those pressures.
The launch of cryptocurrency staking looks most relevant for the current catalyst mix. It adds another fee stream on top of the existing crypto trading offering and keeps Interactive Brokers Group’s platform more “sticky” for clients who want to keep digital assets and traditional securities in one place.
Staking also introduces execution and regulatory risk. Service quality, uptime and reward accruals will matter to clients in the same way fills and margin do. If IBKR can run this reliably alongside prediction markets, extended hours and global access, it supports the idea that product breadth can keep trading volumes and engagement resilient through different market cycles.
What The Current Forecasts Assume For Interactive Brokers Group
Interactive Brokers Group's narrative projects US$10.7b revenue and US$1.8b earnings by 2029. This rests on analyst expectations of 16.0% yearly revenue growth and an earnings increase of about US$700m from US$1.1b today.
Uncover why Interactive Brokers Group's fair value indicates a 28% potential upside to its current price before the market potentially closes that gap.
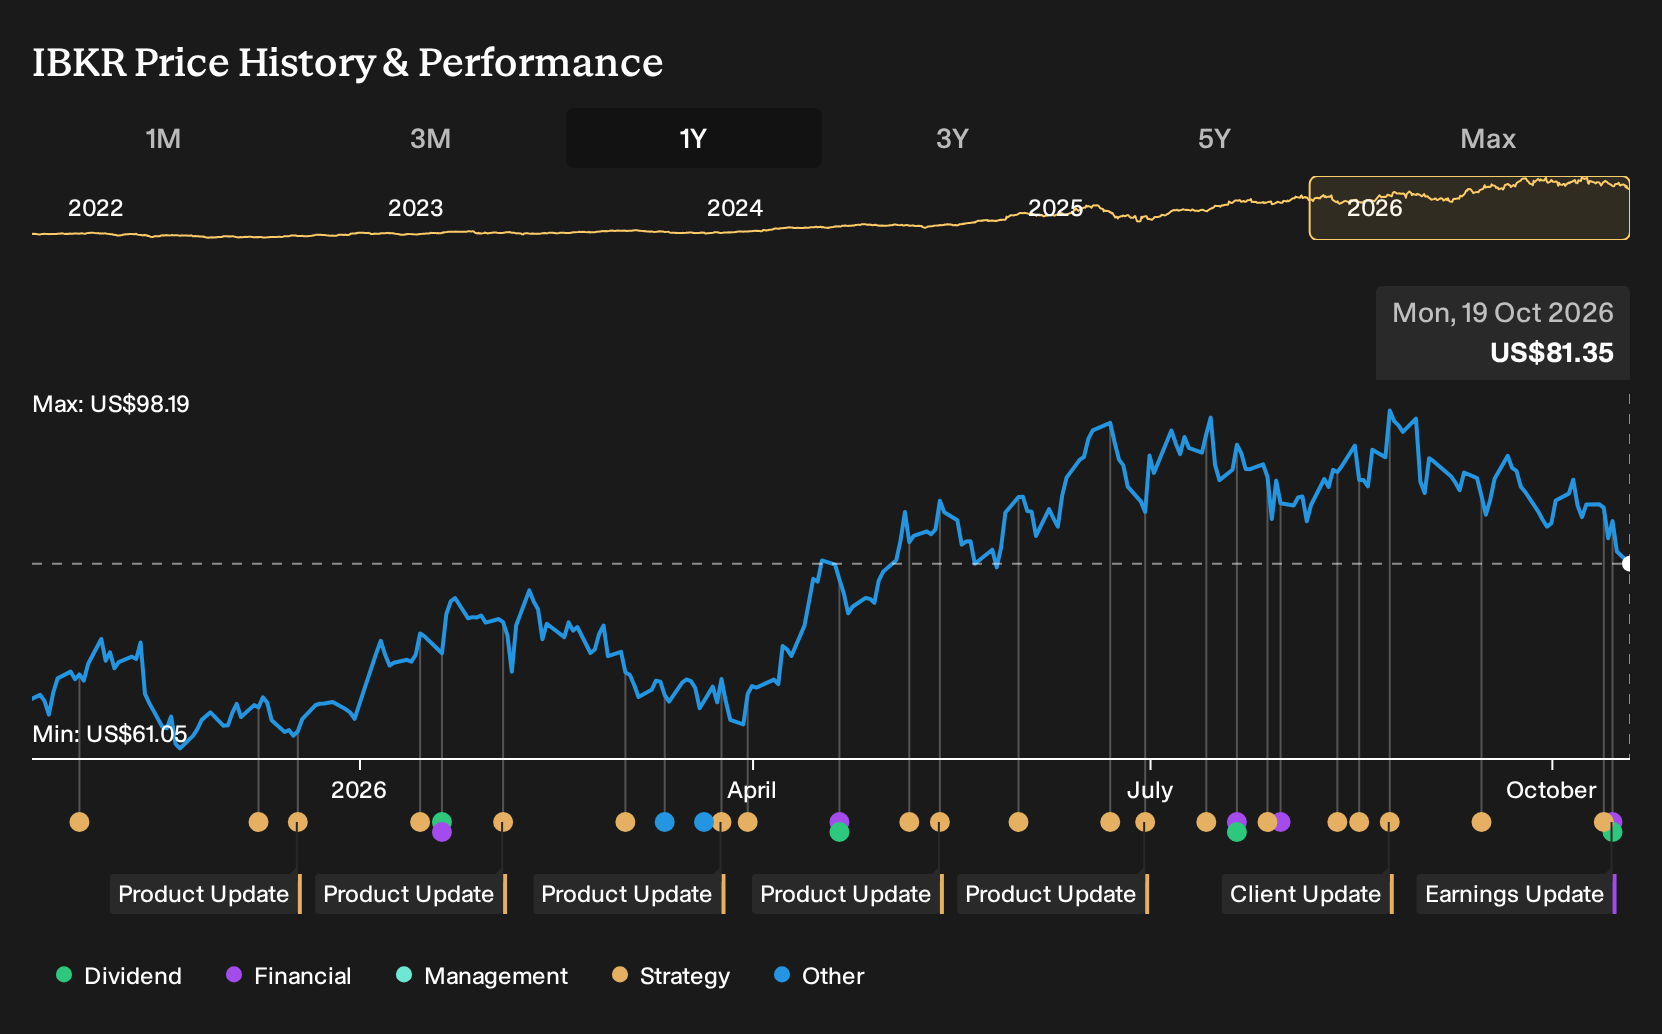
Exploring Other Perspectives
Some of the most optimistic analysts frame crypto staking and broader digital assets as the real swing factor for Interactive Brokers Group. Before this dividend news, the bullish camp was already sketching out about US$11.8b in 2029 revenue and US$1.9b in earnings. You can treat those as one possible path and compare them with more cautious views that may now shift again after the latest announcements.
Explore 7 other Interactive Brokers Group fair value estimates, including one that suggests as much as 34% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Interactive Brokers Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Interactive Brokers Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interactive Brokers Group's overall financial health at a glance.
Looking For More Ideas Beyond Interactive Brokers Group?
If this update on Interactive Brokers Group has sharpened your view on earnings quality and capital returns, it can be useful to line that up against what other businesses are offering right now. Use the Simply Wall St Screener to scan the wider market and see which opportunities best match your return targets and risk tolerance.
- If you care most about financial strength and balance sheet resilience, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stressing the capital structure.
- For investors who want quality at a sensible entry point, compare Interactive Brokers Group with a 35 high quality undervalued stocks that can blend cash flow support with more conservative pricing.
- If lower volatility and downside protection matter more than rapid gains, focus on 32 resilient stocks with low risk scores that score well on stability and business durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com