


Skylark Holdings (TSE:3197) has released its September 2026 trading statement, reporting all-store sales at 105.8% and same-store sales at 102.9%, which has drawn investor attention ahead of year-end positioning.
On the market side, Skylark Holdings has picked up momentum, with a 7.28% 7-day share price return and a 20.03% 90-day gain. The 1-year total shareholder return of 24.26% and 5-year total shareholder return of 142.09% indicate a strong longer-term payoff profile.
Compare Skylark Holdings' recent sales resilience with other consumer-facing businesses by scanning our curated list of 73 high quality undiscovered gems that may still be flying under most investors' radar.
After Skylark Holdings’ sharp run, the real tension is simple. Do you pay up for momentum or wait for a cooler entry and risk the stock running further before the valuation stacks up in your view?
Preferred P/E of 42.7x: Is it justified?
On valuation, Skylark Holdings is being asked to clear a high bar, with a P/E ratio of 42.7x against a backdrop of earnings that are growing but not flagged as rapid. The last close at ¥3,580 prices the restaurant operator at a premium that assumes meaningful profit expansion and resilience in its cash generation.
The P/E multiple compares the current share price to earnings per share and effectively tells you how many years of current profits the market is willing to pay for today. For a mature hospitality group, a high P/E usually reflects expectations for consistent earnings growth, perceived quality of profits, or a belief that the current profit base is temporarily depressed relative to future potential.
For Skylark Holdings, recent data points to a business with high quality earnings, net profit margins at 4% compared with 3.6% a year earlier, and forecast earnings growth of 10.67% per year. That profile can support a richer tag. Yet the P/E of 42.7x is described as expensive versus the estimated fair P/E of 26.8x and also compared with the peer average of 36.5x. Against the JP Hospitality industry average of 22.2x, the premium is even more pronounced, which suggests the valuation is stretching ahead of what the fair ratio analysis indicates the market could move toward over time.
Explore the SWS fair ratio for Skylark Holdings.
Result: Price-to-Earnings of 42.7x (OVERVALUED)
Still, the story can break if Skylark Holdings faces weaker restaurant traffic in Japan or if profit delivery falls short of what a 42.7x P/E implies.
Find out about the key risks to this Skylark Holdings narrative.
Another View: SWS DCF model points to only mild value
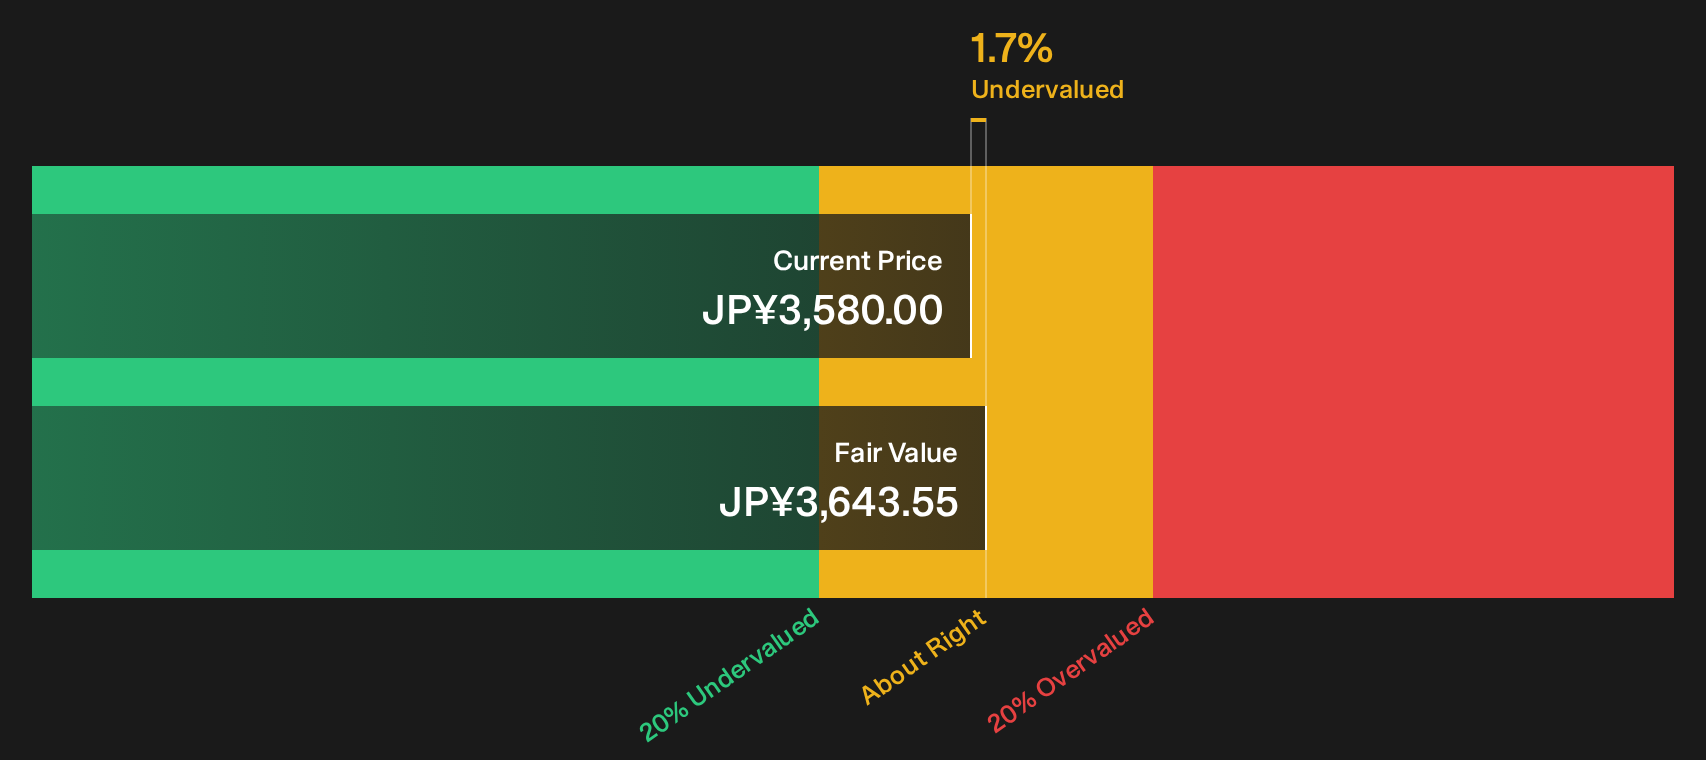
The P/E looks stretched, yet the SWS DCF model paints a softer picture. At ¥3,580, Skylark Holdings trades about 1.7% below an estimated future cash flow value of ¥3,643.55, which suggests only a small margin of value rather than a clear mispricing.
That kind of narrow gap can still matter, since it limits the cushion if earnings progress slows or sentiment on Japanese restaurant chains cools. It raises a simple question for you as an investor: Is a sliver of implied value enough compensation for paying up for a high multiple on Skylark Holdings?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Skylark Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Skylark Holdings now sits at the center of a clear split in sentiment, with one camp focused on risks and another on rewards. To decide which side you agree with, you may want to start by weighing the company's 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Skylark Holdings?
Skylark Holdings might be on your radar already, yet your portfolio could benefit from a few more targeted ideas pulled from different corners of the market.
Use the Simply Wall St Screener to uncover opportunities that match your risk comfort and income goals before others move on them.
- Target stability first and reduce unpleasant surprises by filtering for 21 resilient stocks with low risk scores that score well on resilience and business quality.
- Hunt for value where quality meets price discipline by searching through the 13 high quality undervalued stocks that combine strong fundamentals with attractive valuations.
- Build a foundation around financial strength by reviewing a list of solid balance sheet and fundamentals (22 results) so you are not relying on fragile capital structures when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com