


- Valmont Industries is set to report its Q3 results after a prior quarter that topped revenue and EPS estimates and came with slightly higher full year revenue guidance.
- The key angle for investors is how expected 6.9% year on year revenue growth will confirm whether current demand momentum is holding across infrastructure and agriculture.
- Now the focus shifts to how Valmont Industries' expected 6.9% revenue growth this quarter could reshape its longer term investment narrative.
Scan how Valmont Industries stacks up against other infrastructure focused manufacturers by reviewing a curated 42 power grid technology and infrastructure stocks that is poised to benefit if demand momentum holds.
Valmont Industries Investment Narrative Recap
To own Valmont Industries, you need to believe its infrastructure and agriculture demand stays resilient enough for the firm to convert its utility opportunity pipeline and agriculture mix shift into steady, higher quality earnings. The near term swing factor is whether Q3 confirms that 6.9% expected revenue growth is coming from healthy utility and irrigation activity, rather than price and backlog timing effects.
The biggest operational risk right now is cost and mix. Inflation in steel, zinc and diesel, together with a two quarter pricing lag, puts pressure on Infrastructure margins, while telecom weakness weighs on that segment. If Q3 commentary suggests those pressures are intensifying, the appeal of Valmont Industries’ medium term margin targets becomes less compelling.
The most relevant development for this earnings setup is management’s prior decision to slightly raise full year revenue guidance after a quarter that exceeded revenue and EPS estimates. That move set a higher bar for delivery. Q3 now tests whether the business can support that outlook with consistent execution in both Infrastructure and Agriculture.
If the reported 6.9% expected revenue growth aligns with that upgraded guidance, investors may view it as evidence that the utility backlog, brownfield expansions and agriculture technology offerings are contributing to top line performance. A softer result, or a cautious tone around telecom or cost inflation, would put more focus on how quickly Valmont Industries can adjust pricing, mix and capital expenditure plans.
Valmont Industries' current analyst narrative points to revenues of US$5.1b and earnings of US$550.5m by 2029, based on an assumed 6.8% yearly revenue growth rate and an earnings increase of about US$44.8m from US$505.7m today.
Discover how Valmont Industries' fair value points to a 39% potential upside from its current price, which some investors believe could materialize sooner than expected.
Exploring Other Perspectives
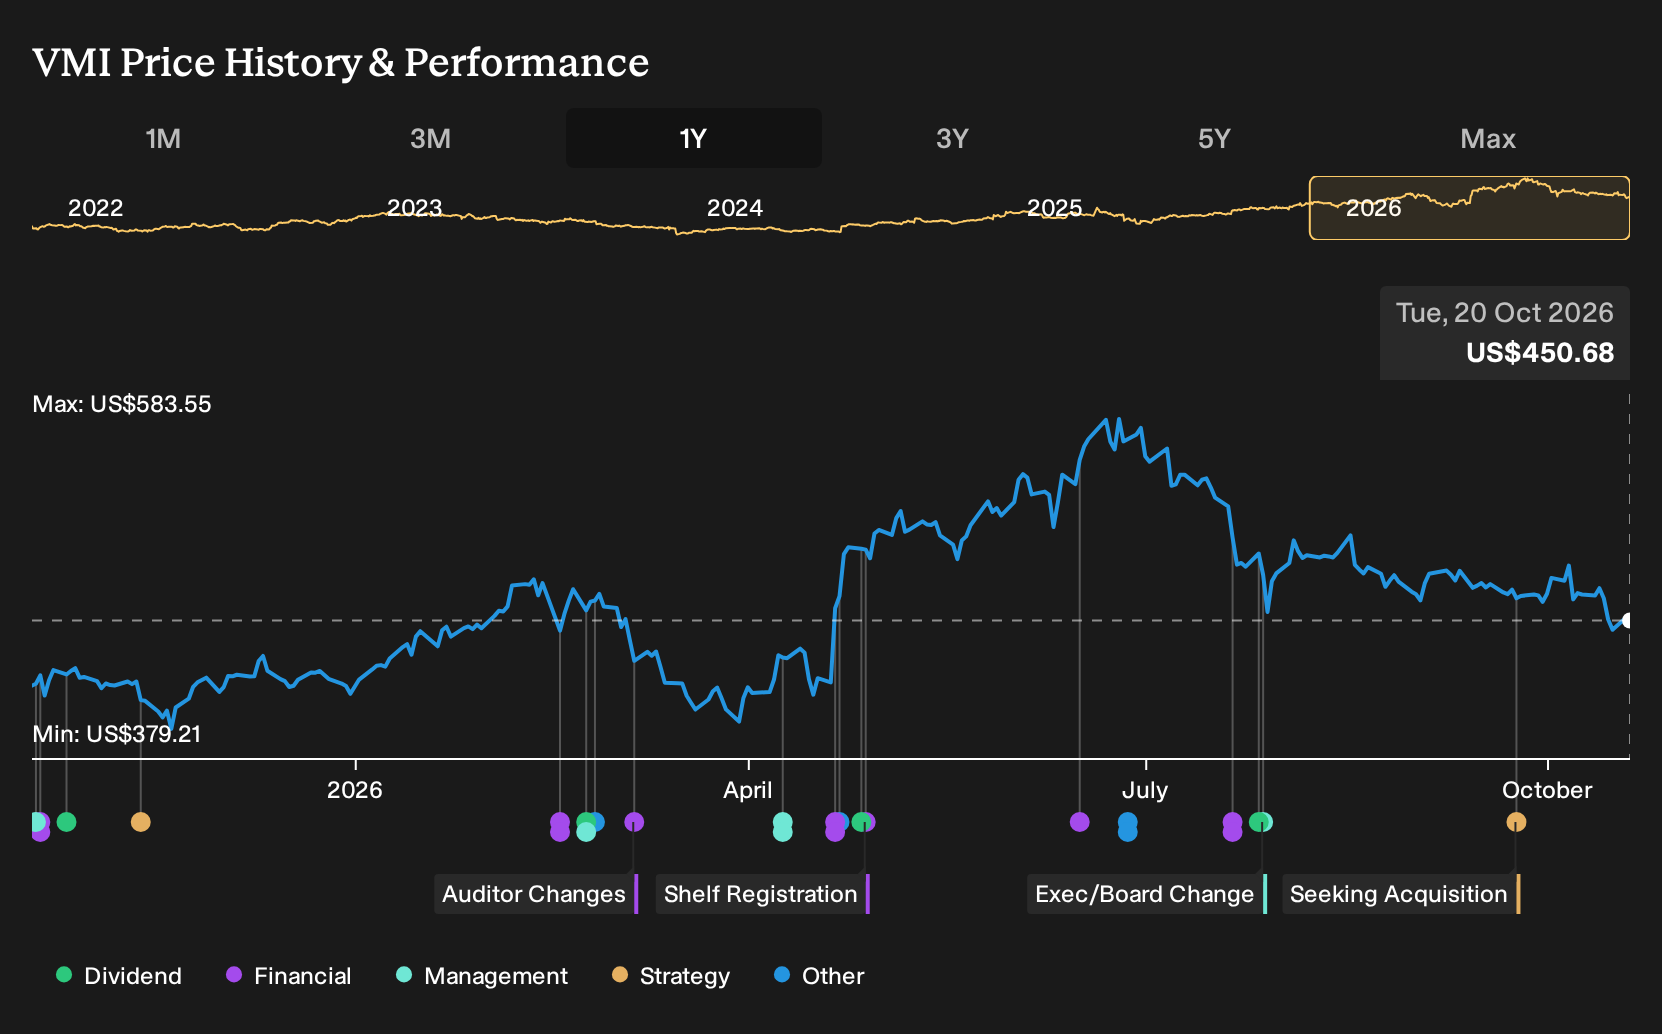
Three fair value estimates from the Simply Wall St Community span a wide band, from US$335 up to about US$624.5, which brackets Valmont Industries’ latest US$452.25 share price. Those private investors are not reflecting the recent target cut to US$519 or current cost and telecom pressures, so you should weigh multiple viewpoints before forming your own stance.
Explore 2 other Valmont Industries fair value estimates, including one that suggests as much as 39% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Valmont Industries research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Valmont Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Valmont Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Valmont Industries?
If the setup around Valmont Industries has sharpened your thinking, use that momentum to scan a wider opportunity set where balance sheets, income statements and risk profiles all line up with your own playbook.
- For investors who care most about paying less for quality, start with a 35 high quality undervalued stocks that filters for stronger fundamentals at prices some would argue look reasonable.
- If capital protection sits higher on your list than headline growth, a 32 resilient stocks with low risk scores can help you narrow in on companies with more resilient profiles and fewer red flags.
- When you want to move beyond the usual watchlists, use a 20 high quality undiscovered gems that surfaces fundamentally solid businesses that many investors may not be focusing on yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com