


Goldman Sachs’ upgrade and Taylor Wimpey (LSE:TW.)’s decision to stop building homes in London arrived together, putting fresh focus on how this £2.76b housebuilder is reshaping risk and capital priorities.
That upgrade landed after a tough stretch for Taylor Wimpey shareholders, with the share price down about 26% year-to-date and the 1-year total shareholder return lower by roughly 20%. However, the recent 1-day and 7-day share price gains of 4.1% and 8.6% hint that sentiment may be starting to improve as the market reassesses risk around London exposure and the new payout policy.
Scan how other UK builders are repositioning after policy shifts and higher costs by comparing Taylor Wimpey with our curated list of 7 high quality undervalued stocks.
Taylor Wimpey now trades around £0.79, with analysts pointing to a price target near £0.87. Is that discount mispricing caution around London and the payout reset, or a fair warning on risk?
Most Popular Narrative: 24% Undervalued
The narrative fair value of £1.05 sits well above Taylor Wimpey’s last close around £0.79. This frames the recent London retrenchment and dividend reset as share-price noise rather than a permanent reset of earnings power.
The UK government's 1.5 million homes pledge could be a tailwind for Taylor Wimpey, boosting its workload and potentially its stock price, provided it navigates cost pressures and the government delivers on planning reforms. The government’s "golden rules" mandate that greenbelt developments include 50% affordable housing, alongside infrastructure like schools and GP surgeries. Taylor Wimpey has experience delivering mixed-tenure schemes (e.g., private sale, affordable rent, shared ownership), which aligns with this policy. While affordable housing typically offers lower margins, the sheer volume of mandated construction could boost overall revenue. Only a third of councils currently have up-to-date local plans, and planning permissions hit a decade-low under the prior system. Reforms aim to fix this, potentially accelerating Taylor Wimpey’s project timelines.
See why 27 investors see Taylor Wimpey as 24% undervalued.
Result: Fair Value of £1.05 (UNDERVALUED)
Still, higher build costs and pressure on affordable housing buyers could yet cap Taylor Wimpey’s margins and slow the pace at which any policy benefits appear.
Find out about the key risks to this Taylor Wimpey narrative.
Another View: Cash Flows Paint A Cooler Picture
The fair value story shifts once you move from earnings multiples to our DCF model. On that lens, Taylor Wimpey, at about £0.79, trades above an estimated future cash flow value of £0.72. This points to the shares looking overvalued rather than discounted. Which lens do you trust more for a builder tied closely to housing cycles?
Look into how the SWS DCF model arrives at its fair value.
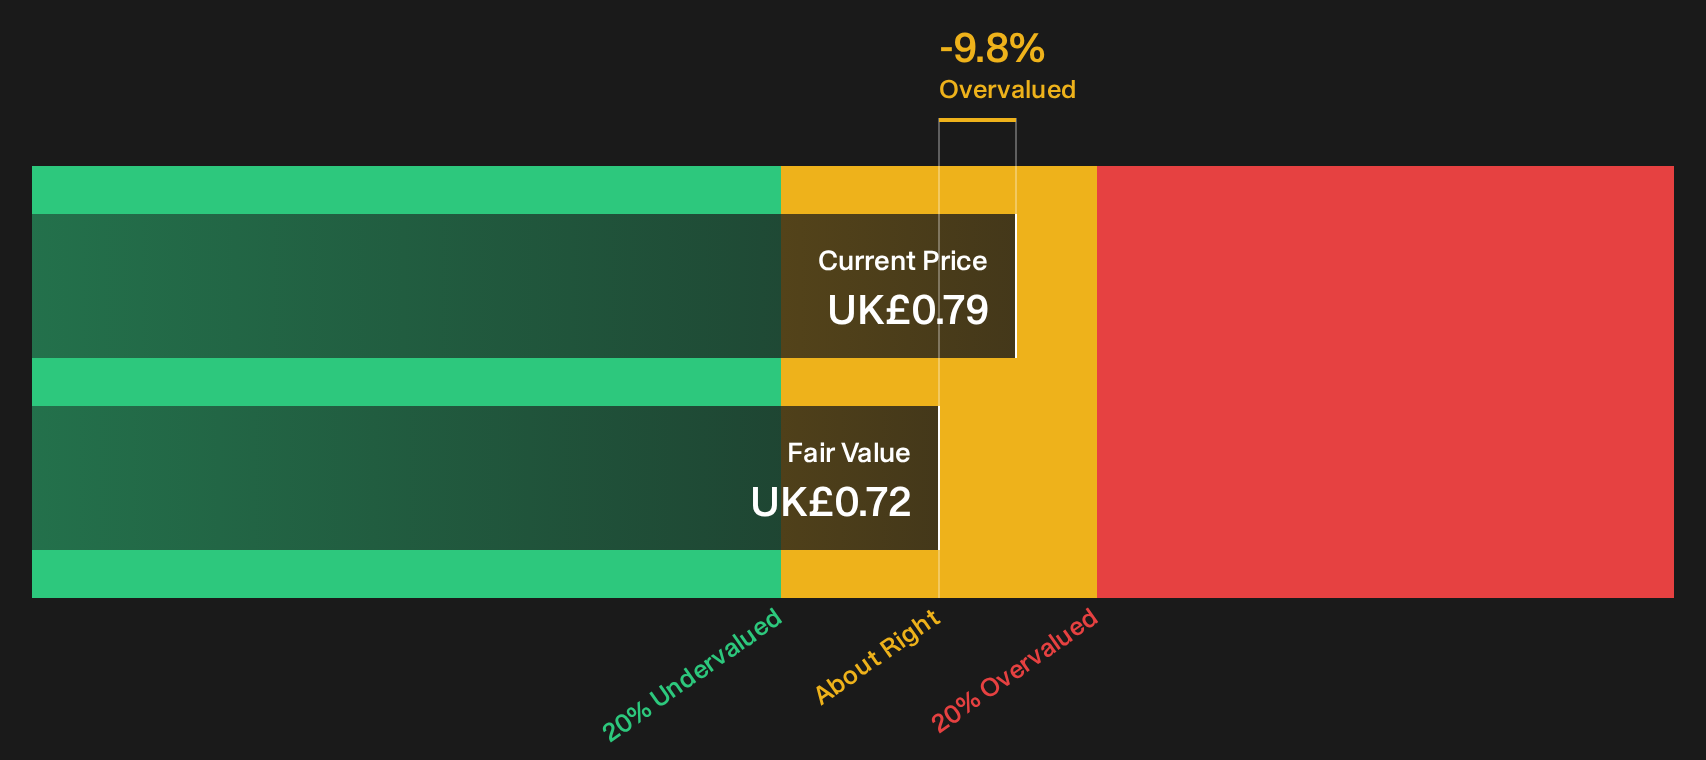
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Taylor Wimpey for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages so far on Taylor Wimpey. Use this as a starting point, act promptly, and weigh both risks and potential benefits by checking the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Taylor Wimpey?
If Taylor Wimpey has sharpened your focus on value and risk, do not stop here. Use the screener to surface fresh opportunities that match your own playbook.
- Target potential bargains by scanning companies our models flag as quality opportunities with 7 high quality undervalued stocks.
- Build a cash flow focused watchlist by reviewing income ideas in the 5 dividend fortresses.
- Prioritise resilience by filtering for companies screened in the 4 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com