


RB Global (RBA) reshuffled its senior bench in October, naming long-time executive Steve Steinberg as Chief Financial Officer and elevating three internal leaders to newly created roles that reshape oversight of finance, digital strategy and core operating units.
Recent trading has been rough for RB Global, with the share price down 26.79% over the past 90 days and 21.68% year to date, while the 1-year total shareholder return declined 17.97%. However, the 3-year and 5-year total shareholder returns of 32.85% and 31.22% hint at longer term resilience despite near term pressure around these leadership changes.
Spot fresh leadership-driven opportunities by lining up RB Global alongside our hand picked 21 high quality undiscovered gems that are also reshaping their business for the next leg of growth.RB Global now trades at a sharp discount to both analyst targets and intrinsic estimates, raising a simple question: Is the market correctly pricing fresh leadership risk, or misreading the spread in front of it?
Most Popular Narrative: 37% Undervalued
RB Global’s most followed narrative points to a fair value near $128.64, well above the last close at $80.90. This places the current leadership shake up squarely against a long-term story built on specific growth levers and capital allocation choices.
Expansion from heavy equipment into sector specific marketplaces such as automotive salvage, government surplus and now agriculture through BigIron increases the range of assets on RB Global platforms and can support higher GTV and service revenue over time as these verticals scale.
Global footprint expansion through contracts in markets such as Australia, the UK and Central America, together with a growing agriculture presence from BigIron, broadens the buyer and seller base and can support higher international GTV contribution and operating leverage.
See why 4 investors see RB Global as 37% undervalued.
Result: Fair Value of $128.64 (UNDERVALUED)
Still, if service fee take rates keep compressing and heavy capital spending delays free cash flow, RB Global’s margin story could quickly become less convincing.
Find out about the key risks to this RB Global narrative.
Another View: RB Global Looks Expensive On Earnings
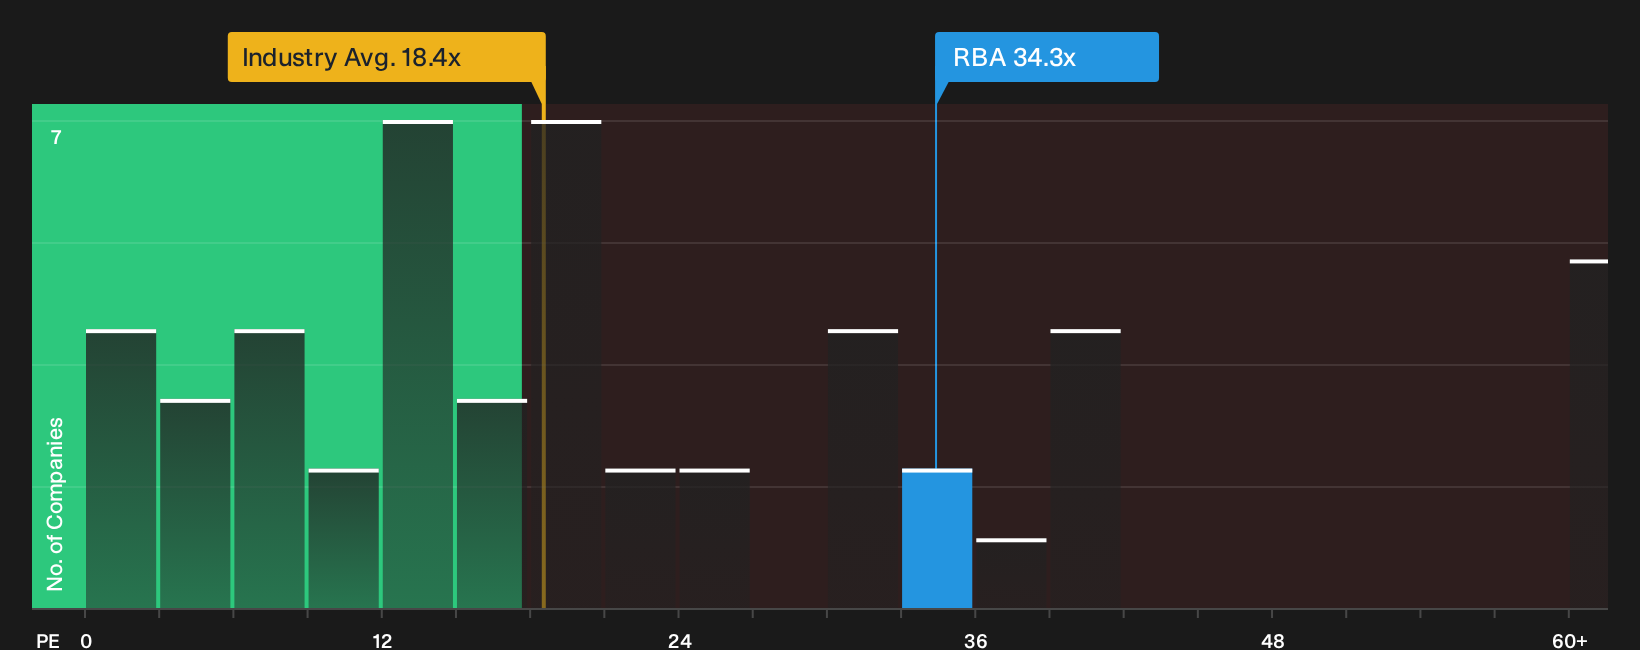
The story shifts when you swap fair value models for a simple P/E lens. RB Global trades around 34.3x earnings, well above the US Commercial Services group at 18.4x and even above its own 27x fair ratio. That wide gap can signal rich expectations, or it can flag valuation risk if sentiment turns.
To see how the numbers stack up when they are run through earnings based ratios rather than long term narratives, take a look at the detailed breakdown in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around RB Global is clearly split. Move quickly, review the numbers for yourself, weigh both sides of the story and study the 5 key rewards and 1 important warning sign
Looking for more RB Global style investment ideas?
RB Global gives useful context, but your portfolio deserves a broader bench of potential opportunities that line up with your own risk, income and valuation preferences.
- Target high quality potential value by scanning companies that combine solid fundamentals with attractive pricing using the 34 high quality undervalued stocks.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help anchor your capital when conditions turn choppy.
- Aim for strong cash returns by studying our hand picked 8 dividend fortresses that focus on higher yielding payouts backed by real businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com