


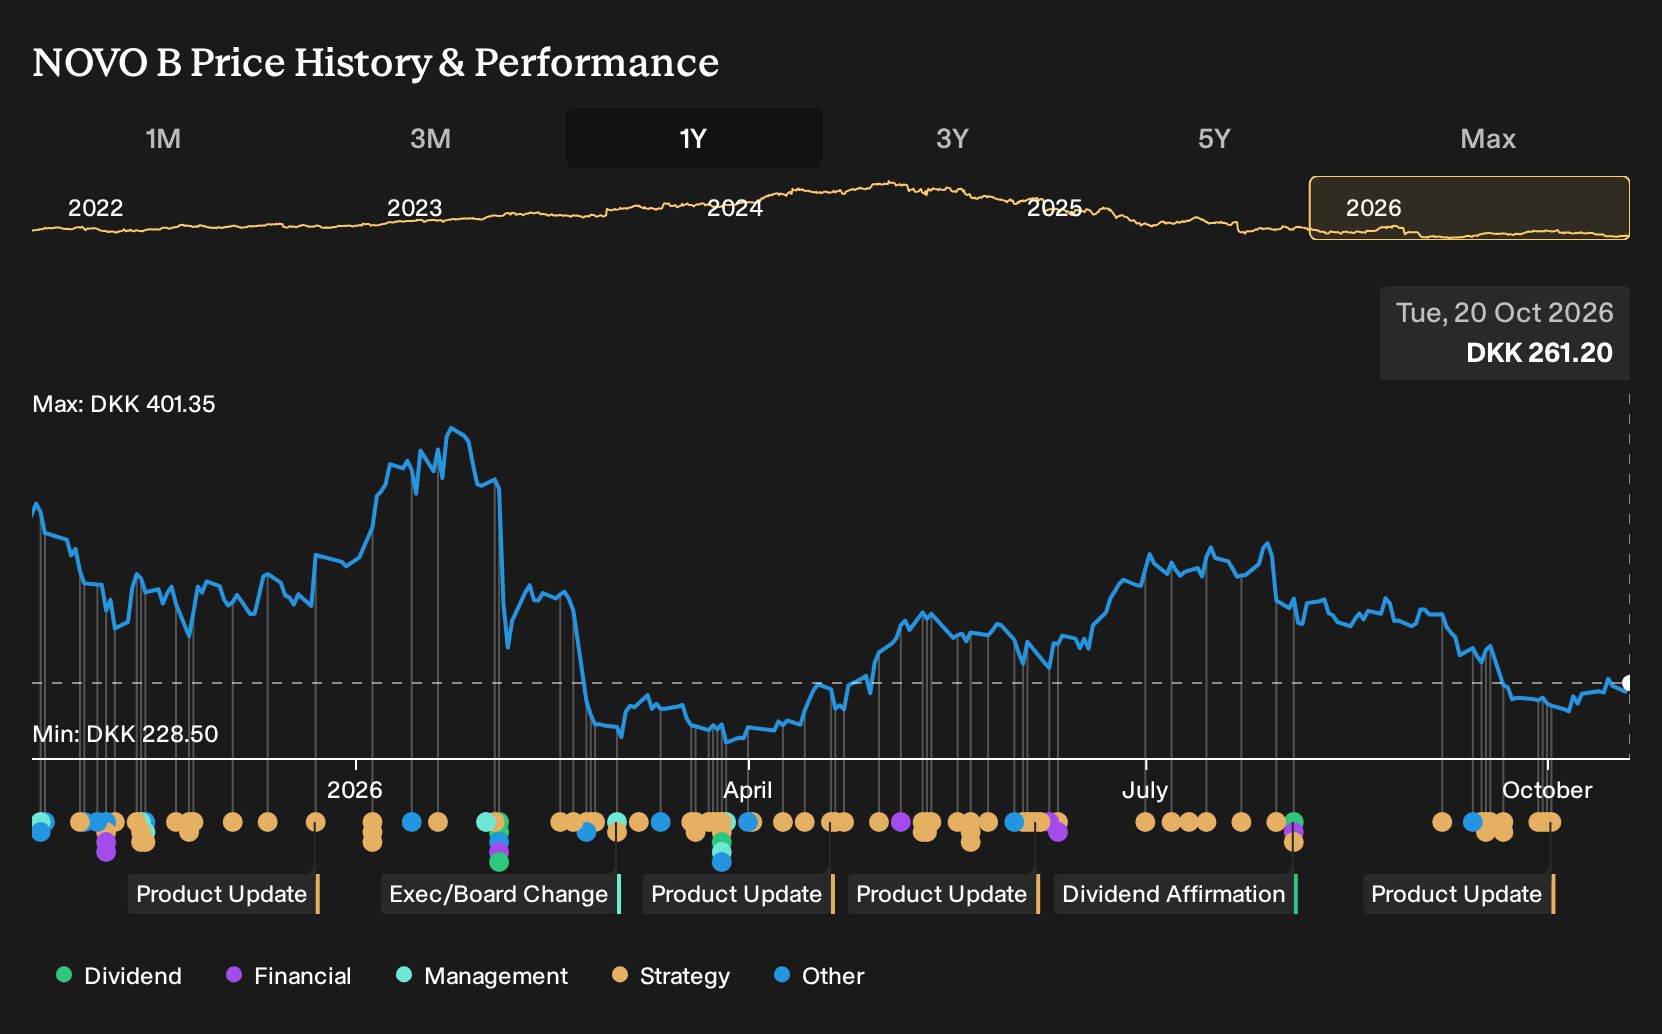
- Eli Lilly’s Foundayo oral obesity and diabetes therapy has received backing from a key European Medicines Agency panel, increasing competitive pressure on Novo Nordisk’s oral semaglutide franchise and adding to concerns about U.S. pricing pressure and softer momentum for the Wegovy pill.
- At the same time, Novo Nordisk is pursuing share buybacks and advancing obesity and cardiometabolic candidates like CagriSema. Investors are weighing expanding GLP-1 capacity and pipeline ambitions against sharper rivalry in its largest treatment areas.
- We will now assess how Novo Nordisk's investment narrative is affected by Foundayo's regulatory progress in Europe and rising GLP-1 competition.
Compare Novo Nordisk's setup with other potential cardiometabolic winners by scanning our curated list of 125 healthcare AI stocks that could benefit as AI reshapes drug development and obesity care.
Novo Nordisk Investment Narrative Recap
To own Novo Nordisk, you need to believe its GLP 1 obesity and diabetes engine can stay resilient while pricing pressure, tougher European competition from drugs like Eli Lilly’s Foundayo and softer Wegovy pill momentum are all in play. In the near term, the key factor is execution on scaling oral Wegovy supply and maintaining share as rivals line up in obesity.
On the risk side, deeper U.S. price erosion or a slower ramp in Wegovy pill demand would hit utilisation of the large capacity build out and could weigh on margins and free cash flow. Foundayo’s progress in Europe raises that risk but does not yet fundamentally change Novo Nordisk’s operational playbook.
The most relevant recent development is Novo Nordisk’s use of AI platforms such as OpenAI’s Rosalind, strengthened by the Orchestra Bio acquisition. Novo Nordisk already uses Rosalind, so any productivity gain here feeds directly into its obesity and cardiometabolic pipeline, where investors are watching for new drugs to diversify beyond current GLP 1 therapies.
Better R&D tooling does not remove the immediate concerns around U.S. pricing, Wegovy pill capacity absorption or Foundayo’s entry. It does, however, give the group more scope to advance candidates such as CagriSema and newer blood and endocrine projects, which many shareholders view as important to balance GLP 1 exposure over time.
Novo Nordisk's current analyst consensus points to DKK 335.4b in revenue and DKK 103.3b in earnings by 2029, with revenues expected to remain fairly flat and profits moving from DKK 116.4b today to that lower level. This implies an earnings decrease of DKK 13.1b over the period.
Uncover why Novo Nordisk's fair value indicates a 17% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on GLP 1 price pressure and more on Novo Nordisk’s potential to hit around DKK 392.6b in revenue and DKK 136.2b in earnings by 2029. You can treat Foundayo’s progress and the OpenAI and Orchestra Bio tie up as fresh information that might nudge those upbeat narratives or challenge them, so it is worth comparing several viewpoints.
Explore 16 other Novo Nordisk fair value estimates, including one that suggests the potential for as much as 226% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research and going with your instincts.
- A great starting point for your Novo Nordisk research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Novo Nordisk. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Novo Nordisk's overall financial health at a glance.
Looking For More Ideas Beyond Novo Nordisk?
If the Novo Nordisk story has sharpened your focus on quality, you can widen the lens and see how other businesses measure up using the Simply Wall St Screener. Build a shortlist that matches your risk tolerance and income goals rather than relying on a single stock.
- For investors who care most about balance sheet strength and resilient fundamentals, start by scanning this curated list of solid balance sheet and fundamentals (202 results) that already clears a basic quality bar.
- If meaningful passive income is your priority, you can filter for companies with higher yields and steadier payout profiles through this targeted 221 dividend fortresses that focuses on established income plays.
- Readers who want a broader watchlist of quality businesses with room to grow can review this hand picked 616 high quality undiscovered gems that highlights lesser known names with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com