


Veidekke (OB:VEI) has just secured a series of sizeable Norwegian construction contracts, including the NOK 520 million NTNU Campus "Resonans" project, adding fresh volume to its confirmed project pipeline and future activity visibility.
These new contracts arrive while Veidekke’s share price has gained 18.15% year to date and 9.87% over the past 90 days, even though the 30 day share price return is down 3.04%, and long term total shareholder returns above 100% indicate that momentum has been building rather than fading.
Scan for other construction and infrastructure stocks showing similar contract momentum to Veidekke using the hand picked list of solid balance sheet and fundamentals (202 results) as a starting universe.
Veidekke now combines a heavier order book with a share price that has already moved sharply higher. Is it better to pay up today for that visibility, or to wait for a cheaper entry and risk missing further rerating as contracts convert into earnings?
Preferred P/E of 16.6x: Is it justified for Veidekke?
Veidekke trades on a P/E of 16.6x, with the NOK207 share price sitting modestly below an internal fair value estimate and supported by strong shareholder returns in recent years.
P/E compares what investors are currently paying for each unit of earnings. For a construction and infrastructure group like Veidekke, this ratio often reflects how much faith the market has in the durability of its project pipeline and profit quality through cycles.
Several elements point to investors accepting a fuller earnings multiple. Earnings grew 32.9% over the past year, ahead of the 11.8% per year rate over five years, and management reports high quality earnings alongside a 3.8% net margin that is above last year. Return on equity of 67.1% is described as outstanding, and forecasts point to revenue growth of 4.6% per year, faster than the wider Norwegian market, even if profit growth of 2.6% per year is expected to trail the broader market.
The 16.6x P/E sits below the peer average of 23x, which suggests investors are paying less for each krone of Veidekke earnings than for comparable companies. At the same time, the stock is described as expensive versus the European Construction industry average P/E of 14.9x, so the market is assigning a premium to the sector benchmark. Internal modelling also indicates a fair P/E of 15.9x, so the current level is slightly richer than that reference point and could adjust if sentiment or results change.
Explore the SWS fair ratio for Veidekke.
Result: Price-to-earnings of 16.6x (ABOUT RIGHT)
Still, the Veidekke story could shift quickly if new contract awards slow or if current projects run into cost overruns that pressure its 3.8% net margin.
Find out about the key risks to this Veidekke narrative.
Another view on Veidekke's valuation
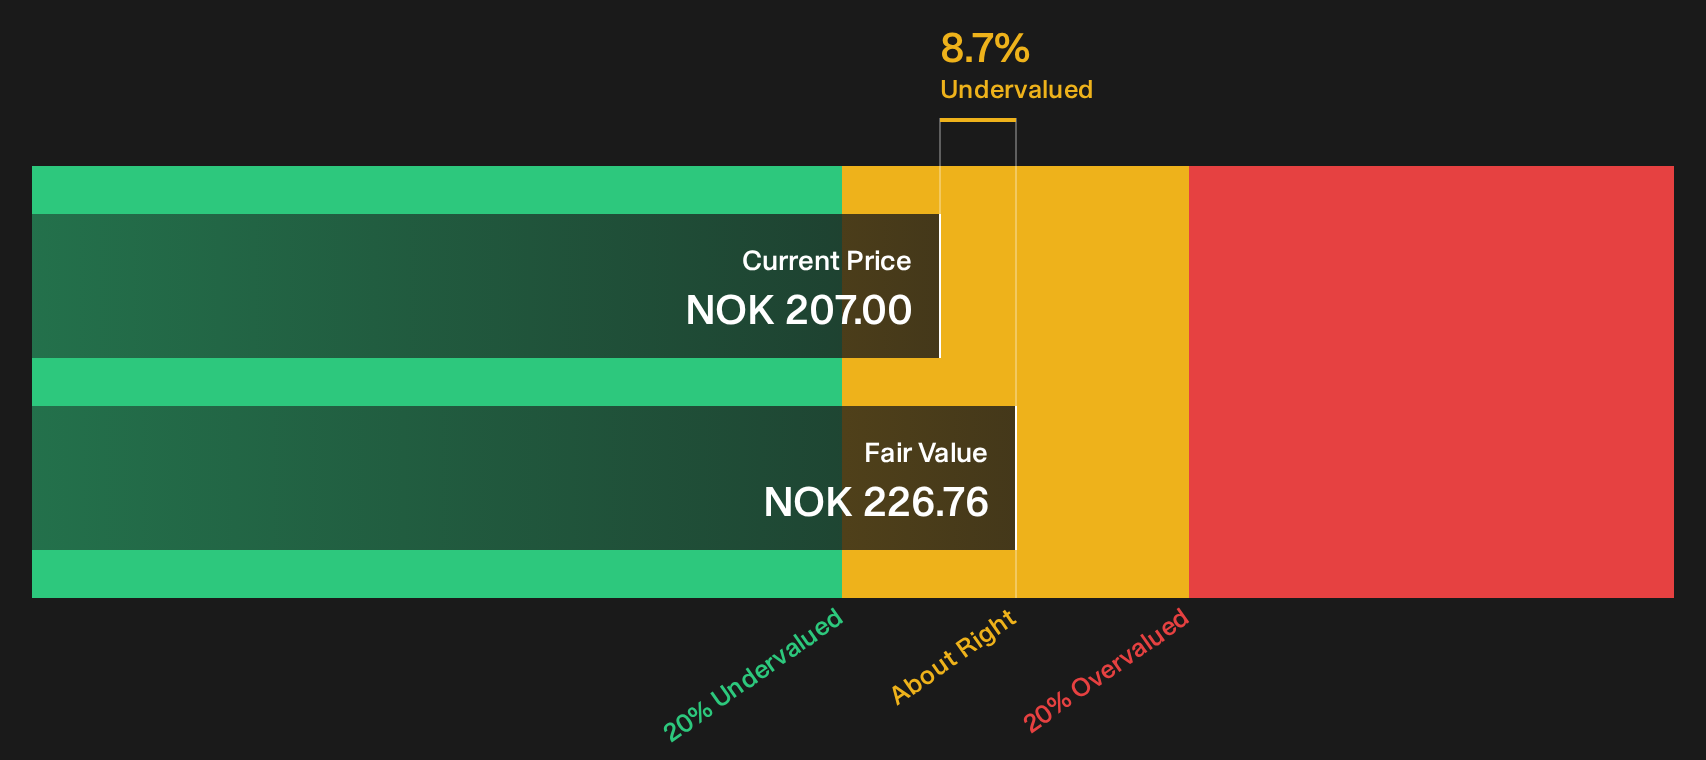
The P/E argument points to Veidekke as roughly fairly priced, yet the SWS DCF model tells a different story. With the share at NOK207 and a cash flow based value of NOK226.76, the framework flags the stock as undervalued. Which signal should matter more for you, earnings or cash flows?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Veidekke for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 188 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the combination of new contracts, fair value signals and risk flags around Veidekke leaves you uncertain, act promptly and pressure test the numbers yourself using the full breakdown of 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Veidekke?
Do not stop your research with Veidekke. The strongest portfolios usually pull from several clear themes, each backed by hard numbers and disciplined selection.
- Spot potential mispricings early and use the 188 high quality undervalued stocks to find candidates that combine quality fundamentals with prices that lag underlying business strength.
- Build a steadier income stream and turn to the 221 dividend fortresses for companies that pair higher yields with balance sheets that aim to support regular payouts.
- Protect the downside first and lean on the 228 resilient stocks with low risk scores to surface businesses that score well on resilience while still offering room for upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com