


Fortrea Holdings (FTRE) has just closed its purchase of the Early Phase Services division from Worldwide Clinical Trials, expanding its early clinical development footprint and drawing fresh attention to a stock that has already delivered a sharp 115.8% one year return.
Recent trading has reflected renewed interest in Fortrea Holdings, with a 30 day share price return of 13.79% and a 90 day gain of 16.82% contributing to a year to date share price increase of 35.51% and a 1 year total shareholder return of 116.54%. However, the 3 year total shareholder return is still down 16%, indicating strong momentum over the past year as investors respond to acquisitions, resilient bookings commentary and an improving clinical pipeline while reassessing both growth potential and risk around the stock.
Scan how Fortrea Holdings compares with other contract research and healthcare service stocks that screen well on cash flow, balance sheets, and valuation signals inside the 34 high quality undervalued stocks.
After a gain like this, plus a fresh acquisition in early phase trials, the question on Fortrea Holdings now is whether today’s price still leaves enough upside to justify the risks.
Most Popular Narrative: 11% Overvalued
Analysts following Fortrea Holdings see fair value around $20.55, which sits below the recent $22.78 close and frames a market that already prices in a lot of good news.
Fortrea is well positioned to benefit from global demographic changes (such as aging populations and increased healthcare access in emerging markets), demonstrated by robust demand for its clinical pharmacology services and strong execution on large-scale trials. This is expected to support sustainable top-line revenue growth.
See why 8 investors see Fortrea Holdings as 11% overvalued.
Result: Fair Value of $20.55 (OVERVALUED)
Still, cracks in the story remain, including heavy reliance on a handful of large customers and a very high implied future P/E multiple that could reset quickly.
Find out about the key risks to this Fortrea Holdings narrative.
Another View: Fortrea Holdings on Sales-Based Valuation
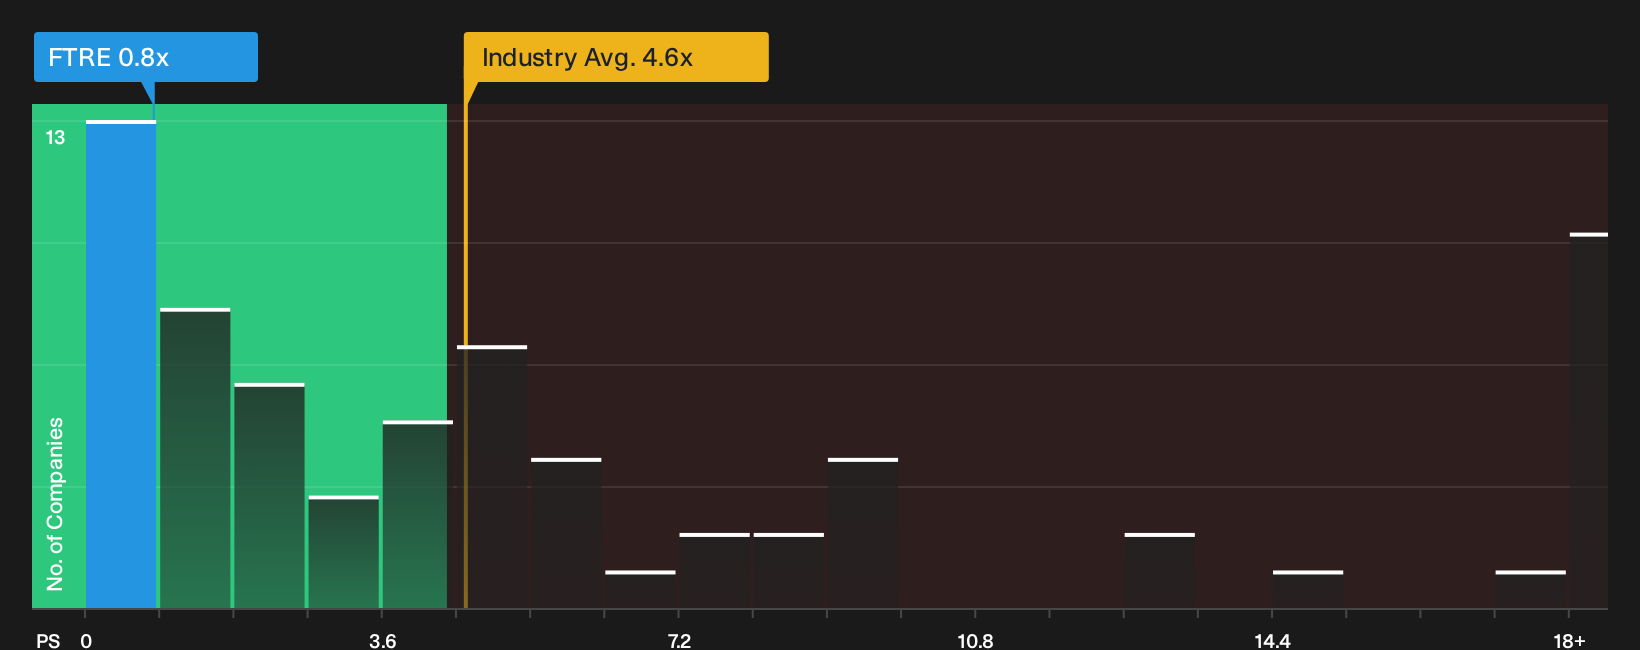
On earnings assumptions, Fortrea Holdings screens as overvalued versus the $20.55 analyst fair value. On sales, the picture is very different. The stock trades on a P/S of just 0.8x, while the US Life Sciences industry sits around 4.6x and peers average 25.9x.
The fair ratio for Fortrea is estimated at 2.4x P/S, which is a much higher level than where the shares change hands today and implies the market is heavily discounting execution and profitability risk. The question for investors is whether that discount fairly reflects the uncertainties or overshoots them.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Fortrea Holdings so far. Move quickly, stress test the numbers against your own expectations, then weigh up the 3 key rewards and 1 important warning sign.
Looking for more Fortrea Holdings sized ideas?
Do not stop your research with one ticker. Broaden your watchlist with fresh setups that match your risk tolerance, cash flow priorities, and return goals.
- Target resilient compounding potential by scanning companies that combine strong cash generation with sensible valuations using the 34 high quality undervalued stocks.
- Prioritise sleep-at-night portfolios by filtering for businesses that carry lower risk profiles through the 31 resilient stocks with low risk scores.
- Spot future standouts early by hunting for underfollowed quality using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com