


- In October 2026, AST SpaceMobile announced that Deutsche Telekom, Orange, Telefónica and Vodafone signed a Letter of Intent to explore a joint bid for Mobile Satellite Services spectrum in Europe. The initiative aims to support service readiness for more than 500 million mobile subscribers.
- The planned use of AST SpaceMobile’s BlueBird satellites and dedicated European ground infrastructure could allow Telefónica to extend its existing mobile services into areas without reliable coverage while keeping data and service control within European jurisdiction.
- We will now assess how Telefónica's investment narrative could be affected by this joint Mobile Satellite Services spectrum initiative in Europe.
Scan other telecom and connectivity stocks that are positioned for coverage expansion by reviewing our hand picked 42 power grid technology and infrastructure stocks.
Telefónica Investment Narrative Recap
To own Telefónica, you need to believe the heavy investment in fiber, 5G and B2B digital services can translate a currently unprofitable, highly leveraged profile into steadier cash generation. The short term focus is still on improving margins and cash flow, while revenue is expected by analysts to edge slightly lower over the next few years.
Debt remains the biggest operational overhang, with interest costs not well covered by earnings and a dividend that analysts flag as not well supported. The new Mobile Satellite Services initiative may help Telefónica improve coverage and product depth, but it does not directly solve leverage or competitive pressure in Spain, Germany, the UK and Latin America.
The AST SpaceMobile Letter of Intent is the clearest recent development tied to Telefónica's long term infrastructure story. If execution goes to plan, space based connectivity could sit alongside fiber and 5G as another way to widen service reach without building traditional towers in every rural pocket. That fits the existing push into more premium connectivity offerings and digital services.
For you as a shareholder, the operational question is whether this kind of partnership can eventually support better economics in markets where pricing is tight and revenue growth is muted. Telefónica is already working to simplify its footprint and modernize networks to lift margins. The MSS spectrum effort adds another moving piece that could help service quality, but it still competes for capital with debt reduction and core network projects.
Telefónica's current analyst narrative points to revenues of €34.4 billion and earnings of €2.4 billion by 2029, based on a projected yearly revenue decline of 1.7% and an earnings swing of €4.9 billion from a loss of €2.5 billion today.
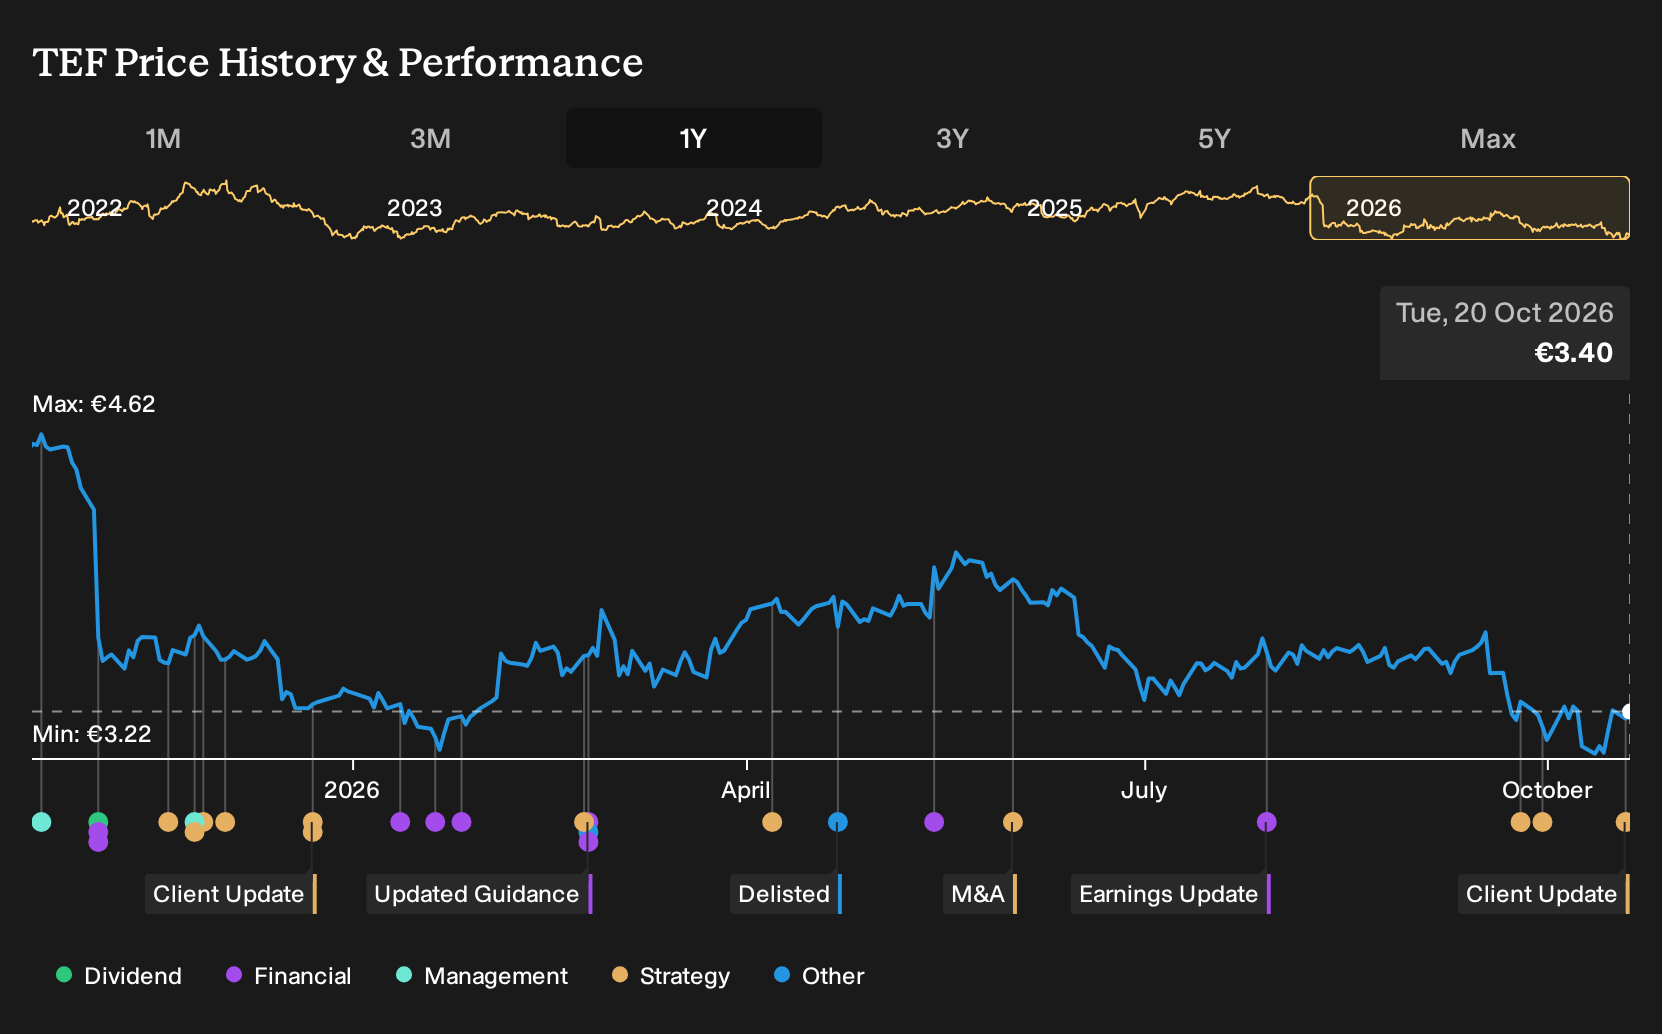
Uncover why Telefónica's fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts already saw Telefónica as a beneficiary of heavier data usage, with pre news forecasts pointing to roughly flat revenues near €35.9b and earnings of €3.5b by 2029. You might read this MSS spectrum move as reinforcing that upbeat view, or you might question it. Either way, opinions differ widely. Treat this as a prompt to compare several narratives before deciding how this news could reshape your own expectations.
Explore 2 other Telefónica fair value estimates, including one that suggests as much as 72% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Telefónica research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Telefónica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Telefónica's overall financial health at a glance.
Looking For More Ideas Beyond Telefónica?
If this Telefónica story has you rethinking your watchlist, it can help to line it up against other opportunities that match your risk tolerance, income needs, or value focus. The Simply Wall St Screener gives you a quick way to filter for stocks that fit your own brief instead of relying on headlines.
- For investors who want potential mispricing with quality fundamentals, compare Telefónica with a wider set of value ideas by scanning 188 high quality undervalued stocks.
- If capital preservation matters more than headline-grabbing growth, narrow your search to companies that score well on resilience and review the 228 resilient stocks with low risk scores.
- Income focused investors who care about durability as much as yield can focus on sturdier payers by checking out the 221 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com