


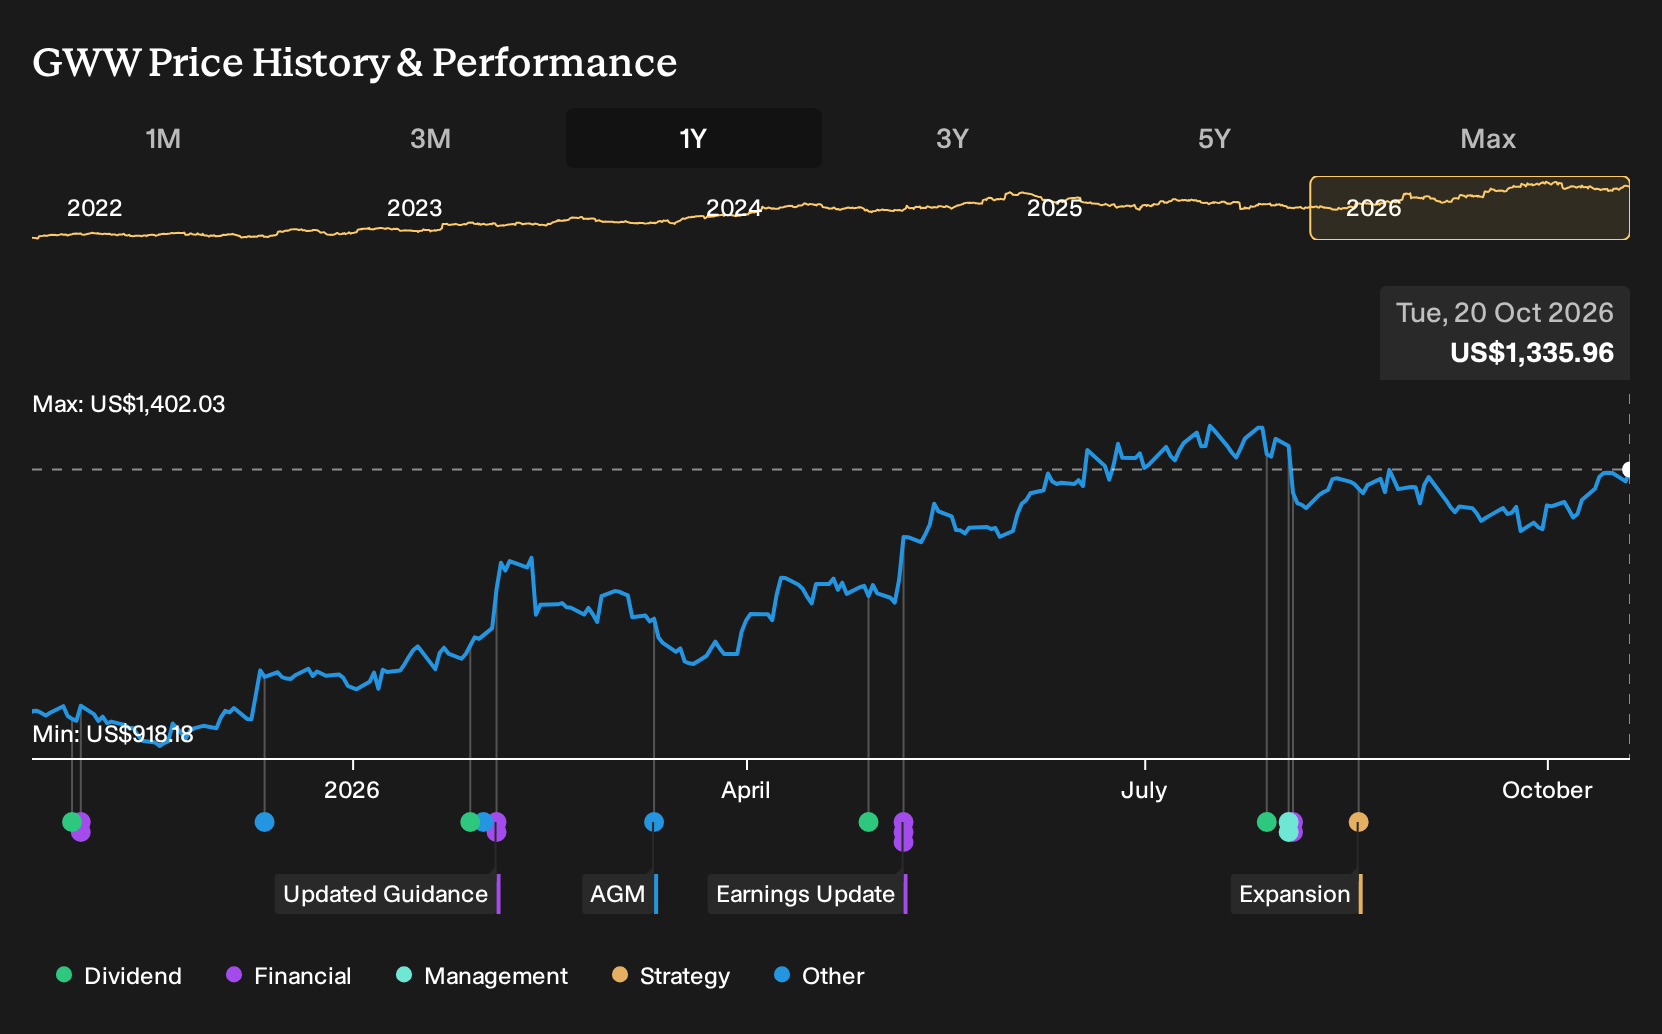
- Recent commentary on W.W. Grainger highlights a track record of earnings surprises, with the last two quarters exceeding estimates by 6.47% and 14.22%, alongside a positive Earnings ESP and a Zacks Rank of 2 that point to constructive expectations for the next report.
- The interesting angle for investors is how consistent outperformance versus forecasts reinforces confidence in Grainger’s underlying operations, suggesting analysts view its scale, supply chain investments, and B2B e commerce execution as key supports for profitability even before the next set of results arrives.
- We will now look at how W.W. Grainger’s earnings surprise history and upbeat expectations could influence its broader investment narrative.
W.W. Grainger Investment Narrative Recap
To stay invested in W.W. Grainger, you need to believe the distribution engine, from high touch branches to Endless Assortment platforms, can keep turning scale into resilient earnings. The recent streak of earnings surprises speaks to that execution, but does not remove the reliance on continued distribution expansion, pricing discipline, and e commerce growth as key near term supports.
The biggest swing factor right now sits in margins. Higher freight, fuel, and private label inventory costs can still pressure profitability if pricing windows do not fully offset them. The recent upside to earnings does not eliminate this risk. It provides fresher evidence on how effectively Grainger is managing the squeeze for now.
With no fresh corporate announcements tied directly to this earnings setup, the most relevant reference point remains Grainger's focus on supply chain expansion and automation. The new Northwest Distribution Center in Oregon and the planned Houston facility for 2028 show how the business is trying to hard wire more efficient fulfillment and better service levels into its model.
These logistics projects matter because they intersect directly with current catalysts and risks. Better automation and coverage can help blunt elevated freight and fuel costs over time and support Endless Assortment growth. Execution missteps, cost overruns, or slower benefits from these facilities would leave earnings more exposed to rising logistics and input costs than recent results might suggest.
W.W. Grainger's narrative projects US$23.2b revenue and US$2.7b earnings by 2029. This assumes 7.2% yearly revenue growth and an earnings increase of about US$0.8b from US$1.9b today.
Uncover why W.W. Grainger's fair value is essentially consistent with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into W.W. Grainger’s Endless Assortment catalyst. Before this latest earnings buzz, they were penciling in revenue of about US$24.0b and earnings of US$2.9b by 2029. That is far above consensus, and this fresh report could easily push those narratives in either direction.
Explore 2 other W.W. Grainger fair value estimates, including one that suggests it could be worth as much as $1332.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your W.W. Grainger research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for W.W. Grainger. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate W.W. Grainger's overall financial health at a glance.
Looking For More Investment Ideas Beyond W.W. Grainger?
If you want to stress test your view on W.W. Grainger, one of the best checks is to compare it with other businesses that have different balance sheet strength, income profiles, and risk levels using the Simply Wall St screener.
- For investors focused on stability first, compare W.W. Grainger against a 31 resilient stocks with low risk scores that may better fit a capital preservation mindset.
- If you are looking for companies with strong fundamentals that the market may not fully appreciate yet, review a 21 high quality undiscovered gems that could complement a holding like Grainger.
- For those building around quality and financial resilience, compare W.W. Grainger with a list of solid balance sheet and fundamentals (25 results) to see how its profile stacks up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com