


- DoorDash has recently expanded its marketplace by adding Macy's and other large retailers, while also opening a new hub in India to grow its employee base and support broader international operations.
- The push into non restaurant retail and a larger global workforce signals management's focus on scaling DoorDash's platform reach rather than focusing solely on restaurant delivery economics.
- We will examine how DoorDash's investment narrative is affected by this retail expansion effort and the new India hub build out.
Scan how DoorDash’s retail push compares with other platform plays by reviewing the hand-picked 21 high quality undiscovered gems that may be building similar under-the-radar ecosystems.
DoorDash Investment Narrative Recap
To own DoorDash, you need to believe this is growing into a broad local commerce platform where grocery, retail, subscriptions and ads steadily add to restaurant delivery. The recent retail partnerships and India hub fit that picture operationally, but Q3 earnings still look like the near term proof point. The main near term risk remains pressure on profitability from regulatory outcomes, Dasher support programs and affordability constraints in grocery and non restaurant delivery.
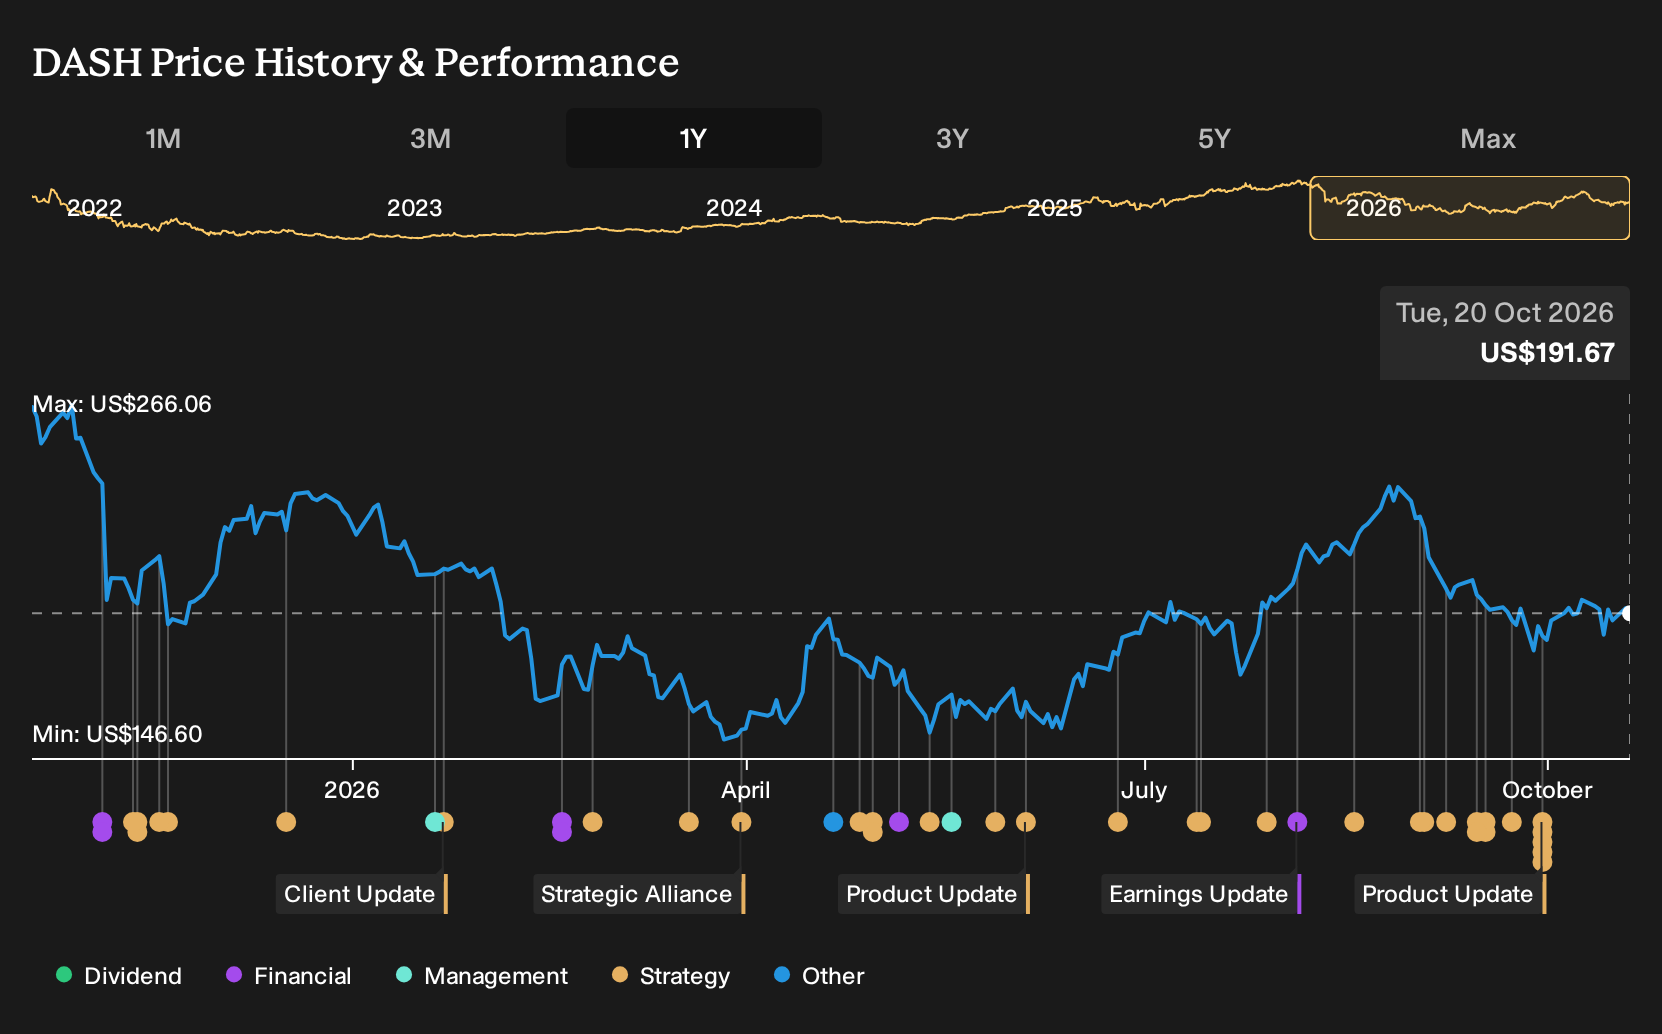
The stock has pulled back about 27% over the past year and trades below analyst price targets, so expectations already look more cautious. That setup cuts both ways. If revenue and earnings keep lining up with current forecasts and newer verticals stay on track to reach gross profit positivity by the second half of 2026, the recent news likely reinforces, rather than changes, the short term narrative.
The expansion into grocery and other non restaurant categories is the announcement that matters most in this context. Management has guided that these newer areas are the fastest growing segment and could turn gross profit positive by the second half of 2026. The Macy's partnership and broader retail push feed directly into that thesis by potentially lifting order density, ad inventory and subscription value across the DoorDash ecosystem.
Execution risk sits in the details. Affordability in online grocery and retail, ongoing regulatory scrutiny around Dasher pay and programs like temporary gas rewards currently costing about US$50 million each quarter in 2026 can all weigh on margins if conditions stay tough. The India hub ramps fixed costs and complexity as well, so investors will likely watch upcoming earnings for signs that higher revenue, advertising mix and automation offset those pressures.
DoorDash Forecasts and Valuation Check
DoorDash's narrative projects US$28.0b in revenue and US$3.8b in earnings by 2029. That profile aligns with analyst assumptions of 20.8% yearly revenue growth and implies an earnings increase of roughly US$3.0b from US$841.0m today.
Uncover how DoorDash's fair value indicates a 34% potential upside to its current price that may not be available for long.
Exploring Other Perspectives
Regulatory risk sits at the center of the most bearish DoorDash story. Where consensus looks for US$3.8b in earnings by 2029, the lowest analysts frame a much cooler path near US$2.9b on roughly US$27.4b of revenue. Those views were set before this retail and India hub news, so treat them as starting points and explore how opinions might shift.
Explore 7 other DoorDash fair value estimates, including one that suggests it could be worth just $226.02.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your DoorDash research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DoorDash. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DoorDash's overall financial health at a glance.
Looking For More Investment Ideas Beyond DoorDash?
If the DoorDash story has sharpened your thinking about platform businesses, it can help to line it up against a few other opportunities that match different risk and income profiles. The Simply Wall St Screener is built for exactly that kind of side by side comparison so you can pressure test your thesis and spot alternatives that fit your own goals.
- If capital preservation ranks high on your list, consider filtering for companies with steadier risk profiles using our 31 resilient stocks with low risk scores.
- Income focused investors who want payouts backed by stronger fundamentals can scan for higher yielding opportunities through the 8 dividend fortresses.
- Readers hunting for less crowded opportunities with solid financials can cast a wider net with the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com