


Investor attention around Quaker Chemical (KWR) has picked up after management issued positive guidance for fiscal 2026, citing meaningful expected revenue and adjusted EBITDA growth supported by new business wins and disciplined cost control.
Quaker Chemical shares have climbed over the year, with a year to date share price return of 13.68% and a 1 year total shareholder return of 20.05%. The latest move to about $157.97 reflects fresh optimism around the updated earnings outlook, even as the 5 year total shareholder return remains down 31.88% and highlights how recent momentum is still rebuilding from a weaker longer term base.
Scan for other materials stocks showing similar earnings momentum and disciplined cost control using our curated list of 34 high quality undervalued stocks.
Quaker Chemical is suddenly back on investor radar after that guidance and a near US$158 share price. Is this where you commit fresh capital, or wait and hope for a cheaper entry before the next move?
Most Popular Narrative: 18% Undervalued
Quaker Chemical's most followed narrative pegs fair value at $192.57, which sits well above the latest $157.97 close and places the recent guidance upgrade within a longer multi year earnings rebuild.
The main factor that needs to go right is successful execution of the multi year cost and business transformation program that targets at least $20 million to $30 million of structural savings and sustainably higher EBITDA margins.
See why 8 investors see Quaker Chemical as 18% undervalued.
Result: Fair Value of $192.57 (UNDERVALUED)
Still, the Quaker Chemical story depends on cost savings arriving on schedule and Americas margins improving. Both of these factors could disappoint if operational issues drag on.
Find out about the key risks to this Quaker Chemical narrative.
Another View: Quaker Chemical Through The P/E Lens
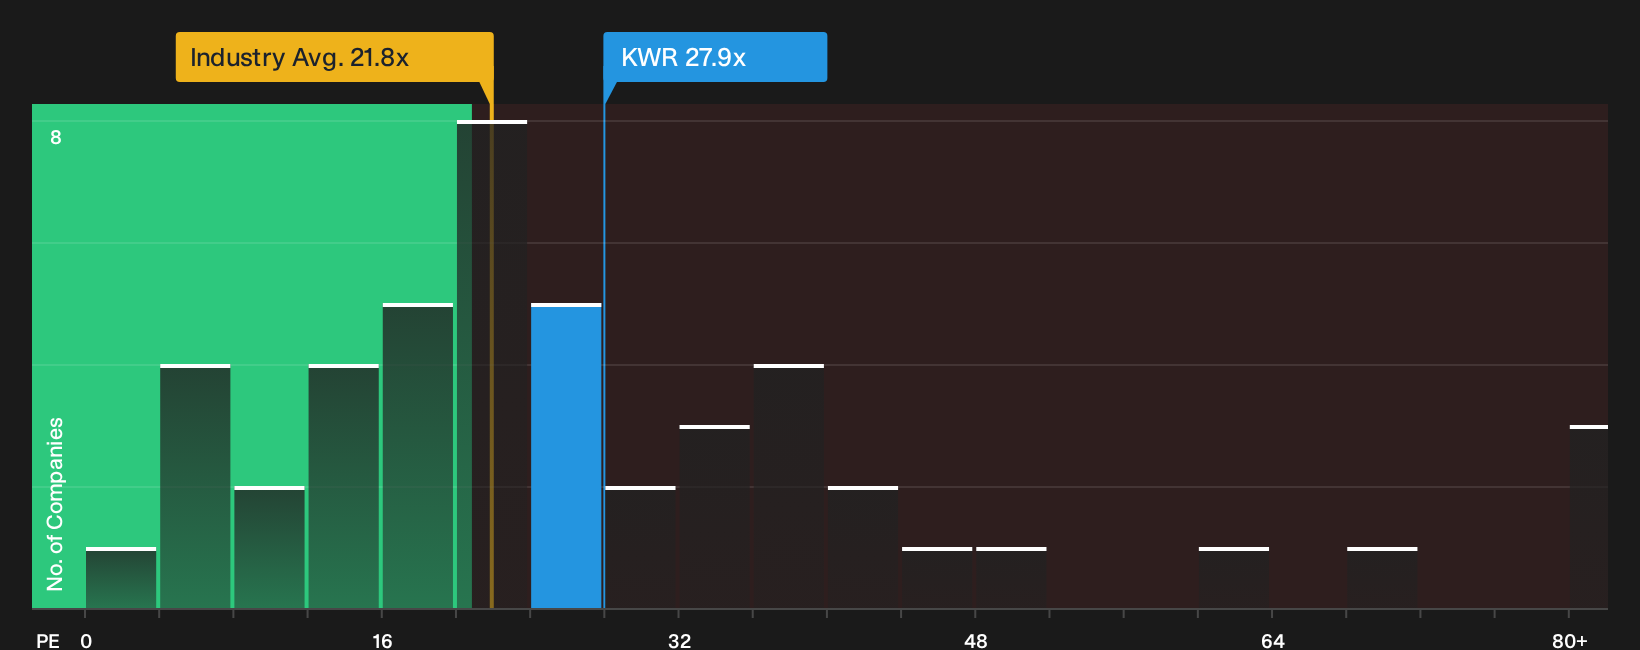
The fair value story around Quaker Chemical gets more complicated once the current P/E is brought into the picture. At about 27.9x earnings, the stock trades above the US Chemicals sector on 21.3x, ahead of peer averages on 24.9x, and also above its own fair ratio of 22.3x. That gap points to valuation risk if expectations on earnings growth and margin expansion are not met.
Numbers like these can help you decide whether valuation stretch is acceptable, or if you would rather focus on companies where the ratio already lines up closer to the fair ratio. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these rarely stay unresolved for long, so consider reviewing the numbers for yourself and weighing both sides of the story through 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Quaker Chemical?
If you stop with Quaker Chemical, you miss a wider field of opportunities where pricing, income potential, and balance sheet strength can work harder for you.
- Target potential mispricings early by scanning companies that screen as high quality and potentially undervalued using our focused list of 34 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that combine higher yields with resilient payouts through the curated set of 8 dividend fortresses.
- Lean into resilience by filtering for financially robust companies with clean balance sheets using the dedicated list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com