


- GSK received U.S. FDA accelerated approval for Jemperli, originally discovered using AnaptysBio technology, to treat adults with stage II and III MSI-H/dMMR locally advanced rectal cancer. The approval is backed by AZUR-1 data showing sustained clinical complete responses and a safety profile consistent with prior use across solid tumors.
- This new label expansion reinforces the royalty potential of Jemperli for AnaptysBio and highlights how immunotherapy can offer some patients an option that may avoid chemotherapy, radiation and surgery, which often carry permanent quality-of-life trade-offs.
- We will look at how AnaptysBio's investment narrative is influenced by Jemperli's new rectal cancer indication and its expanding royalty footprint.
Scan how the Jemperli decision fits into the broader hunt for oncology and biotech breakouts by zeroing in on our hand picked 21 high quality undiscovered gems list.
What Is AnaptysBio's Investment Narrative?
The simple version of the AnaptysBio story is belief in a lean royalty and licensing model. The business currently leans on Jemperli economics with US$106.1m of royalty management revenue, a P/E of 3.9x against peers at 40.7x and analyst expectations for roughly 30% annual top line growth. The recent FDA approval for the new rectal cancer indication fits that thesis by broadening the potential royalty base without adding heavy capital needs, while Quimilza and other partnered assets shape the rest of the near term catalyst path.
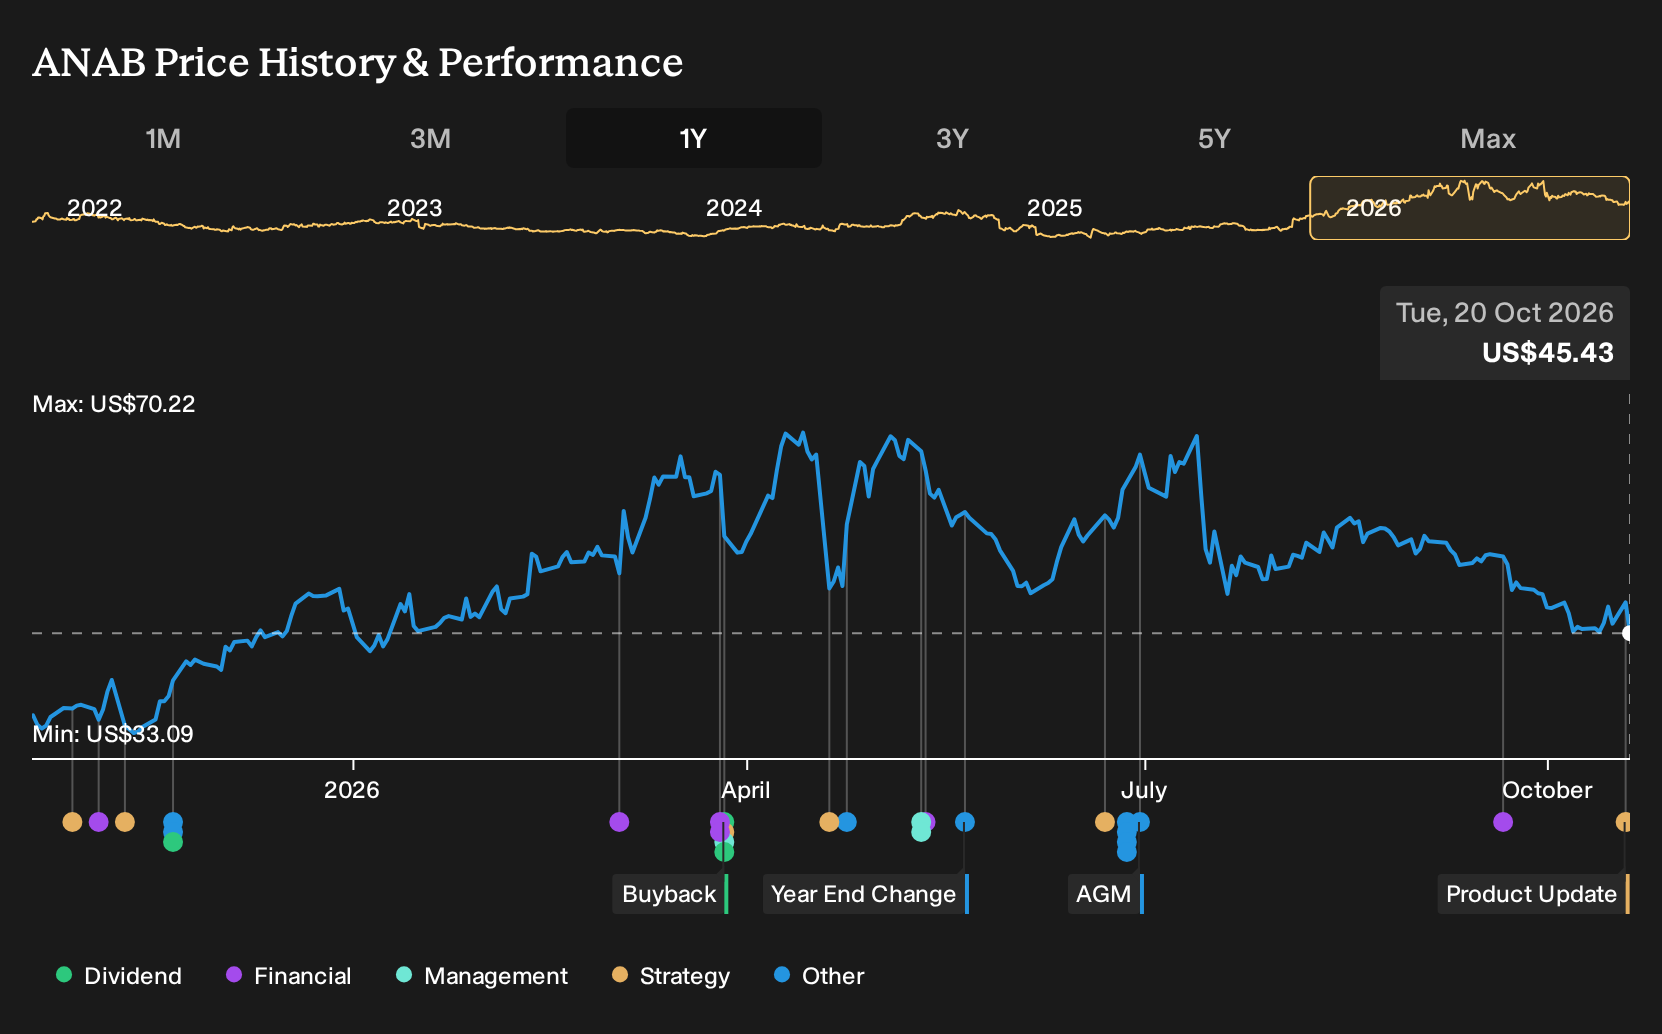
Execution risk sits mostly in partner performance, deal quality and balance sheet resilience rather than bricks and mortar expansion. Earnings are forecast to drift slightly lower despite revenue expectations, interest cover is tight and a high level of non cash earnings clouds profit quality. If Jemperli uptake in this new setting tracks more slowly than hoped, near term enthusiasm around AnaptysBio’s valuation gap and its roughly 1 year share price run, up about 100%, could meet the harder reality of cash flow timing.
That said, alongside the Jemperli win and apparent value on traditional metrics, one uncomfortable piece of the AnaptysBio story still sits in plain sight...
There's only one way to know the right time to buy, sell or hold AnaptysBio. Head to Simply Wall St's company report for the latest analysis of AnaptysBio's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community has only three fair value views on AnaptysBio, yet they stretch from about US$87 to roughly US$169 per share, a huge spread for such a small sample. Those opinions were set before the Jemperli approval, so you are effectively weighing stale models against a fresh oncology catalyst. That gap is exactly why it can help to compare several community viewpoints before considering how this story fits your own expectations.
Explore 2 other AnaptysBio fair value estimates, including one that suggests as much as 273% upside from the current price!
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider forming your own view based on your research.
- A great starting point for your AnaptysBio research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AnaptysBio. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AnaptysBio's overall financial health at a glance.
Looking For More Investment Ideas Beyond AnaptysBio?
If the AnaptysBio story has sharpened your sense of what you want in a biotech holding, it can help to compare it against a wider set of opportunities using the Simply Wall St Screener.
- Focus on quality at a discount by scanning companies that currently screen as 34 high quality undervalued stocks based on their fundamentals.
- If capital preservation sits high on your list, filter for 31 resilient stocks with low risk scores that aim to keep volatility and financial red flags in check.
- Prefer sturdier balance sheets before taking on fresh equity risk, and use the list of solid balance sheet and fundamentals (25 results) to find businesses with stronger financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com