


As European markets navigate the complexities of elevated energy prices and geopolitical tensions, investor focus has shifted towards corporate fundamentals, with the pan-European STOXX Europe 600 Index advancing 2.09% in local currency terms. In this environment, growth companies with strong insider ownership can offer a compelling investment case, as they often align management interests with those of shareholders and may be better positioned to weather market uncertainties.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.9% |
| OSE Immunotherapeutics (ENXTPA:OSE) | 23% | 73.3% |
| Kuros Biosciences (SWX:KURN) | 23.7% | 65.6% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 36.7% | 89.8% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 19.4% | 41.1% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.4% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 35.6% |
We're going to check out a few of the best picks from our screener tool.
Banijay Group (ENXTAM:BNJ)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Banijay Group N.V. operates in content production, distribution, online sports betting, and gaming across the United States, Europe, and internationally with a market cap of €3.43 billion.
Operations: The company's revenue is primarily derived from its Entertainment and Live segment, which generated €3.23 billion, and its Sports Betting and Gaming segment, which contributed €2.02 billion.
Insider Ownership: 10.1%
Earnings Growth Forecast: 23.9% p.a.
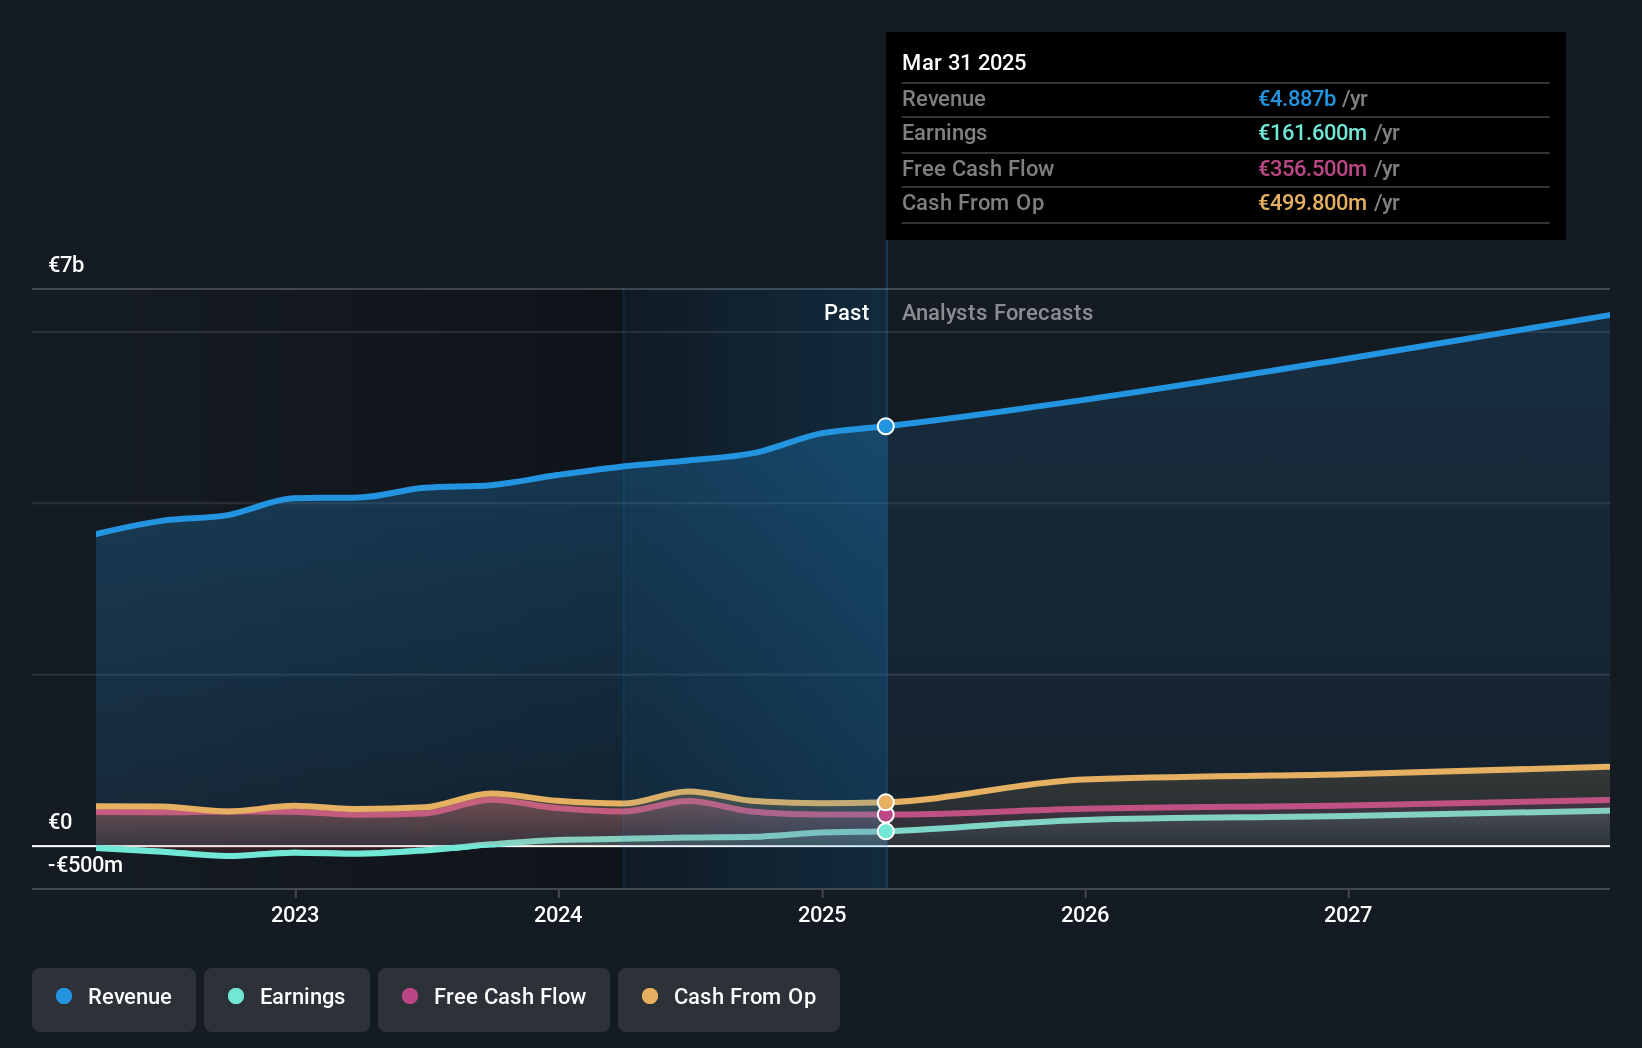
Banijay Group, with significant insider ownership, is poised for growth. Despite a recent dip in net income to €61 million for the first half of 2026, earnings are forecasted to grow significantly at 23.95% annually over the next three years. The appointment of Antoine Jouteau as CEO of Banijay Gaming aims to accelerate growth and innovation. Although trading below fair value estimates by 67.7%, interest payments remain a concern due to limited earnings coverage.
- Dive into the specifics of Banijay Group here with our thorough growth forecast report.
- Insights from our recent valuation report point to the potential undervaluation of Banijay Group shares in the market.
Creotech Instruments (WSE:CRI)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Creotech Instruments S.A. is a Polish company that manufactures and sells satellites, satellite systems, and subsystems, with a market cap of PLN2.35 billion.
Operations: The company's revenue segments include Space Projects generating PLN165.62 million, Electronics Production contributing PLN2.51 million, and Satellite data and Unmanned Aerial Vehicle technologies adding PLN2.23 million.
Insider Ownership: 31.1%
Earnings Growth Forecast: 62.9% p.a.
Creotech Instruments, with significant insider ownership, reported a substantial increase in net income to PLN 692.14 million for Q2 2026, showcasing high-quality earnings despite volatility in share price. Revenue is expected to grow at 43.4% annually, outpacing the Polish market average of 5.3%. Earnings are projected to rise significantly by 62.92% per year over the next three years, while trading at a notable discount of 82.2% below estimated fair value suggests potential investment appeal.
- Click to explore a detailed breakdown of our findings in Creotech Instruments' earnings growth report.
- Our comprehensive valuation report raises the possibility that Creotech Instruments is priced lower than what may be justified by its financials.

PSI Software (XTRA:PSAN)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: PSI Software SE develops software products to optimize energy and material flows for utilities and industries globally, with a market cap of €698.71 million.
Operations: The company's revenue is primarily derived from Grid & Energy Management (€152.16 million), Process Industries & Metals (€68.31 million), Logistics (€35.79 million), and Discrete Manufacturing (€34.93 million).
Insider Ownership: 31.4%
Earnings Growth Forecast: 114.8% p.a.
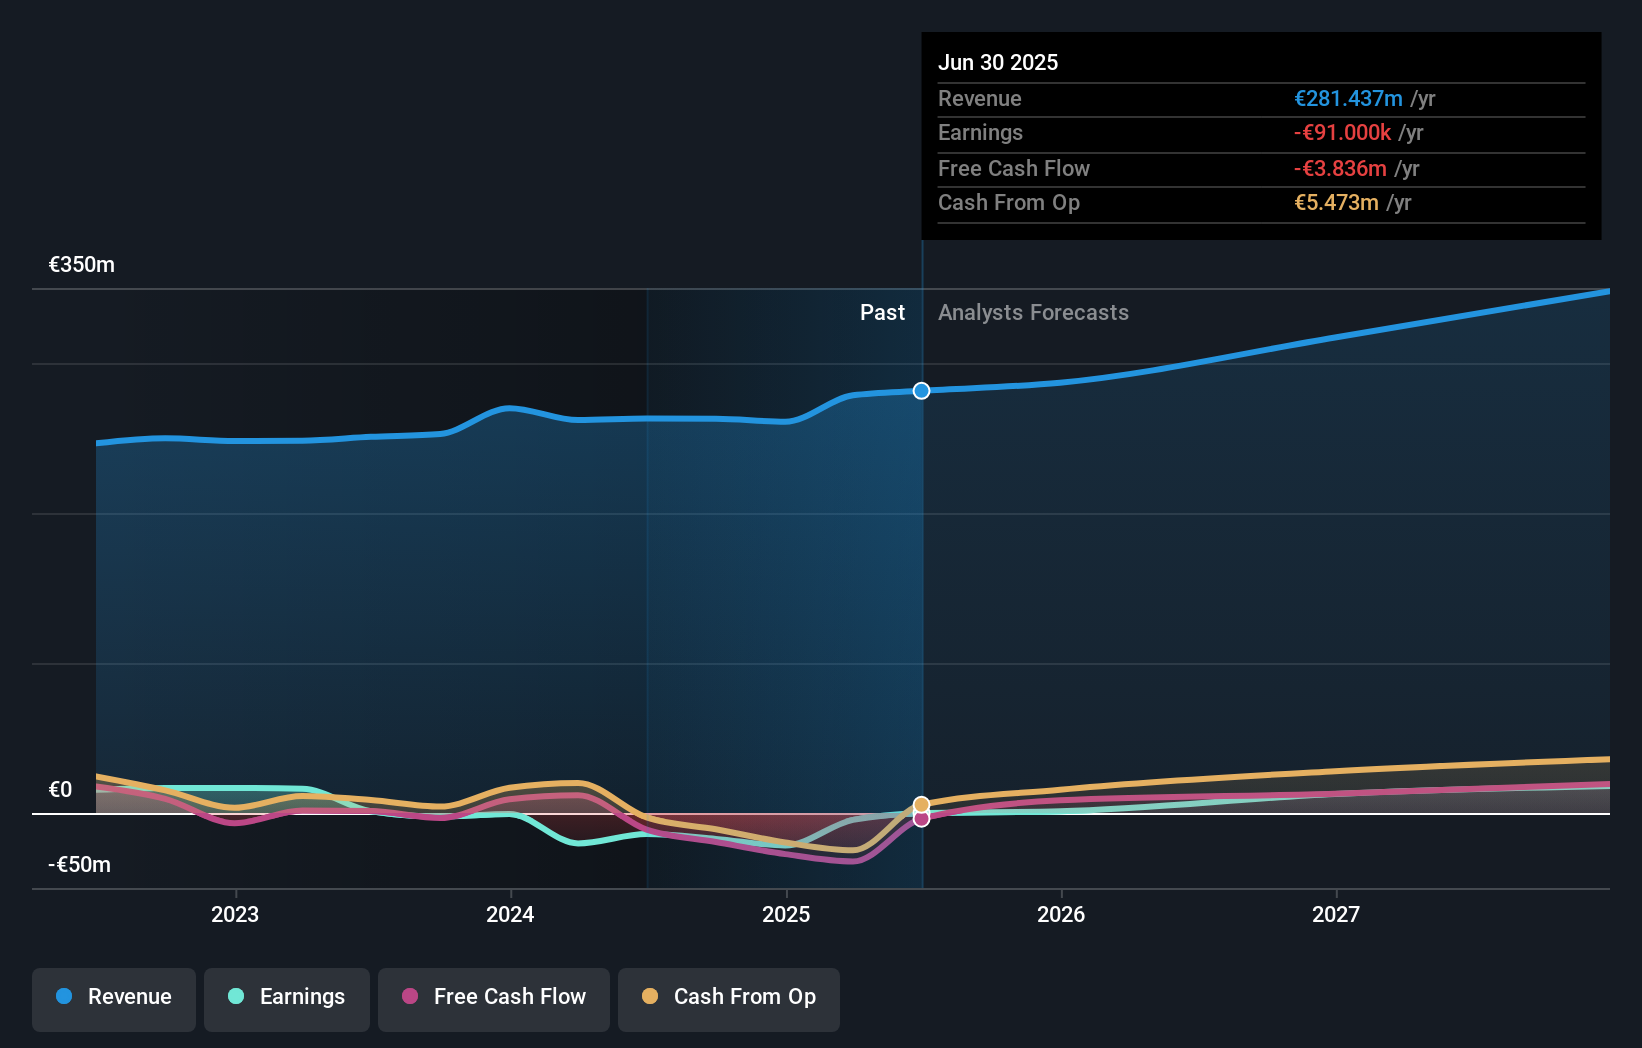
PSI Software is set to benefit from a strategic partnership with Warburg Pincus, aiming for sustainable growth. Despite recent losses, PSI's revenue is forecast to grow faster than the German market at 8.3% annually, with profitability expected in three years. The company faces delisting following an acquisition offer by Warburg Pincus, which may affect share liquidity and price transparency but aligns with long-term growth strategies supported by insider ownership changes.
- Delve into the full analysis future growth report here for a deeper understanding of PSI Software.
- The analysis detailed in our PSI Software valuation report hints at an inflated share price compared to its estimated value.
Taking Advantage
- Delve into our full catalog of 204 Fast Growing European Companies With High Insider Ownership here.
- Ready To Venture Into Other Investment Styles? These 23 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com