


- Kennametal has recently reported two consecutive quarters where earnings exceeded analyst estimates, and analysts now assign the company a positive Earnings ESP ahead of its next scheduled earnings release on 4 November 2026.
- The pattern of recent earnings outperformance, paired with a positive Earnings ESP, points to operating execution that appears to be running ahead of what consensus models had built in.
- We will look at how Kennametal's investment narrative aligns with expectations for another strong earnings report based on recent outperformance.
Kennametal Investment Narrative Recap
To own Kennametal, you need to believe the tooling and hard materials business can keep turning cost cuts, portfolio clean up and tungsten integration into reasonably steady earnings, even as commodity timing benefits fade. The recent earnings beats suggest operations are currently tracking well against that goal, but the core thesis still rests on execution in Metal Cutting and Infrastructure, not on quarterly surprises alone.
The main near term swing factor remains how quickly restructuring savings and product investments offset any normalization in margins linked to tungsten and mix. The biggest risk is softer demand in key end markets like energy, earthworks, aerospace and transportation at the same time as free cash flow is pressured by working capital and interest costs. The latest earnings strength does not remove that risk; it just buys Kennametal a bit more breathing room.
Against this backdrop, the recent pattern of earnings outperformance is the announcement that matters most. It directly tests whether Kennametal’s cost actions, digital machining efforts and portfolio tilt toward aerospace and defense are turning into real operating progress rather than just a tungsten pricing benefit visible on paper.
For catalysts, those beats intersect with management’s multi year restructuring program that targets US$125 million of run rate savings by fiscal 2028 and US$110 million by fiscal 2027. Consistent delivery against those milestones, together with evidence that earnings quality improves despite forecasts for declining profit over the next three years, is what you want to watch into the 4 November 2026 report.
Kennametal earnings and valuation setup into 2029
Kennametal's narrative projects US$3.6b revenue and US$273.0 million earnings by 2029. That path assumes 15.0% yearly revenue growth and an earnings decrease of US$69.4 million from US$342.4 million today.
For anyone tracking the story into the next few earnings reports, those figures act as the scoreboard. Analysts are effectively saying the business needs to grow the top line at a healthy clip while accepting a thinner margin structure that leaves profit below where it is today.
The forecast margin compression from 14.5% to 7.6% means investors are being asked to underwrite a Kennametal that is larger in sales but lighter in profitability. That mix matters because it shapes how much free cash flow might be available for debt reduction, buybacks or higher dividends if management sticks to current capital allocation habits.
On valuation, the consensus view ties that 2029 profile of US$3.6b in revenue and US$273.0 million in earnings to a future P/E of 11.8x. At a current P/E of 7.3x, the implied setup is that the market would pay a higher multiple for a company with lower margin but more balanced end markets and a cleaner cost base.
The price target spread between US$27.0 and US$38.0 shows that specialist coverage is split on how much credit to give those assumptions. A reader who thinks the restructuring and tungsten integration can hold margins above the 7.6% consensus might see that 11.8x multiple as conservative, while anyone expecting tougher cycles in energy, earthworks, aerospace or transportation may treat the US$273.0 million earnings bar as optimistic.
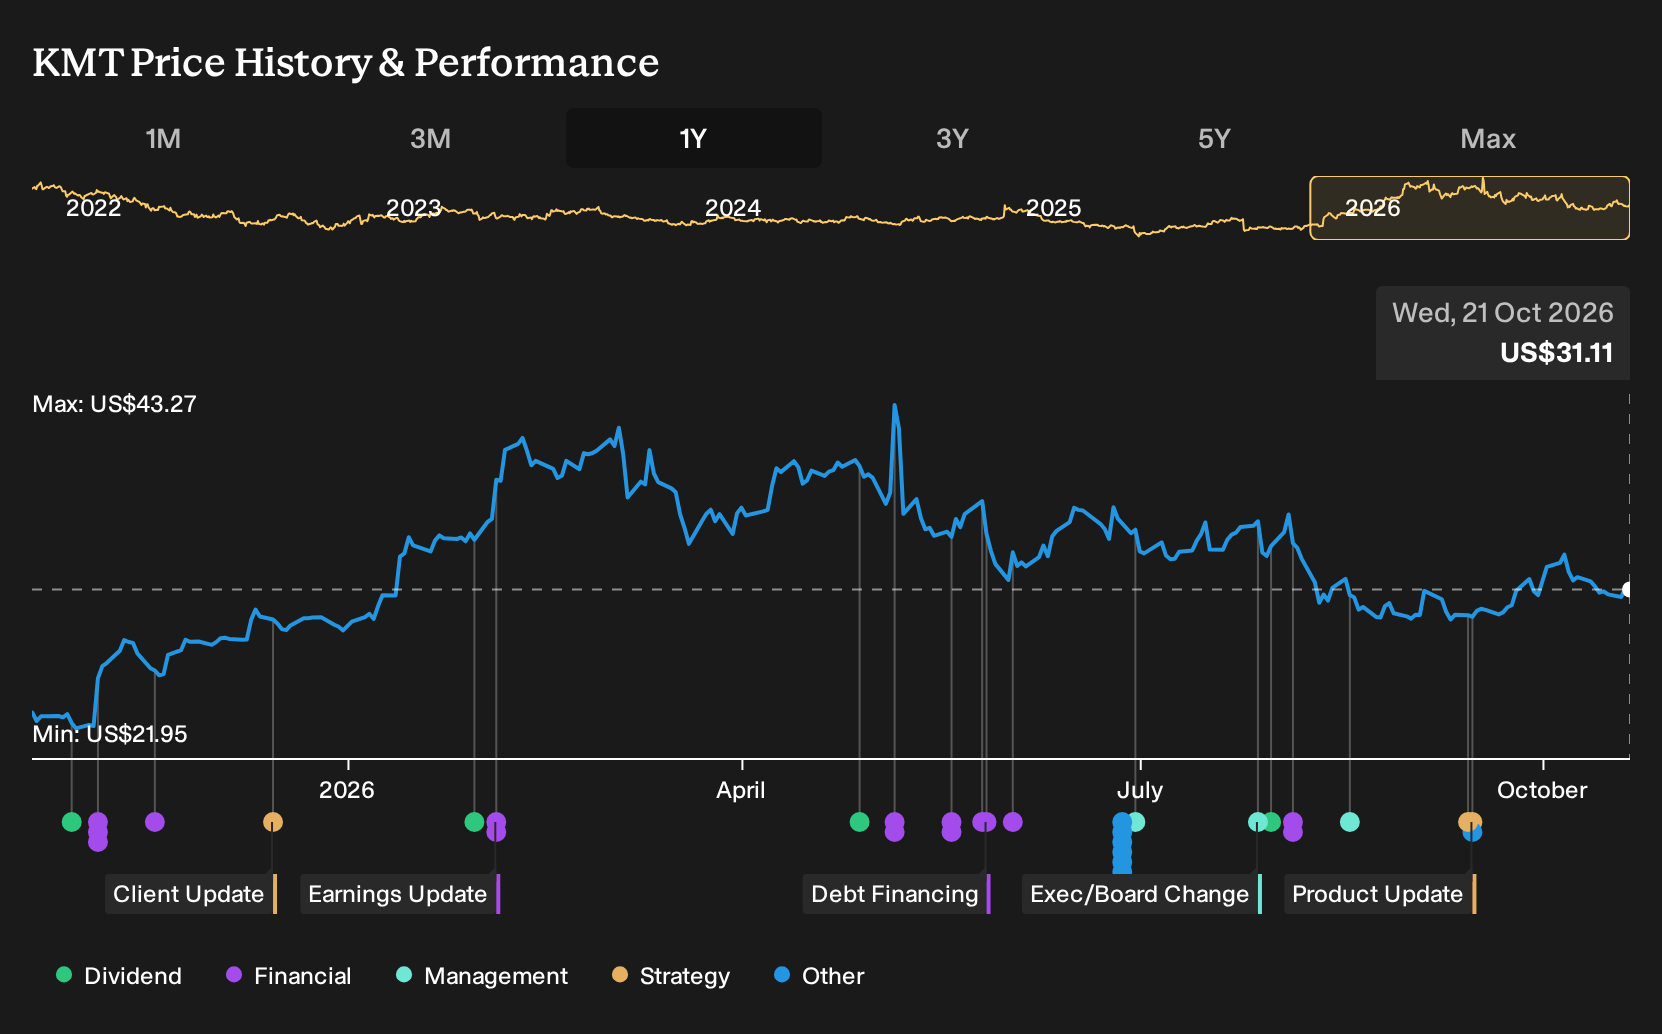
Because the analyst consensus price target of US$32.43 sits only 0.5% below the current US$32.60 share price, the market is not baking in a dramatic swing in either direction. For portfolio decisions, that kind of setup usually pushes the focus back to execution in Metal Cutting and Infrastructure and to whether Kennametal can translate its restructuring program into higher quality earnings rather than just near term beats against quarterly estimates.
Uncover why Kennametal's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Kennametal leans hard into tungsten risk. The most bearish analysts were looking for earnings of about US$268.5 million on US$3.6b revenue by 2029 and a 10.1x P/E. That setup paints a more compressed margin story. You can weigh that against the recent earnings beats and decide which narrative might now shift.
Explore 2 other Kennametal fair value estimates, including one that suggests it could be worth just $31.43.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kennametal research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Kennametal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kennametal's overall financial health at a glance.
Looking for more Kennametal sized investment ideas?
If the Kennametal story has helped sharpen your thinking, you can apply the same approach across the market by running a few focused screens on Simply Wall St. Target the traits you care about most and let the data surface candidates that deserve a closer look next to KMT in your watchlist.
- If capital preservation matters most to you, start with companies that pair stability with measured upside by checking out 31 resilient stocks with low risk scores.
- For investors who want financial resilience front and center, scan the list of solid balance sheet and fundamentals (25 results) that can better handle tougher operating conditions or funding costs.
- If you are hunting for quality that is not widely followed yet, broaden your watchlist with a 21 high quality undiscovered gems that may still be flying under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com