


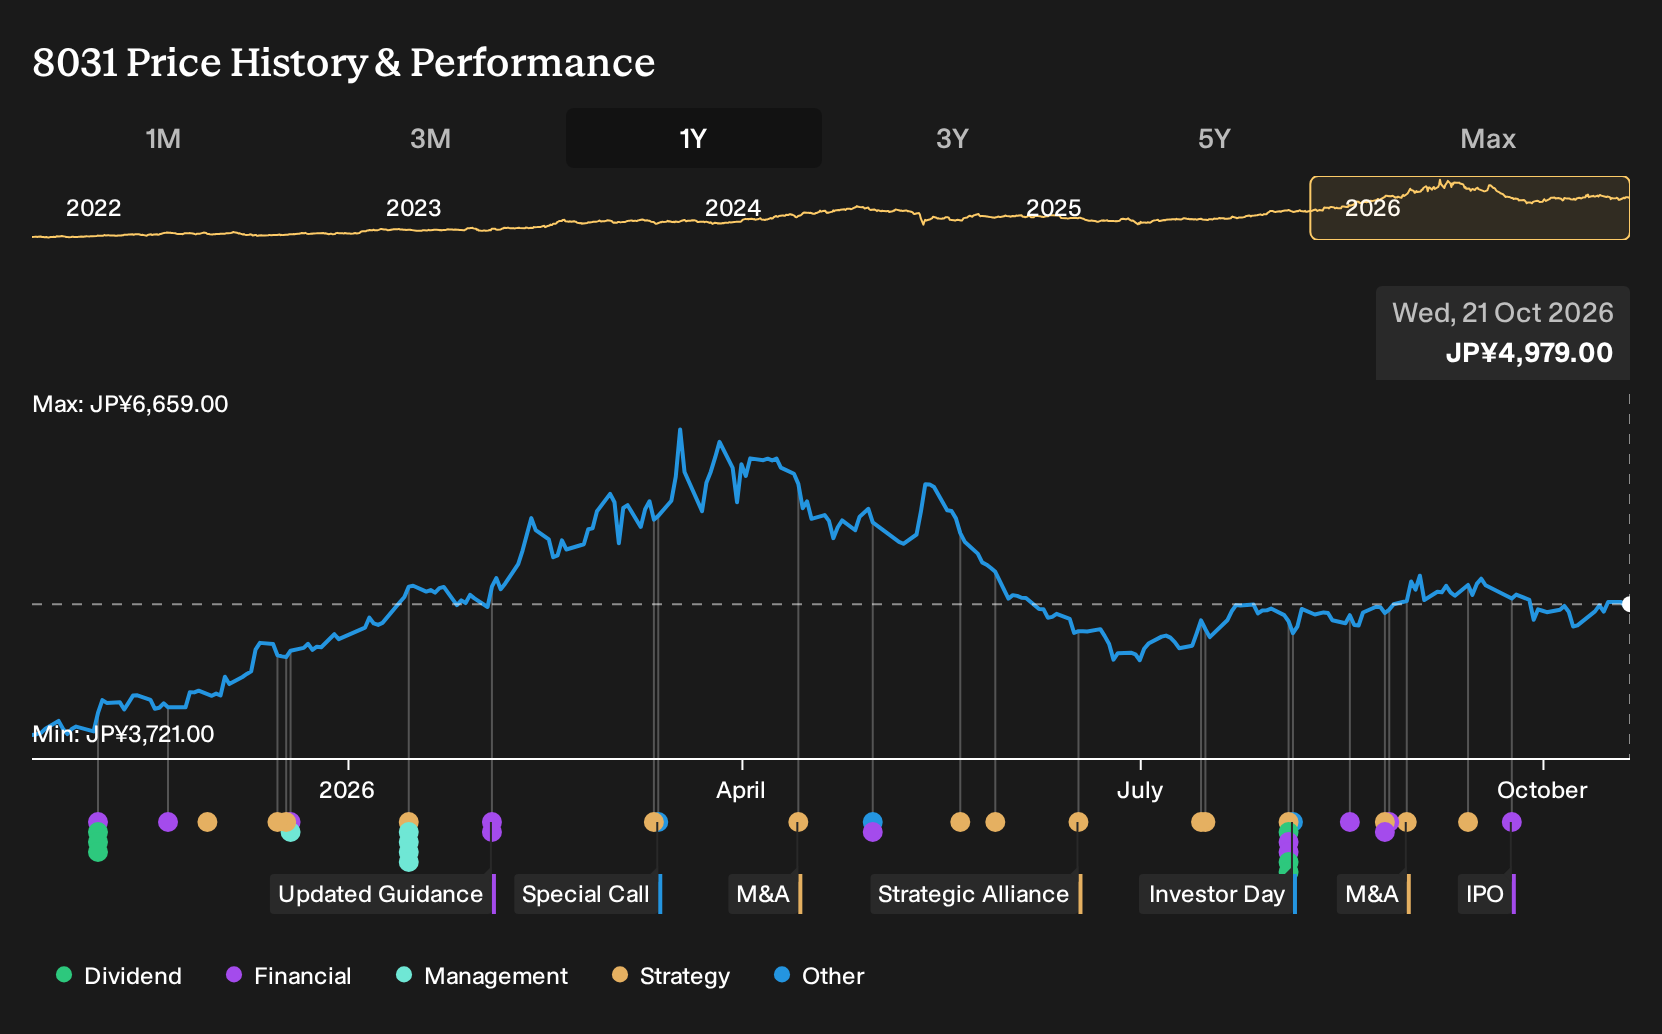
If Mitsui was on your watchlist instead of in your portfolio, the past year may feel like a missed shot. Holding Mitsui over the past year would have returned 36.7%, including dividends. That outcome invites a tougher question. Back on 21 October 2025, when bullish and bearish analysts were split on fossil fuel exposure versus energy transition upside, what business assumption about its shift toward decarbonization and asset recycling could have helped you recognise the potential before the move happened?
If the move has made Mitsui harder to judge, start where the gap is still open and scan 13 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On Mitsui
The shares cost ¥3,715 at the start of the period, and Mitsui sat between two sharply different but credible stories about where its mix of fossil fuels and energy transition projects might lead.
Bullish investors pointed to a Fair Value of ¥4,700, a notional price built on assumptions, tied to heavier exposure to LNG, hydrogen, renewables and digital logistics, plus asset recycling that could free over ¥1t for higher margin projects.
The bearish narrative anchored on a Fair Value of ¥2,860 and focused on fossil fuel dependency, commodity price pressure, and the risk that expansion into new sectors and stricter ESG rules would raise complexity and squeeze profitability.
What The Evidence Around Mitsui Actually Tested
Mitsui spent the period signing energy transition deals, including a five year, roughly US$850m cobalt offtake agreement and a US solar project reaching operations in Texas, alongside a US$750m bond issue backing low carbon ammonia. Q1 2027 also showed higher revenue, profit and a net margin of 6.8% versus 5.8% a year earlier. The evidence leaned toward the optimistic case but did not remove fossil fuel or complexity risks.
The key takeaway is straightforward: when a story focuses on decarbonization and asset recycling, track hard numbers on net margin and capital raised for cleaner assets, and then test whether those projects are actually entering production.
What Mitsui's Price Now Asks You To Believe
Mitsui now trades at ¥4,979. The selected Narrative sets a Fair Value below that level and frames the gap as a question about how reliable cash generation really is once LNG linked cash flows normalise.
Buying at today’s price leans on confidence that cash from cleaner projects will stay near plan. The Narrative asks how that assumption copes with volatile resource cash flows and disciplined but demanding shareholder returns.
"While Mitsui is presenting disciplined capital allocation around MTMP2029 and committing over 50% of COCF to shareholder returns, the prior JPY 101.4 billion fall in Energy segment COCF linked to non recurring LNG dividends shows that if new projects do not generate steadier operating cash, the combination of high payout and volatile resource cash flows could strain reinvestment capacity and pressure future COCF sustainability."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Where Mitsui’s Theme Extends
Mitsui points you to decarbonization and cash from cleaner projects. One step away, the same shift creates a different choke point.
Low carbon fuels and renewables still need dependable electricity systems. Data centers, factories and grids only work if power stays stable.
Another energy specialist focuses on the equipment that keeps that flow steady. Gas turbines, grid hardware and related software support reliability over long periods.
As electricity demand tied to electrification and computing grows, that installed base shapes what stays online.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 37% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com