


- Transurban Group reported quarterly operating data for the September 2026 quarter, with average daily traffic of 2,576,000 vehicles, up 3.1% from 2,499,000 a year earlier.
- This higher vehicle throughput highlights how Transurban Group’s toll road portfolio is attracting steady user demand, which directly feeds into toll collection volumes and operational scale.
- We will examine how Transurban Group’s 3.1% uplift in average daily traffic affects the investment narrative built around long term volume resilience.
Transurban Group Investment Narrative Recap
To own Transurban Group, you need to believe its toll road portfolio can keep attracting steady volumes while managing rising costs, regulatory scrutiny and funding needs. The 3.1% uplift in average daily traffic to 2,576,000 vehicles supports the volume side of that thesis but does not, on its own, change the near term story.
The key short term swing factor remains how operating expenses, especially maintenance on assets moving into heavier work cycles, track against toll revenue. The main risk is that higher upkeep and interest costs reduce cash generation faster than traffic and pricing can offset them, particularly if regulatory reforms constrain toll increases.
With no other recent announcements disclosed, the September 2026 traffic update is the clearest operational data point to anchor the near term outlook for Transurban Group. It links directly to previous commentary that highlighted resilient volumes as a support for earnings and cash flow.
For catalysts, investors are likely to compare this 3.1% traffic uplift with the project pipeline and any upcoming openings or ramp ups. The stronger the utilisation on existing roads appears today, the more comfortable you can be that new capacity, once commissioned, has a realistic chance of contributing to volume based revenue rather than diluting returns.
Transurban Group's current analyst narrative points to A$4.3b in revenue and A$569.5m in earnings by 2029, based on an assumed 3.2% yearly revenue growth rate and an earnings increase of about A$203.5m from A$366.0m today.
Uncover why Transurban Group's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
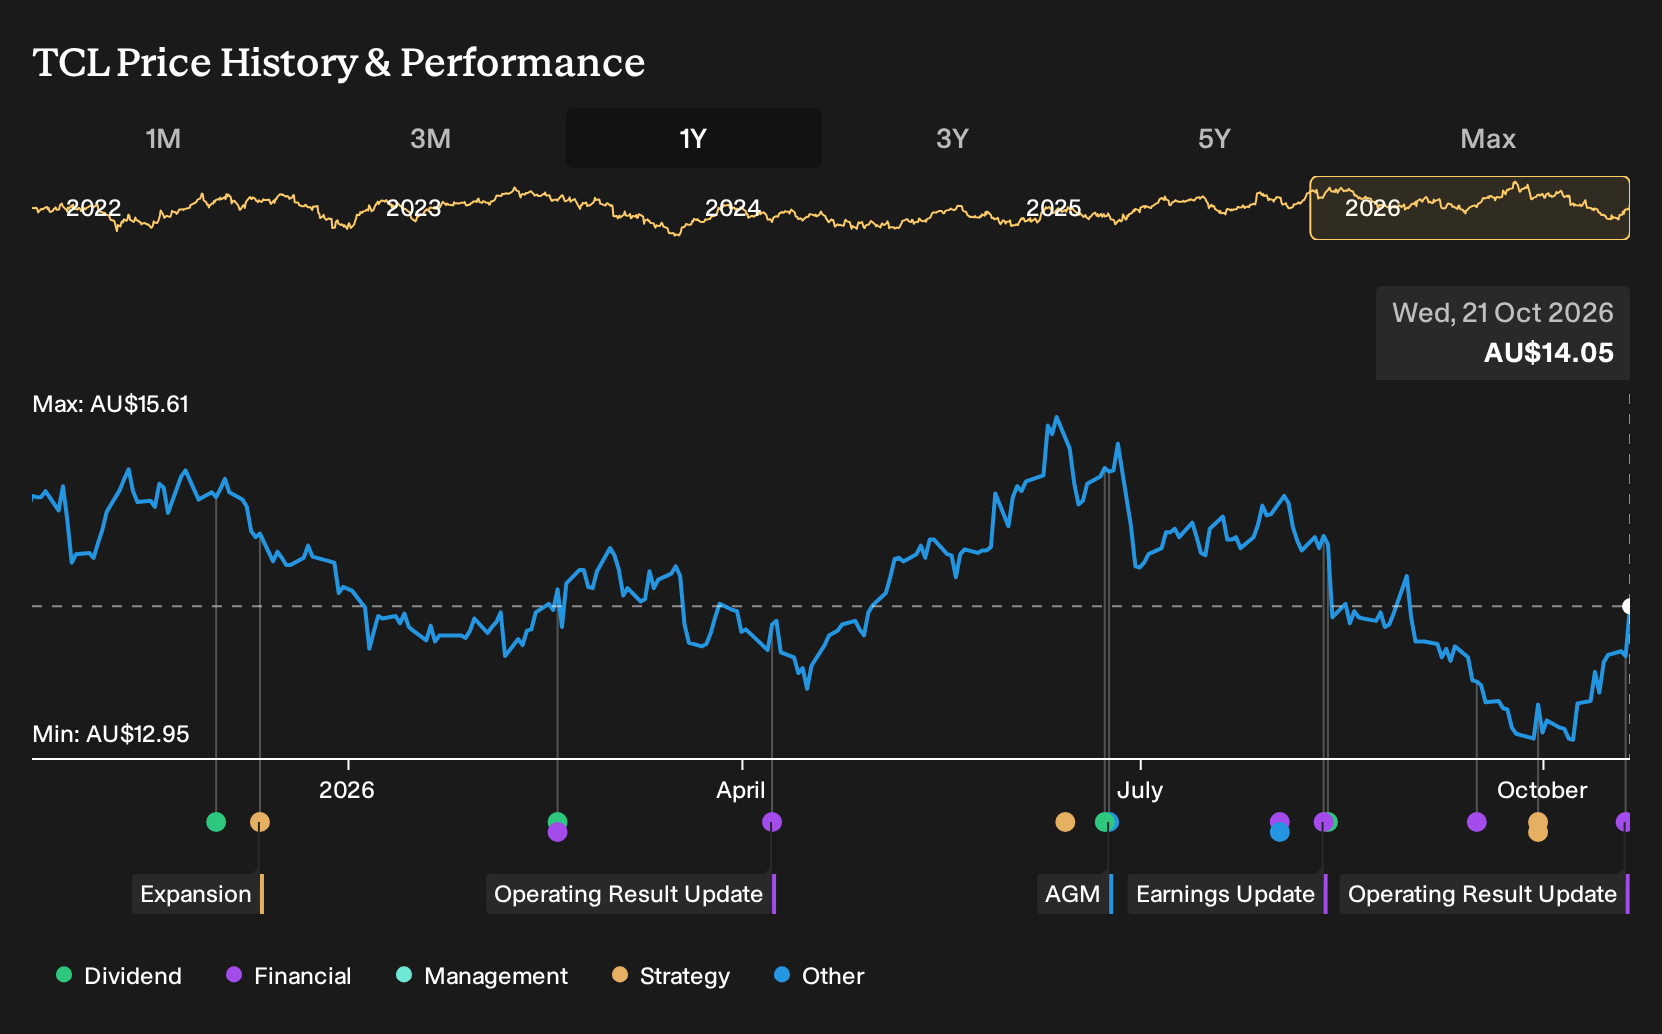
Three fair value estimates from the Simply Wall St Community cluster between A$13.68 and A$20.89, which shows how far apart private investors can be on Transurban Group. Since these views pre date the September traffic update, you should weigh them against looming maintenance, toll reform and interest cost risks that could reshape the story.
Explore 2 other Transurban Group fair value estimates, including one that suggests it could be worth just A$13.68.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Transurban Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Transurban Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Transurban Group's overall financial health at a glance.
Looking for more Transurban Group style investment ideas?
If the Transurban Group story has sharpened your focus on quality and risk, broaden the watchlist by scanning for other businesses that fit clear, disciplined criteria using the Simply Wall St Screener.
- For investors who want quality at a sensible entry point, start with companies flagged as having 4 high quality undervalued stocks based on their fundamentals.
- If capital preservation is front of mind, concentrate on a 6 resilient stocks with low risk scores that screens for resilience rather than excitement.
- When balance sheet strength is non negotiable, filter for a list of solid balance sheet and fundamentals (12 results) that surfaces financially robust businesses first.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com