


Scandi Standard (OM:SCST) just posted fresh Q3 2026 numbers, with sales of SEK 4,038 million and net income of SEK 131 million. The update puts recent share price strength under a clearer earnings lens.
Investors have been rewarding Scandi Standard, with a 7 day share price return of 14.21% and a 90 day share price return of 44.25%. The 1 year total shareholder return of 108.27% and roughly 3x gain over three years point to strong, sustained momentum.
Scan other momentum driven poultry and food producers against Scandi Standard's run with our curated 617 high quality undiscovered gems for ideas that might be earlier in their rerating journey.
Scandi Standard now trades after a sharp rerating, backed by higher recent earnings and strong multi year returns. Is this pricing a sturdier poultry franchise, or a burst of market enthusiasm that valuation needs to test next?
Most Popular Narrative: 21% Overvalued
The most followed valuation narrative for Scandi Standard points to a fair value of SEK151.75 against a last close of SEK183.20, so the recent share price strength sits above that anchor and puts the underlying assumptions under more pressure.
The current valuation may be pricing in an overly optimistic continuation of the shift from red meats to poultry, assuming sustained robust consumer demand for chicken amid global health and wellness priorities; this could lead to disappointment if consumer trends toward plant-based alternatives accelerate, resulting in slower revenue growth than expected.
The share price appears to factor in continued success in passing through higher production costs via price increases, despite ongoing volatility in input costs (notably feed), and assumes minimal margin pressure even though there is increasing regulatory focus and potential public pressure on carbon emissions and animal welfare, which could drive up costs and compress profit margins.
See why 3 investors see Scandi Standard as 21% overvalued.
Result: Fair Value of SEK151.75 (OVERVALUED)
Still, if consumer preferences move faster toward plant based proteins, or if new welfare rules lift costs, the current Scandi Standard valuation narrative could face a real stress test.
Find out about the key risks to this Scandi Standard narrative.
Another View: Scandi Standard Through A Cash Flow Lens
Price based metrics flag Scandi Standard as expensive, with a P/E of 28.5x compared with a fair ratio of 26.2x, peers at 15.5x and the European Food group on 15.2x. That is a rich premium, which raises the question of how much execution risk investors are really comfortable carrying.
See what the numbers say about this price — find out in our valuation breakdown.
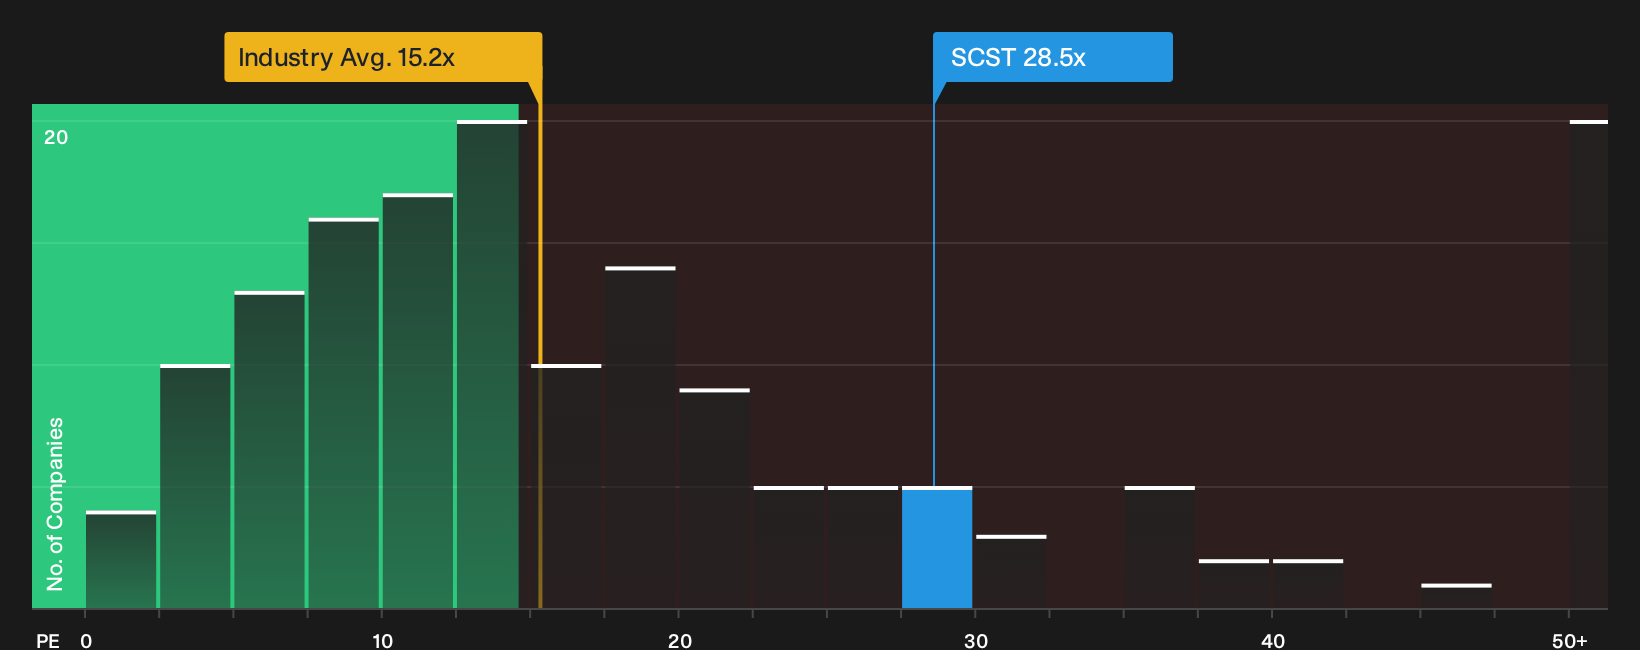
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Scandi Standard for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 190 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Scandi Standard is clearly mixed, with strong recent returns sitting alongside real questions about risk and durability. Act quickly to stress test that tension for yourself by weighing its 3 key rewards and 2 important warning signs via the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Scandi Standard?
If Scandi Standard has sharpened your focus on valuation and momentum, you could broaden your watchlist with a few targeted screens that highlight different types of opportunities.
- Look for quality at a discount by scanning companies that appear attractively priced on fundamentals with the 190 high quality undervalued stocks.
- Build a steadier income stream by examining businesses with robust payouts using the 218 dividend fortresses.
- Manage portfolio risk by filtering for companies that rate well on resilience and financial risk through the 229 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com