


AI has moved from hype to hard infrastructure, as shown by South Korea’s record chip-driven exports linked to the current AI boom. Hardware, cloud and software suppliers behind that surge are not all priced as if this continues. That gap is where opportunity lives. This article highlights three undervalued AI stocks that sit at the intersection of chips, data and software so you can decide which, if any, deserve a closer look.
The three stocks covered below are just a sample, and the full screen surfaced 45 more listed AI players with equally compelling stories across chips, cloud, data infrastructure and software that this article does not touch.
Head straight into the Undervalued Artificial Intelligence/ AI Stocks screener to identify, filter and analyze the highest conviction ways to get direct exposure to the ChatGPT and broader AI build out.
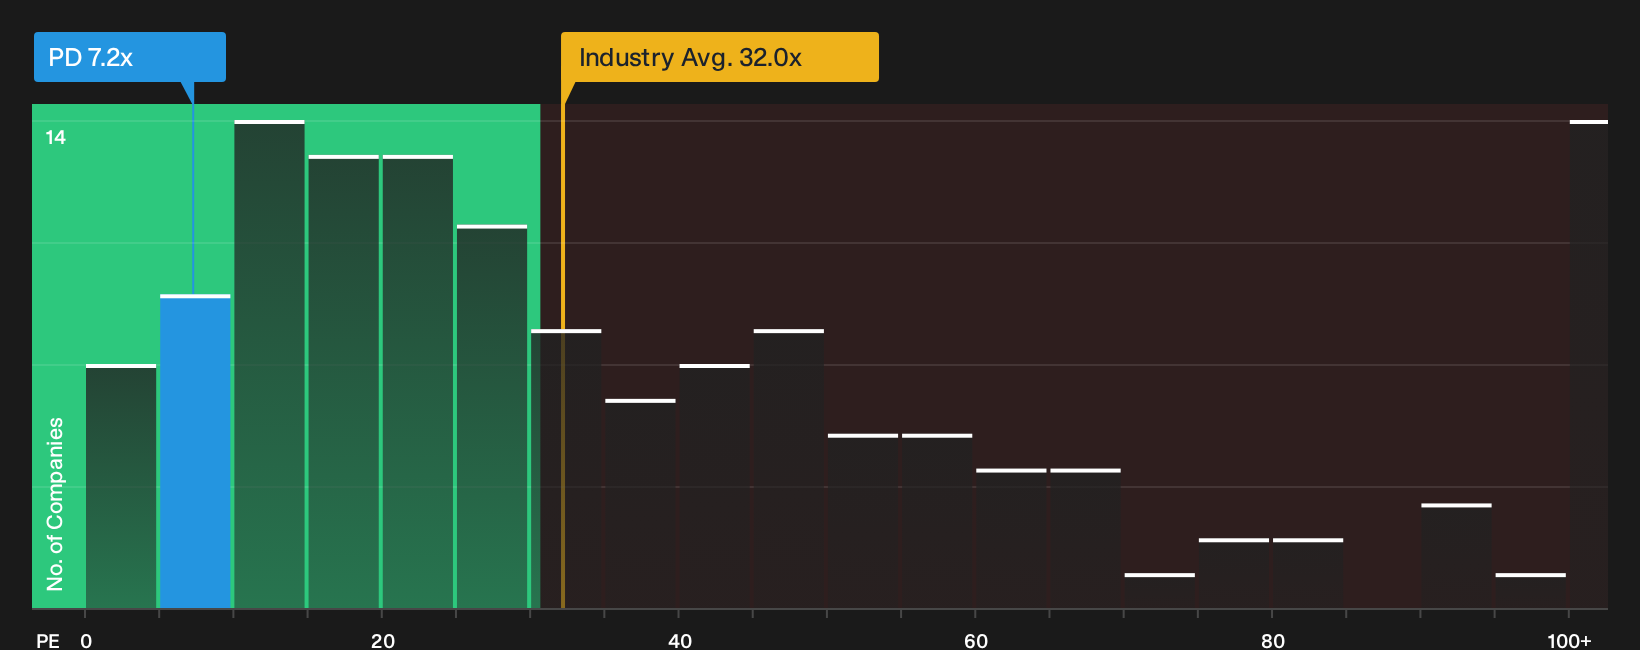
PagerDuty (PD)
Overview: PagerDuty runs a cloud-based operations platform that uses AIOps and generative AI to detect, manage, and automate responses to digital incidents.
Operations: PagerDuty generates about $494.7 million from Software & Programming, with roughly $350.3 million from the United States and $144.5 million internationally.
Market Cap: US$1.32b
PagerDuty matters for this AI-focused screen because its AIOps and generative tools turn raw operational noise into automated, real-time incident response for large digital businesses.
"The accelerating adoption of AI-powered automation across IT operations is likely to commoditize incident response and real-time operations management, putting downward pressure on PagerDuty's pricing power and shrinking its core addressable market, which would cause future revenue growth to slow dramatically."
What happens to PagerDuty’s long-term appeal if a single pressure point quietly reshapes how much customers are willing to pay for that automation?
That pricing pressure is only half the story, and the full narrative for PagerDuty shows how PagerDuty could still harness AI automation to accelerate value creation beyond headline fears.
Adobe (ADBE)
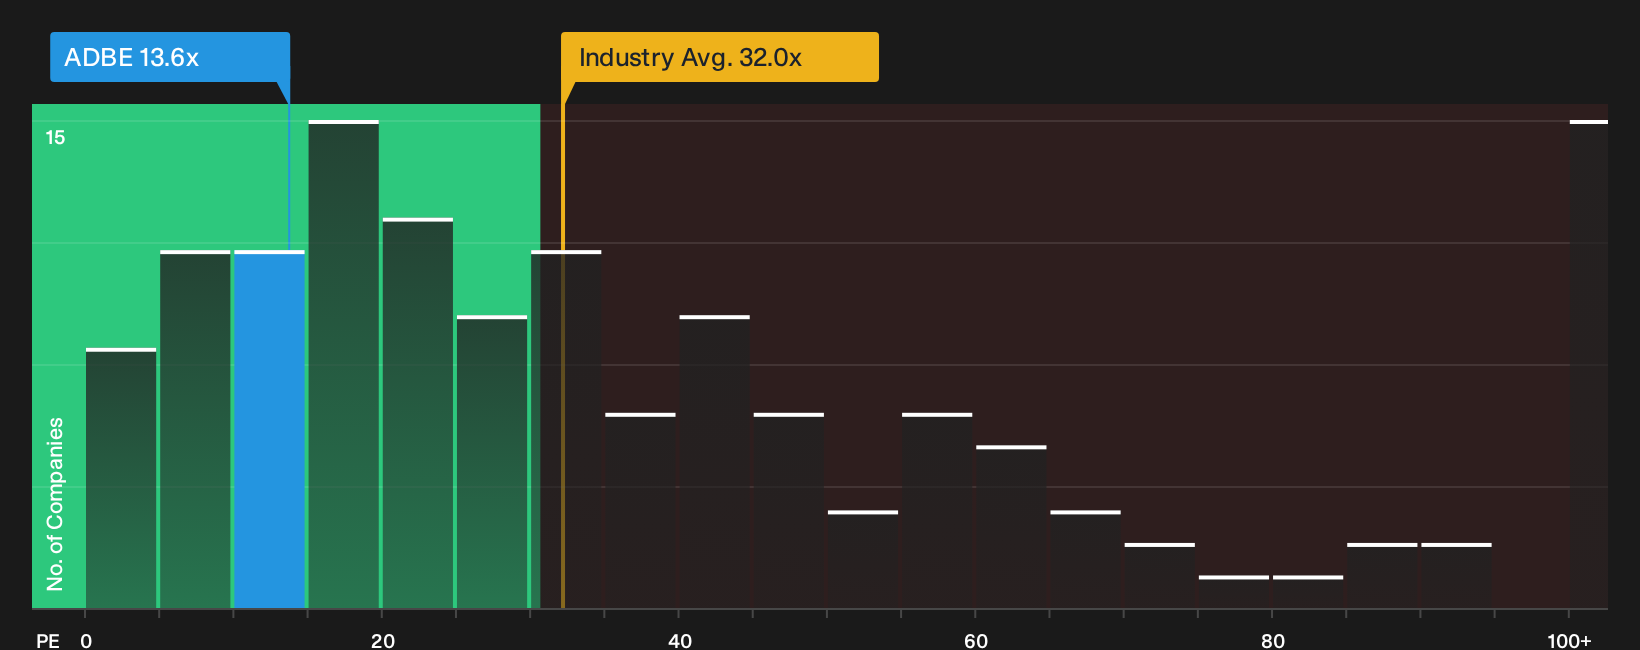
Overview: Adobe is a global software provider whose Creative Cloud and Experience Cloud tools use generative AI to help professionals design, publish, and manage content for marketing, media, and enterprise workflows.
Operations: Adobe records about $15.3 billion from segment adjustments, with key geographic exposure in EMEA at $7.1 billion and APAC at $3.6 billion.
Market Cap: US$99.9b
Adobe matters to this AI-focused screen because Firefly and other embedded tools link generative models directly to paid creative and marketing workflows, turning everyday content production into a recurring AI revenue engine.
"As professionals integrate AI into their daily workflows, their credit usage increases. When they hit the limits of their current plan, the path of least resistance is to upgrade to a higher Creative Cloud tier or purchase a credit pack, thereby driving Average Revenue Per User (ARPU) expansion."
What happens to Adobe’s margin profile if one quiet shift in how enterprises create brand-safe content tilts even more work into these AI tiers?
That shift in creative workflows is only the starting point, and the full narrative for Adobe shows how Adobe could convert AI credit demand into an accelerating, higher quality revenue mix.
Baidu (BIDU)
Overview: Baidu is a Beijing-based technology group that runs China’s leading search, ERNIE Bot AI assistant, AI cloud services, and autonomous driving platform.
Operations: Baidu generates about CN¥102b from Baidu General Business and CN¥26b from iQIYI, with essentially all CN¥127b earned in the PRC.
Market Cap: US$27.5b
Baidu matters for this AI-focused screen because ERNIE Bot and its AI cloud stack put large language models, custom chips, and autonomous driving into real-world products, not just research labs.
"The rapid rise in digitalization and urbanization across China is fueling increased engagement with online platforms and services. This is creating a larger addressable market for Baidu's AI-powered products, which supports potential long term growth in search, cloud and new digital services that can influence revenue and earnings."
The real swing factor for Baidu is whether one emerging profit engine quietly grows fast enough to reshape group margins and investor expectations.
If that engine is what you care about, the full narrative for Baidu describes how Baidu could turn fresh AI demand into accelerating, less correlated cash generation.

Curious About The Next Set Of Alternatives
Fresh opportunities do not wait. Breakout momentum can get caught quickly once the crowd arrives. Scan under the radar for now, while it matters, and act now.
- Spot income workhorses before yields get chased down by late money using the curated list of 7 dividend fortresses.
- Target future-facing materials players positioned for electrification trends through a focused group of 16 top copper producer stocks.
- Track the companies wiring tomorrow’s AI buildout and grid upgrades using a pre-filtered basket of 42 power grid technology and infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com