


We can readily understand why investors are attracted to unprofitable companies. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. Nonetheless, only a fool would ignore the risk that a loss making company burns through its cash too quickly.
So, the natural question for Saudi Industrial Export (TADAWUL:4140) shareholders is whether they should be concerned by its rate of cash burn. In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
Does Saudi Industrial Export Have A Long Cash Runway?
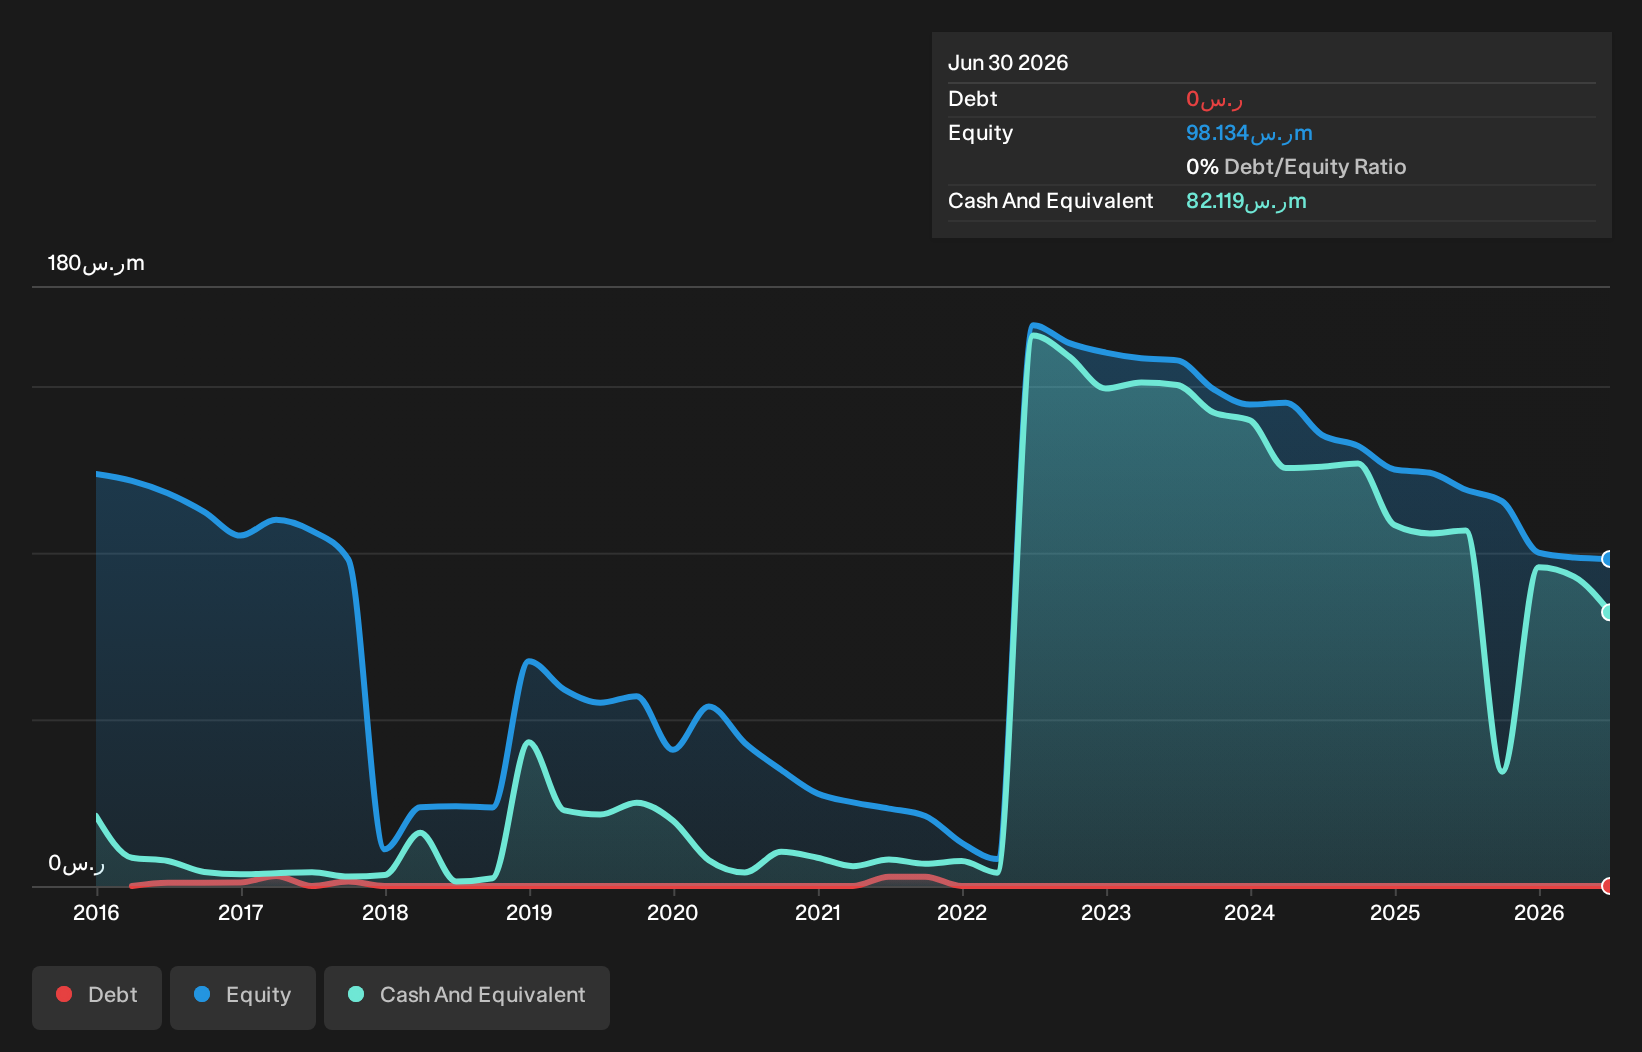
A company's cash runway is the amount of time it would take to burn through its cash reserves at its current cash burn rate. As at June 2026, Saudi Industrial Export had cash of ر.س82m and no debt. In the last year, its cash burn was ر.س10m. So it had a cash runway of about 7.9 years from June 2026. While this is only one measure of its cash burn situation, it certainly gives us the impression that holders have nothing to worry about. The image below shows how its cash balance has been changing over the last few years.
View our latest analysis for Saudi Industrial Export
How Is Saudi Industrial Export's Cash Burn Changing Over Time?
Because Saudi Industrial Export isn't currently generating revenue, we consider it an early-stage business. So while we can't look to sales to understand growth, we can look at how the cash burn is changing to understand how expenditure is trending over time. With cash burn dropping by 9.9% it seems management feel the company is spending enough to advance its business plans at an appropriate pace. Saudi Industrial Export makes us a little nervous due to its lack of substantial operating revenue. We prefer most of the stocks on this list of stocks that analysts expect to grow.
Can Saudi Industrial Export Raise More Cash Easily?
While Saudi Industrial Export is showing a solid reduction in its cash burn, it's still worth considering how easily it could raise more cash, even just to fuel faster growth. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Saudi Industrial Export's cash burn of ر.س10m is about 2.8% of its ر.س373m market capitalisation. So it could almost certainly just borrow a little to fund another year's growth, or else easily raise the cash by issuing a few shares.
How Risky Is Saudi Industrial Export's Cash Burn Situation?
It may already be apparent to you that we're relatively comfortable with the way Saudi Industrial Export is burning through its cash. For example, we think its cash runway suggests that the company is on a good path. On this analysis its cash burn reduction was its weakest feature, but we are not concerned about it. Taking all the factors in this report into account, we're not at all worried about its cash burn, as the business appears well capitalized to spend as needs be. On another note, we conducted an in-depth investigation of the company, and identified 3 warning signs for Saudi Industrial Export (2 shouldn't be ignored!) that you should be aware of before investing here.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.