


Why Wheaton Precious Metals Is Back On Investors’ Radar
Wheaton Precious Metals (TSX:WPM) is drawing fresh attention after reporting second quarter 2026 adjusted earnings of $1.19 per share, with both profit and revenue growth outpacing analyst expectations.
The CA$185.58 share price has pulled back over the past month, with a 30 day share price return of 10.5% in the red. However, the 90 day share price return of 19.8% and 1 year total shareholder return of 37.4% keep Wheaton Precious Metals firmly in longer term momentum territory.
Scan for other precious metals stocks showing strong earnings momentum and price resets by checking the 35 elite gold producer stocks alongside Wheaton Precious Metals after this quarter’s beat and recent pullback.
The strong second quarter beat, the CA$185.58 share price, and analyst fair value estimates that sit meaningfully higher create a wide gap. Is Wheaton Precious Metals already stretched, or still trading below its underlying worth?
Most Popular Narrative: 42% Undervalued
On the most followed view, Wheaton Precious Metals carries a narrative fair value of CA$320.42 against a CA$185.58 last close. This frames the current gap through the lens of larger streaming deals and disciplined underwriting rather than short term price swings.
Scaling into multi billion dollar streams with large diversified miners, as shown by the recent 4.3b Antamina agreement and the expectation of at least one 1b plus transaction per year over the next 5 to 10 years, can shift Wheaton Precious Metals from a portfolio of mid sized deals to a handful of very large contributors that influence revenue concentration, earnings power and valuation multiples.
See why 19 investors see Wheaton Precious Metals as 42% undervalued.
Result: Fair Value of CA$320.42 (UNDERVALUED)
Still, Wheaton Precious Metals faces two clear swing factors: ongoing global minimum tax payments that redirect cash flows and intense bidding pressure across more than 30 streaming rivals.
Find out about the key risks to this Wheaton Precious Metals narrative.
Another View On Wheaton Precious Metals’ Valuation
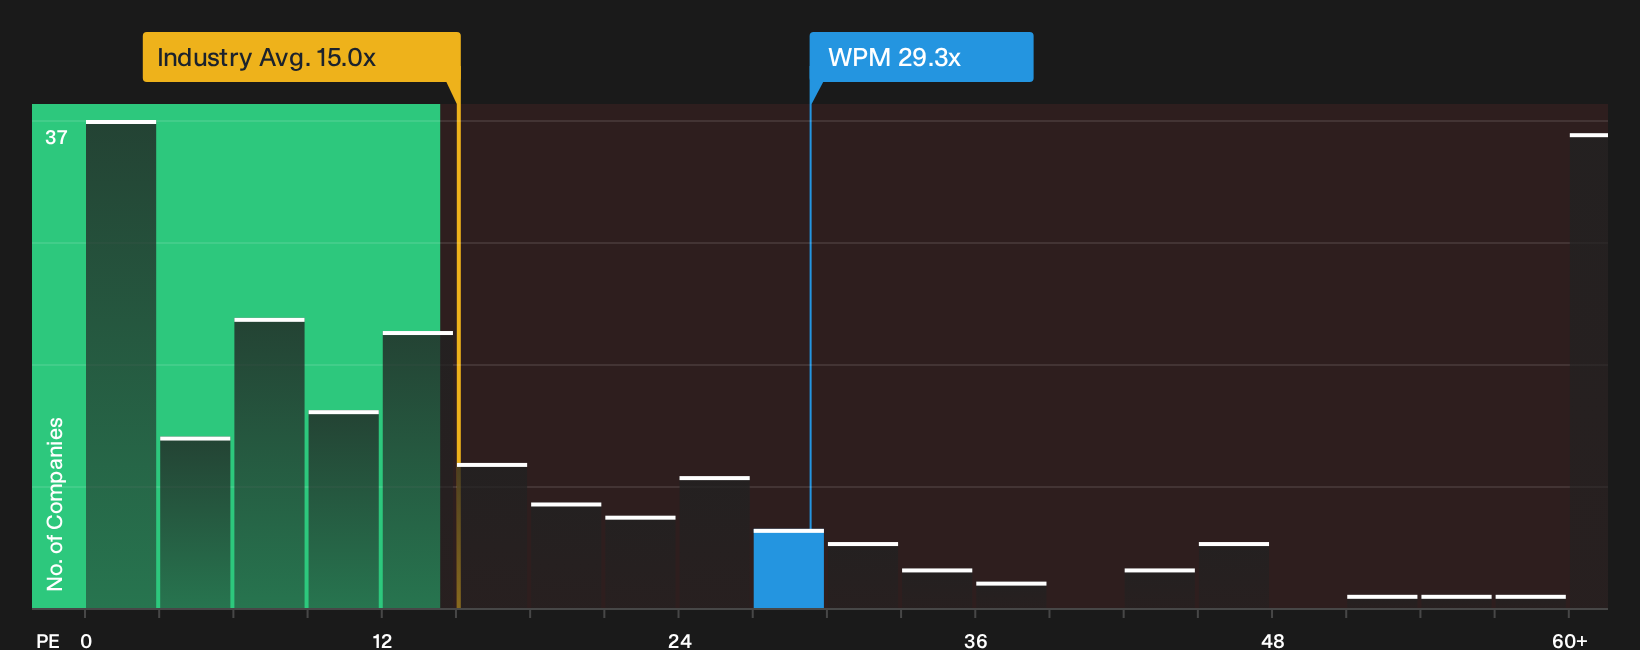
The bullish narrative leans heavily on future earnings power, yet today’s pricing tells a different story. Wheaton Precious Metals trades on a P/E of 29.3x, far above the Canadian Metals and Mining industry at 15x and the fair ratio of 17.4x. This points to richer expectations baked into the share price.
The gap between 29.3x today and a fair ratio of 17.4x leaves less room for error if analyst optimism or deal flow cools, especially when peers average 16.9x. Investors may wish to consider whether this premium is one that long term holders feel comfortable paying if sentiment or growth assumptions reset.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and pressure around Wheaton Precious Metals feels finely balanced, consider acting promptly: review the underlying data, stress test it against your own risk appetite, and then weigh up the 4 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Wheaton Precious Metals?
If Wheaton Precious Metals has sharpened your focus on quality, use that momentum to scan for other opportunities that match your risk, income, and growth goals.
- Target resilience by reviewing the 8 resilient stocks with low risk scores that aim to keep setbacks contained when markets turn rough.
- Hunt for value by checking the 4 high quality undervalued stocks that pair solid fundamentals with prices that still look reasonable.
- Stack potential income by scanning the 3 dividend fortresses that focus on higher yields with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com