


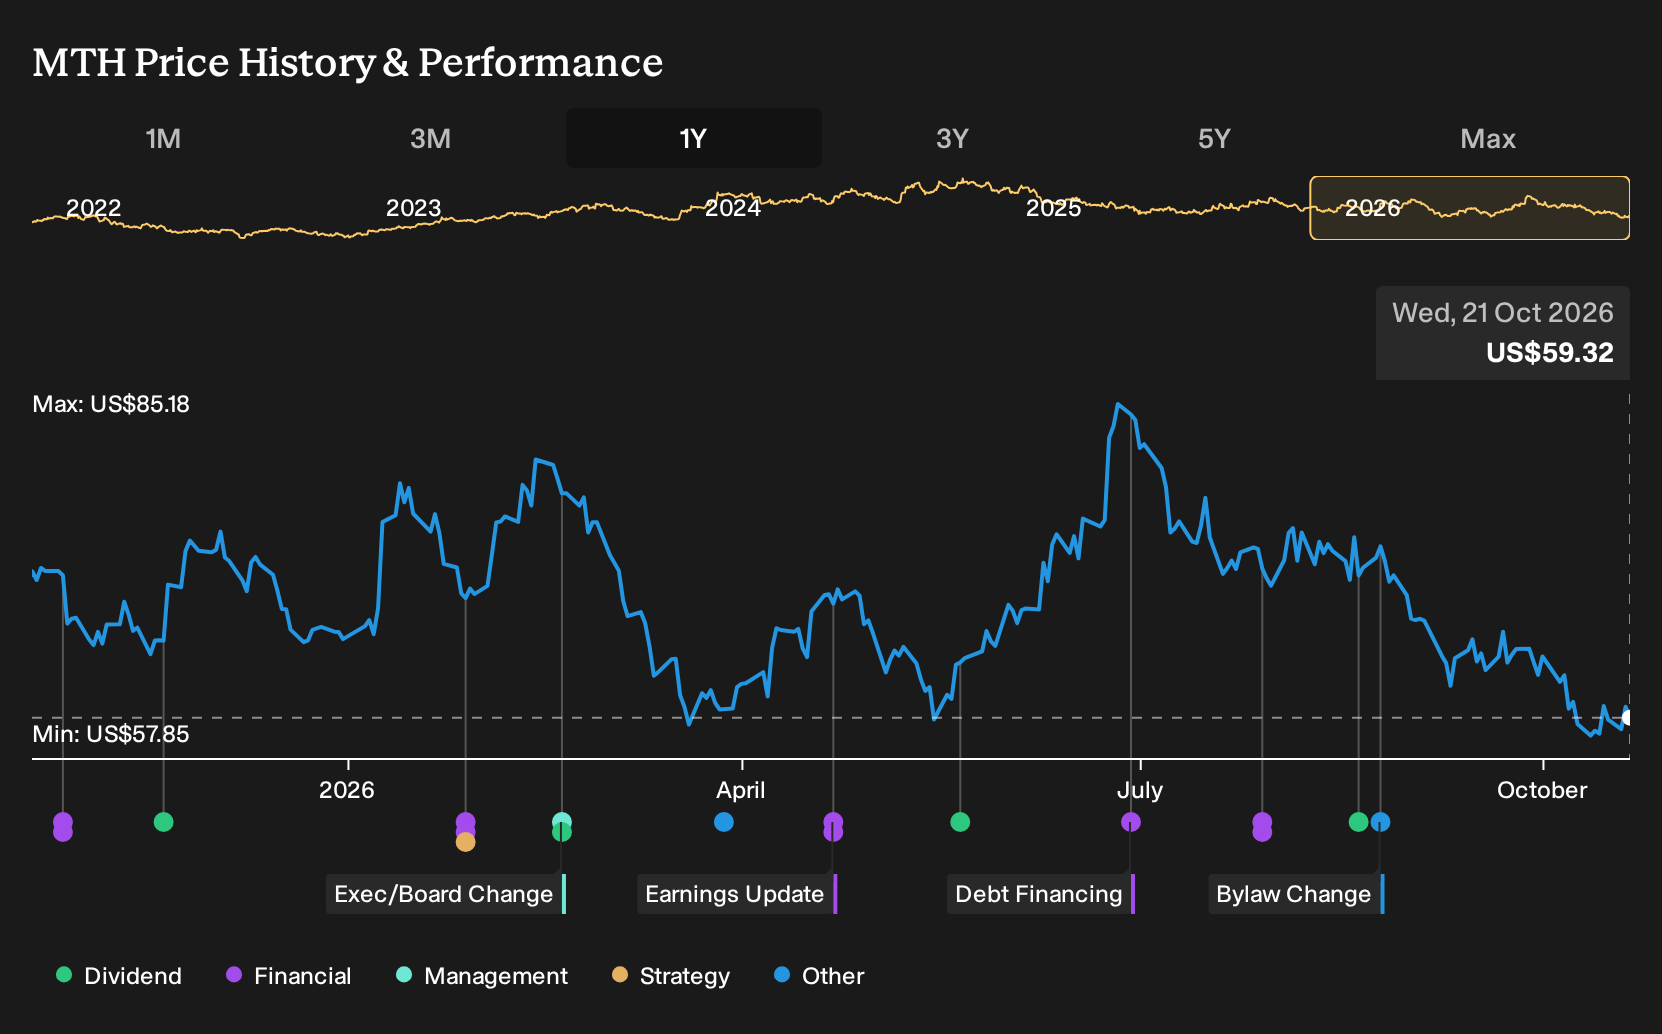
- Meritage Homes is expected to report lower revenue and a year over year decline in earnings for the September 2026 quarter, reflecting pressure on its homebuilding operations.
- The combination of reduced earnings expectations and weaker near term demand assumptions highlights how Meritage Homes' cost structure and pricing power are being tested.
- The focus now turns to how this weaker earnings setup could reshape Meritage Homes' investment narrative and its longer term margin story.
Scan how Meritage Homes' setup compares with other housing-related plays by sizing up our hand-picked list of solid balance sheet and fundamentals (25 results) for ideas with potentially sturdier financial footing.
Meritage Homes Investment Narrative Recap
To own Meritage Homes, you need to believe its focus on entry level and first move up buyers, quick close spec inventory and cost discipline can offset affordability pressure. The expected earnings and revenue decline for the September 2026 quarter raises questions about how durable that thesis looks in a slower order environment.
The near term catalyst is whether Meritage can hold gross margins while still using incentives to keep volumes moving. The biggest risk is that mortgage affordability stays tight, forcing deeper discounts that further pressure the current 6.1% net margin and weigh on cash generation. This update reinforces that risk but does not fundamentally change it.
There have been no fresh operational announcements disclosed alongside this earnings preview, so the most relevant reference point is Meritage Homes’ existing cost and capital framework. Management previously outlined structural cost reductions, including direct construction costs per square foot that were 6% lower year over year, and a pipeline of lower basis land extending from late 2027.
That setup matters for this weaker earnings backdrop because it gives Meritage some levers to defend profitability if pricing remains under pressure. The combination of moderated land spending that still supports 4 to 5 years of lot supply and ongoing share repurchases means execution now hinges on converting those cost and land advantages into steadier margins as near term demand softens.
Meritage Homes' analyst narrative points to US$6.2b in revenue and US$422.1 million in earnings by 2029. That hinges on revenue expanding at 4.7% per year and an earnings increase of about US$92.8 million from US$329.3 million today.
Uncover why Meritage Homes' fair value indicates a 27% potential upside to its current price that could narrow quickly as expectations reset.
Exploring Other Perspectives
One alternate view on Meritage Homes focuses heavily on demand risk. The most bearish analysts were penciling in about US$6.0b of revenue and US$366.8 million of earnings by 2029, well below consensus. They see slower order trends and a flat 6.1% margin as a ceiling rather than a base case. This earnings preview could push those narratives even further apart, so treat it as a prompt to compare several viewpoints before you decide how to interpret the news.
Explore 3 other Meritage Homes fair value estimates, including one that suggests it could be worth just $59.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Meritage Homes research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Meritage Homes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Meritage Homes' overall financial health at a glance.
Looking for more Meritage Homes style investment ideas?
If this Meritage Homes update has you reassessing your watchlist, it can help to line it up against other companies with clear financial profiles and different risk setups.
- If you want potential upside but still care about balance sheet strength, start with a list of solid balance sheet and fundamentals (25 results) that surfaces businesses with cleaner finances and room to manoeuvre.
- If valuation discipline is your priority, compare Meritage Homes with a 33 high quality undervalued stocks that highlights companies where fundamentals and pricing look more aligned.
- If you prefer income support while you wait for a thesis to play out, scan a 7 dividend fortresses that focuses on higher yield opportunities with sturdier payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com