


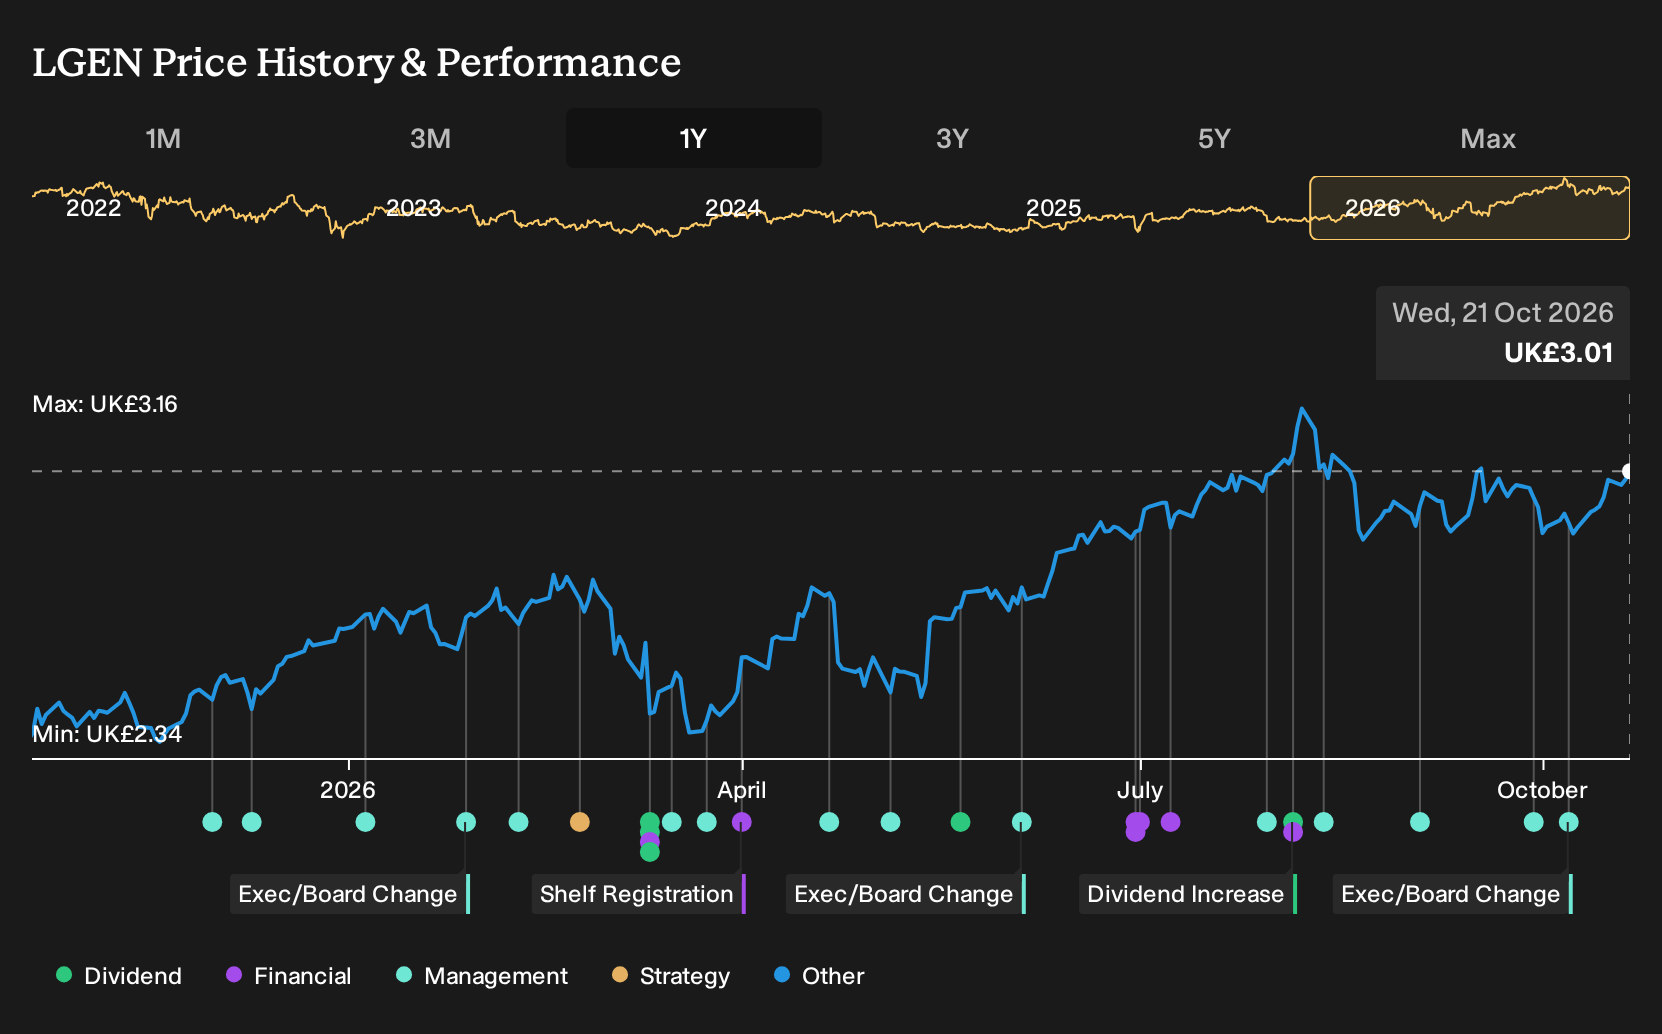
Legal & General Group spent the past year talking about becoming leaner, returning over £5b to investors, and even cutting around 1,000 jobs, yet the share price told its own story. Holding Legal & General Group over the past year would have returned 34.8%, including dividends. If you had put money in on 21 October 2025, knowing only the mixed demographic debates and contested valuation targets, what exactly in the record would have justified taking that risk?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Legal & General Group harder to judge, start where the gap is still open and scan 6 high quality undervalued stocks.
The Two Legal & General Stories Investors Had To Weigh
The shares cost £2.36 at the start of the period, and anyone looking at Legal & General Group had to decide which storyline seemed more convincing.
The bullish narrative priced fair value at £2.62, or 11% above the start price. It leaned on ageing populations and pension system growth to support demand for retirement solutions, alongside digital transformation improving the mix and margins.
The bearish view pointed to a £2.15 fair value, or 9% below the start price. It focused on slowing demographic growth plus fintech competition eroding pricing power and profitability.
What The Results Changed For The Legal & General Group Story
The AGM pledge to return over £5b and simplify Legal & General Group supported the optimistic view that management would prioritise capital returns and a leaner structure. Reported figures added weight. Revenue moved from £5,429m in H1 2025 to £6,260m in H1 2026, net income rose from £259m to £447m, and net margin widened from 4.8% to 7.1%. The planned 1,000 job cuts gave the cautious camp fresh cost and execution risks, so the evidence cut both ways.
The key lesson is simple. When a story depends on improved profitability, focus on reported net margin and absolute earnings and then test any cost cutting or capital return plans against those numbers over time.
What Legal & General's Price Already Assumes
Legal & General Group now trades at £3.01, after a 34.8% gain over the past year from a £2.36 starting point. The selected Narrative places its Fair Value below that level, framing today’s quote as already baking in a lot of execution success.
The focus shifts to whether fee based, capital light areas like asset management and workplace pensions can support that share price. A buyer today has to judge if those businesses can scale profitably while restructuring, cost control and asset optimization all land as planned.
"The main thing that has to go right is that fee based, capital light businesses such as asset management and workplace pensions continue to scale profitably while cost/income ratios improve. The current valuation implies that Legal & General Group shares already price in successful delivery of higher fee related earnings, ongoing asset optimization profits of more than £400m per year and continued large capital returns to shareholders."
The price and this Narrative do not agree. → Uncover what this Narrative says Legal & General Group is actually worth
Legal & General and the Power Behind It
Legal & General is closely tied to where long term capital is deployed. Retirement money often prefers dependable cash flows in tangible real assets.
Electricity demand from AI infrastructure is accelerating very large power projects. Those data centers still need reliable generation, supported by stronger transmission grids.
One industrial specialist provides turbines, grid hardware and software that help keep electricity flowing. Selling equipment can simply open the door to long service work.
Contracts to maintain and upgrade these assets may last for many years. If that requirement keeps expanding, your portfolio research might reach beyond financial stocks.
One Narrative has put that dependency into a written case. → See the power-grid company one Narrative values 37% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com