


Husqvarna just printed a bruising Q3 2026, and the share price told you that before you saw a single line of the report. The stock closed at SEK31.5 on 21 October, capping a slide of roughly 10% over the past week and about 14% over three months, as investors braced for weak seasonal trading.
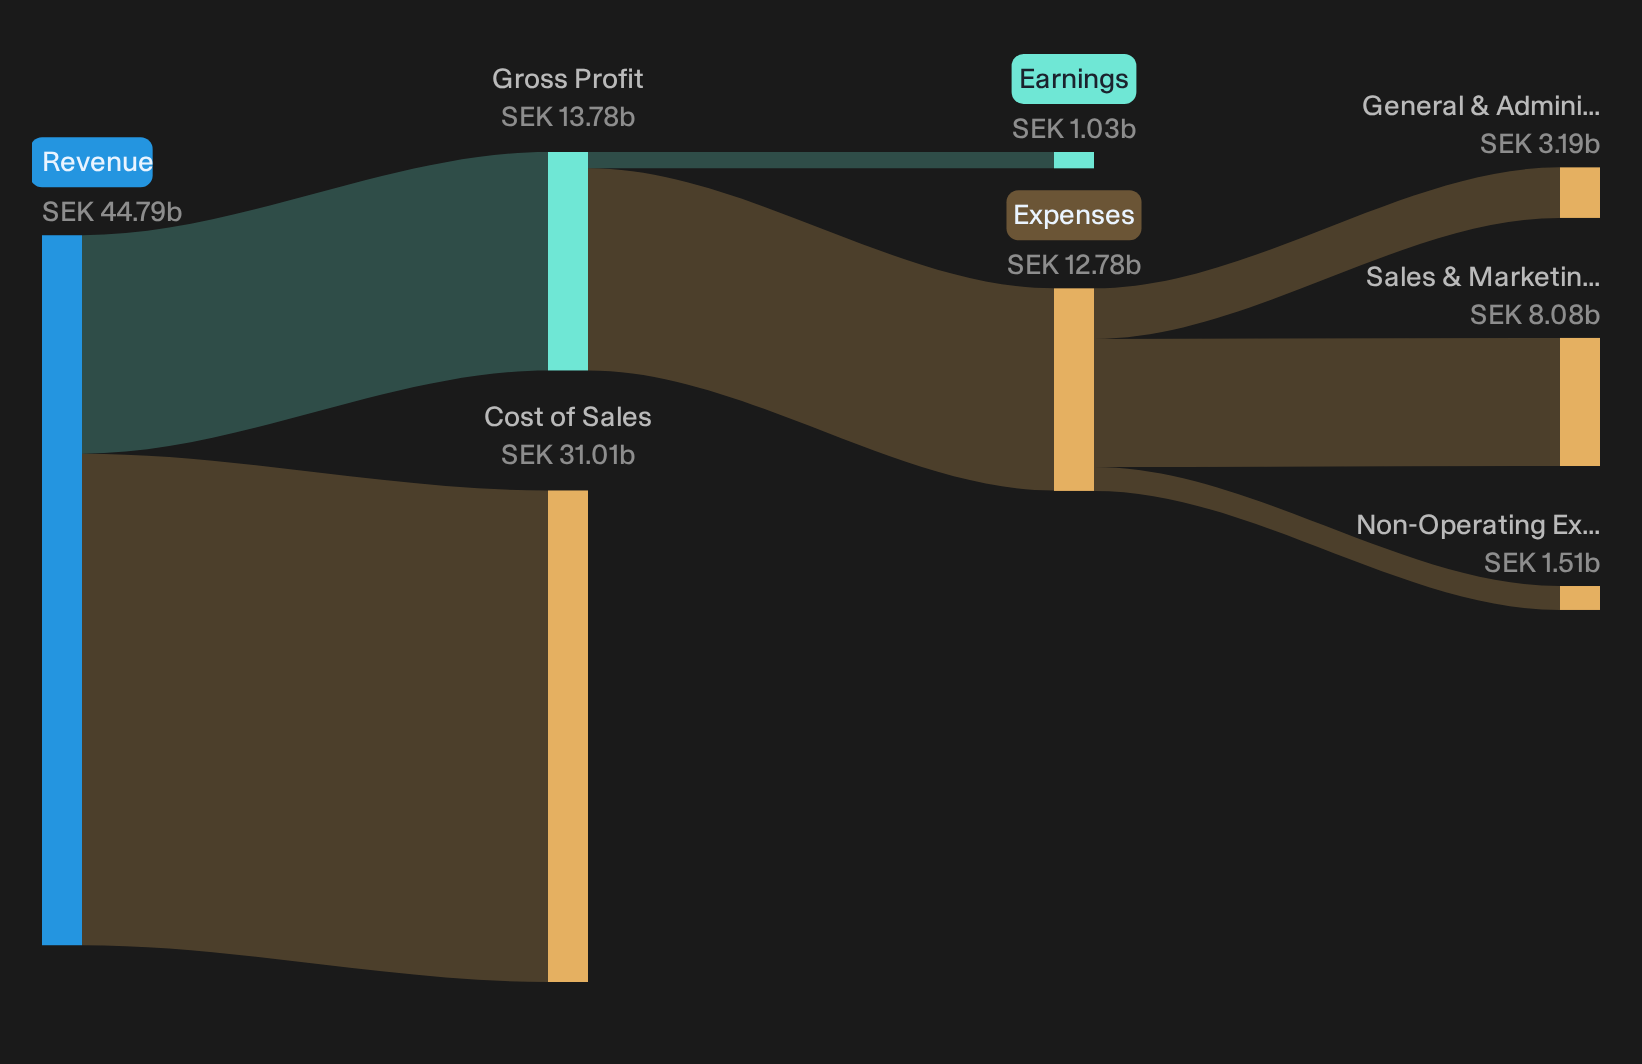
The headline did not calm nerves. Q3 delivered a net income loss of SEK403m on revenue of SEK9,012m, flipping the group into negative basic earnings per share of SEK0.70. Short term sentiment is fixated on that profit squeeze, and the question now is whether the selloff is driven by cold logic or by emotion running ahead of the numbers.
Concerned that Husqvarna has swung to a quarterly loss yet still want exposure to quality industrials with stronger profit profiles? You can benchmark this result against our list of solid balance sheet and fundamentals stocks (203 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): SEK9,012m vs. SEK9,204m (decline of 2.1%)
- Net Income/Loss (Q3 2026 vs. Q3 2025): loss of SEK403m vs. loss of SEK10m (loss widened significantly)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of SEK0.70 per share vs. loss of SEK0.02 per share (loss per share increased sharply)
- Trailing 12-Month Net Income (Q3 2026 TTM vs. Q3 2025 TTM): SEK1,030m vs. SEK1,423m (decline of 27.6%)
Tired of wading through dense earnings reports and raw figures on Husqvarna? See the full visual breakdown of Husqvarna's recent results, including an at-a-glance view of its valuation picture in the company report for Husqvarna.
Husqvarna’s growth engines vs profit reality
The bullish story focuses on robotics, electrification and better earnings quality over time.
"Leadership in robotics and sustainable equipment, supported by innovation, is driving rapid market share gains and recurring revenue opportunities in both professional and consumer segments."
Q3 indicates that leadership alone is not yet translating into resilient profit. Group organic sales fell 5%, robotics volumes were pressured at lower price points and Husqvarna Forest & Garden declined 10% organically. Management continued to invest in professional robotics and Gardena watering gained share, yet the quarter ended in a SEK403m loss and weaker TTM net income of SEK1,030m.
Husqvarna margins under pressure and reset risk
The bear case highlights the risk that competition, weak demand and cost pressure could overwhelm the reset.
"Intensifying competition from low-cost Asian manufacturers, especially in the entry and mid-range robotics segments, is contributing to aggressive price pressure, resulting in price reductions and negative price impacts..."
Recent figures are consistent with that concern. Management cited competitive pressure in lower priced robotics, organic decline in robotics and wheeled mowers, and margin drag from underabsorption as production was cut to reduce inventory. Cost inflation of roughly SEK900m to SEK1,000m for 2026 and tariff and FX headwinds weigh further. Analysts have already cut earnings for 2026 to 2028, and Q3’s widened loss underscores those margin concerns.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt For Mispriced Earnings Power
Husqvarna’s weak quarter shows how quickly sentiment can swing when profits slip. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 40% below our estimate - uses an alliance to share platforms, widen its model range, and expand exports through a multi-brand dealer network.
- Company 2 - 25% below our estimate - expands complex generics and ex U.S. products as rising operating cash flow supports filings and launches funded internally.
- Company 3 - 21% below our estimate - shifts capacity toward AI focused DRAM while a new fab and advanced nodes support customized memory products for data centre customers.
Three companies from the same screener. Open the full list of 190 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com