


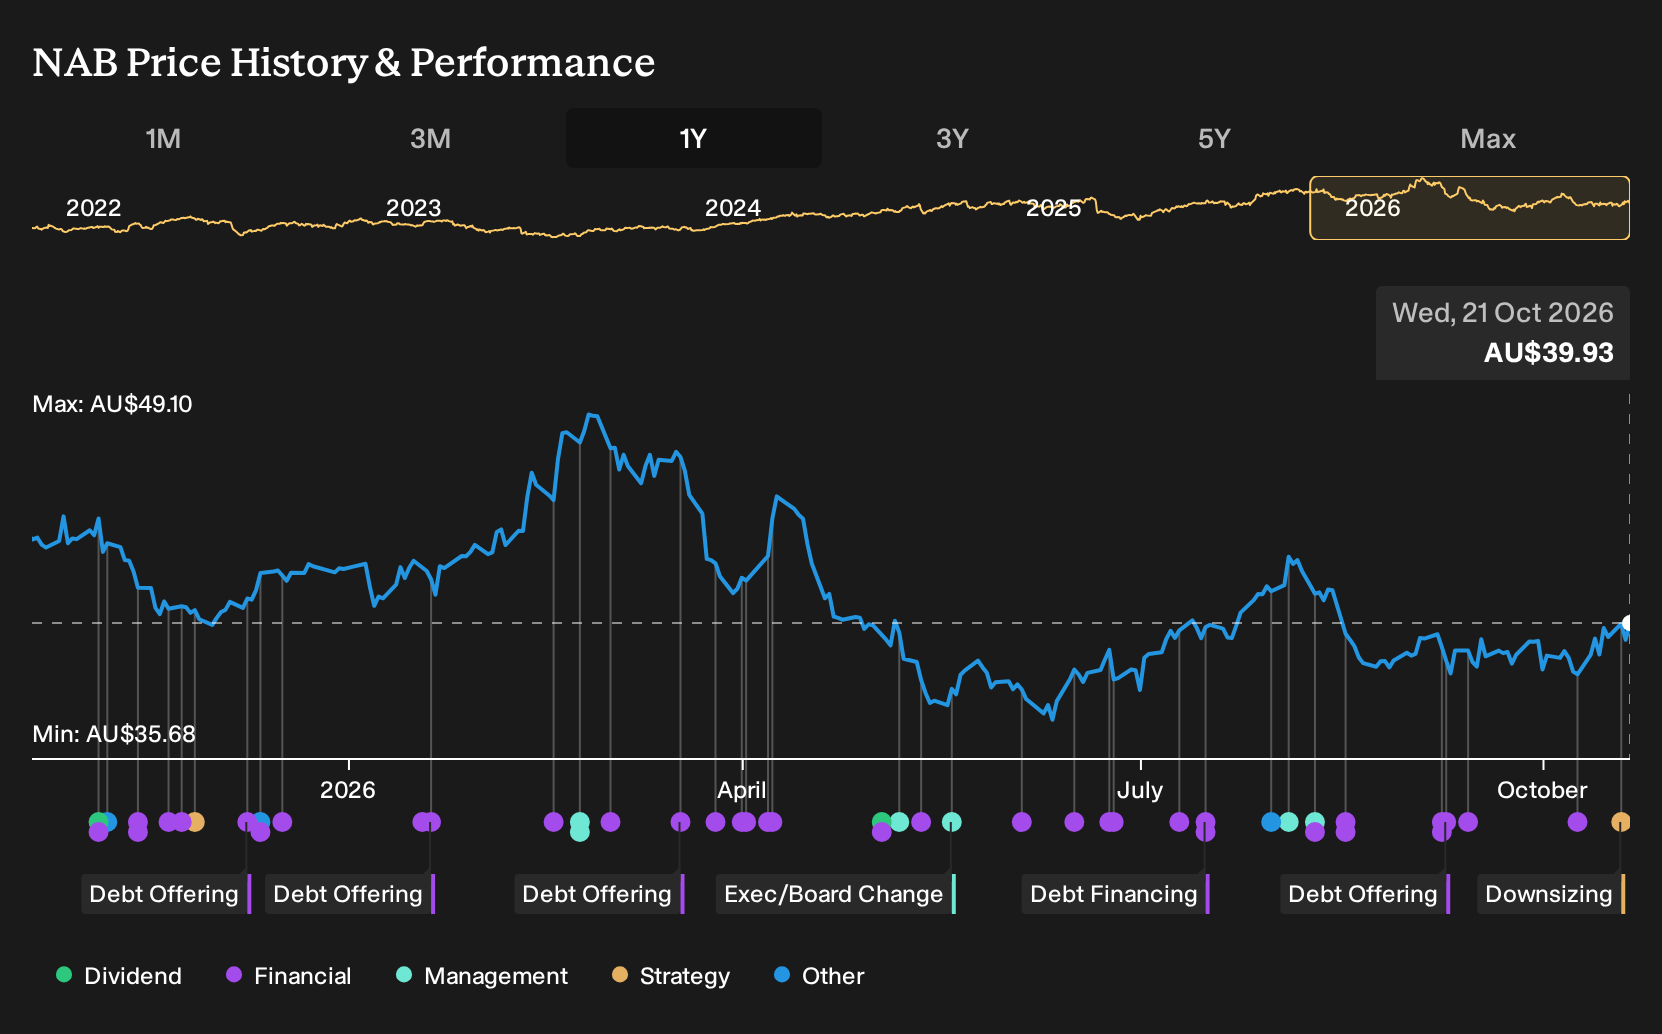
- National Australia Bank has already begun a multi year simplification program that includes reducing its internal workforce by up to 2,500 roles, or about 6%, booking an expected A$300 million pre tax restructuring charge in FY 2027 and cutting use of consultants and contractors.
- The planned headcount reduction and lower reliance on external contractors suggest management is attempting to reset the underlying cost base to support technology projects, business banking, deposit gathering and proprietary home lending priorities.
- We will now consider how National Australia Bank’s investment narrative could be affected by this large scale workforce reduction and cost reset.
National Australia Bank Investment Narrative Recap
To own National Australia Bank, you need to believe the cost base can be reshaped enough to support heavy technology spend while keeping net margins intact. The current simplification plan, including up to 2,500 role reductions and fewer contractors, goes straight to that issue. The key short term catalyst remains execution on digital payments, business banking platforms and deposit growth. On the risk side, any slippage that leaves expenses running ahead of revenue, or weak credit quality in business lending, would cut directly against that thesis.
The restructuring charge of about A$300 million in FY 2027 looks material but not thesis breaking on its own. It mainly pulls forward pain that was already embedded in the cost risk. The bigger operational question is whether National Australia Bank can convert these cuts into sustained improvement in the cost to income ratio without disrupting core business lending, deposits and proprietary home lending priorities.
The recent Hong Kong dollar bond issue, a HK$1b 3.90% senior unsecured note due October 2027, sits alongside this restructuring story rather than driving it. For you, the relevance is funding mix. Access to offshore wholesale markets at fixed coupons can shape how National Australia Bank funds technology investment, business lending growth and deposit gathering campaigns while managing its net interest margin.
That debt deal also matters for risk. Higher wholesale funding always interacts with asset quality and capital usage. If credit costs rise in stressed business sectors or risk weighted asset growth stays heavy, reliance on external funding could limit flexibility on dividends or balance sheet expansion. The combination of restructuring costs, ongoing tech spend and funding decisions is where the real execution test now lies for this bank.
National Australia Bank is being valued on a set of projections that point to A$24.2b in revenue and A$8.1b in earnings by 2029. These projections are built on analyst assumptions of 5.0% yearly revenue growth and an earnings uplift from A$6.1b today to A$8.1b, which is about a 1.3x increase.
Uncover why National Australia Bank's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view focuses on digital disruption risk. Under that lens, you would worry that National Australia Bank spends heavily on technology yet still loses share to faster fintech rivals. The most cautious analysts were working off revenue of about A$23.7b and earnings of A$7.8b by 2029, so this new workforce reset could shift those expectations. Use that spread in opinions as a prompt to test your own assumptions before reacting to the headlines.
Explore 4 other National Australia Bank fair value estimates, including one that suggests it could be worth just A$38.46.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your National Australia Bank research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for National Australia Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Australia Bank's overall financial health at a glance.
Looking For More Investment Ideas Beyond National Australia Bank?
If this reset story at National Australia Bank has you rethinking your watchlist, it can help to compare it with other businesses facing different cost pressures and balance sheet profiles. The Simply Wall St Screener lets you scan for companies that fit whatever mix of quality, value and resilience you care about most, then track them over time instead of reacting only to headlines.
- If you want resilience first and upside second, start with a 6 resilient stocks with low risk scores that have historically kept risk scores in check while still offering room for your own thesis.
- For investors focused on strong foundations rather than short term stories, compare National Australia Bank with a list of solid balance sheet and fundamentals (12 results) that pair robust finances with cleaner balance sheets.
- If you are hunting for less crowded opportunities, scan a 15 high quality undiscovered gems that combine solid fundamentals with limited current attention from the broader market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com