


The Zhitong Finance App learned that at the end of September 2026, Cui Dongshu published an article stating that at the end of September 2026, the national passenger car industry had inventory of 3.21 million vehicles, an increase of 70,000 units over the previous month and a decrease of 70,000 units from September 2025, forming a characteristic that inventory continued to hover in the 3rd quarter. Based on inventory at the end of September 2026 and a comprehensive estimate of domestic retail sales volume for the next 3 months, the number of future sales days is 56 days. Compared with 50 days in September 2023, 49 days in September 2024, and 60 days in September 2025, the overall number of inventory days in September this year is still relatively under pressure.
The Passenger Link Branch predicts that satisfaction will continue to plummet to a low level starting in October 2025. Optimism in September 2026 was 38%, and satisfaction was 19% after September in early October. Expectations are low but satisfaction is not high. Mainly, the impact of high oil prices is too big. The team's optimism about the October market fell to 23%. This is a neutral forecast index for judging market optimism for the past 3 months, but it is lower than 38% in September.
The total inventory of companies that only produce new energy vehicles rose to 880,000 units in September 2026, an increase of 30,000 units over the previous month, an increase of 100,000 units from the peak inventory of 780,000 units in November 2025, but the same as the 880,000 units in April 2025. Recently, the manufacturer and channel inventories of new energy dealers faced lower than expected retail sales in the market, and the overall pressure on industry inventories was high.
1. Passenger car retail trends in the narrow sense of the word in recent years
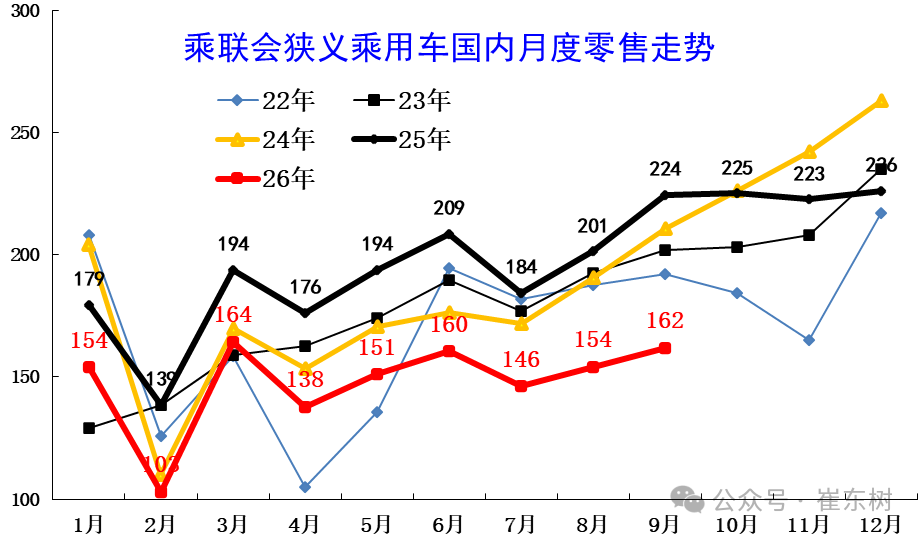
In September, the national passenger car market retailed 1.62 million vehicles. The month-on-month growth performance was weak, leaving the normal growth season trend line. There are many reasons for the continued downturn in September. The first was the impact of high oil prices, followed by the Mid-Autumn Festival holiday. The year-on-year decline was due to the strong regulatory nature of the new trade-in policy and the reduction in passenger car subsidies. Coupled with the sharp impact of upstream price increases, the root cause was low consumption capacity and willingness.
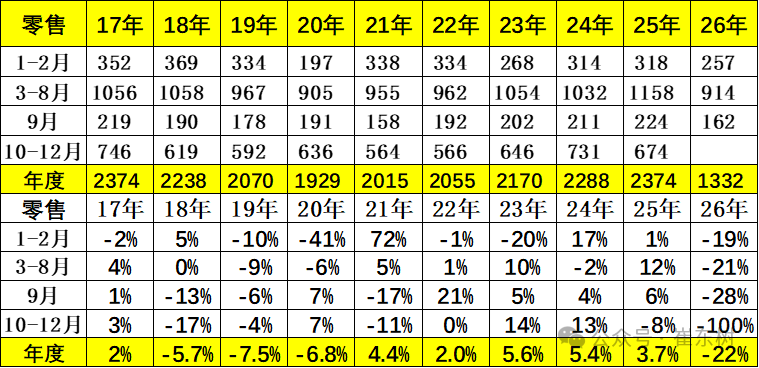
In September 2026, the national passenger car market retailed 1.618 million vehicles, down 28.0% year on year and up 5.0% month on month; from January to September, the total retail sales of passenger cars was 13.334 million units, down 21.7% year on year.
In September 2026, the domestic passenger car market showed a trend of continuous total pressure, month-on-month weakening, and extreme structural differentiation. The downturn in the off-season was highlighted, and the structural adjustment of the industry was further deepened.
2. Passenger car wholesale trends in the narrow sense of the word in recent years
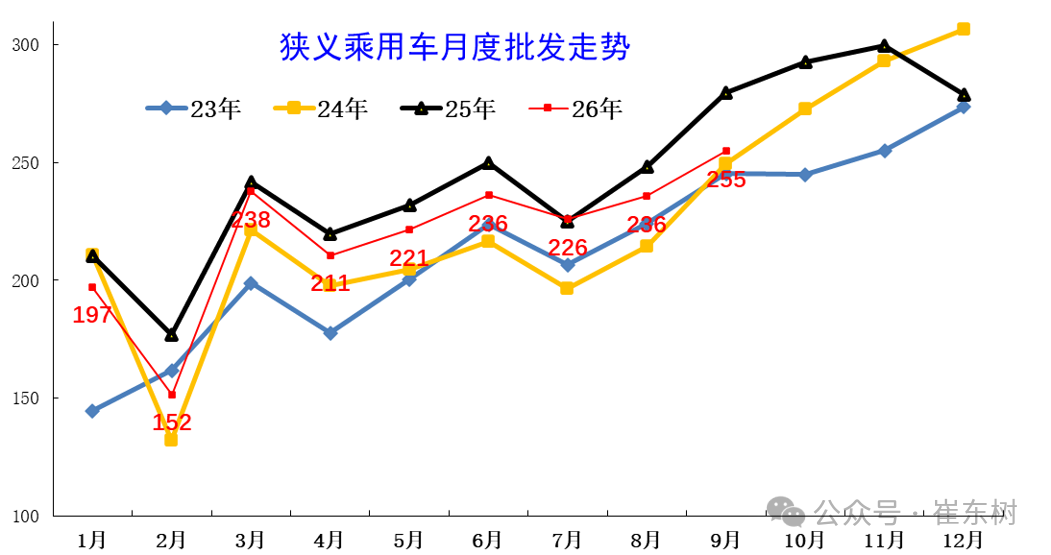
Passenger car manufacturers across the country wholesale 2.55 million vehicles in September, a significant decline over the same period. The trend in September of previous years was relatively strong. The domestic economy was sluggish but export growth was high this year, so the overall return was stable. Due to strong exports, few domestic wholesalers, and good inventory removal results, channel pressure has improved markedly.
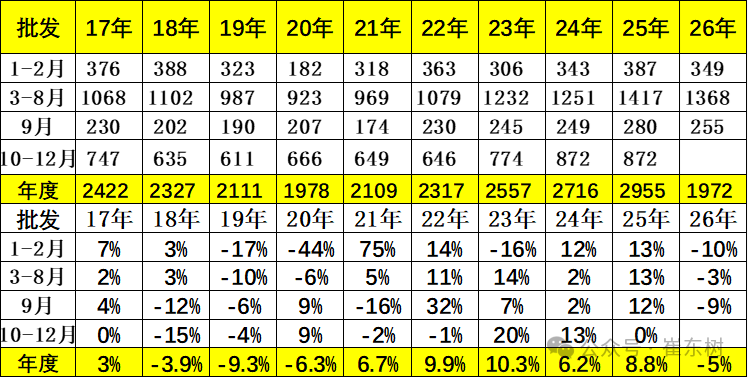
In September, the country's passenger car manufacturers wholesale 2,549 million vehicles, down 8.9% year on year and up 8.1% month on month; encouraged by the surge in exports, the year-on-year growth rate of passenger car wholesale in September was 19 percentage points higher than the retail growth rate.
3. Recent trends in passenger car production in the narrow sense
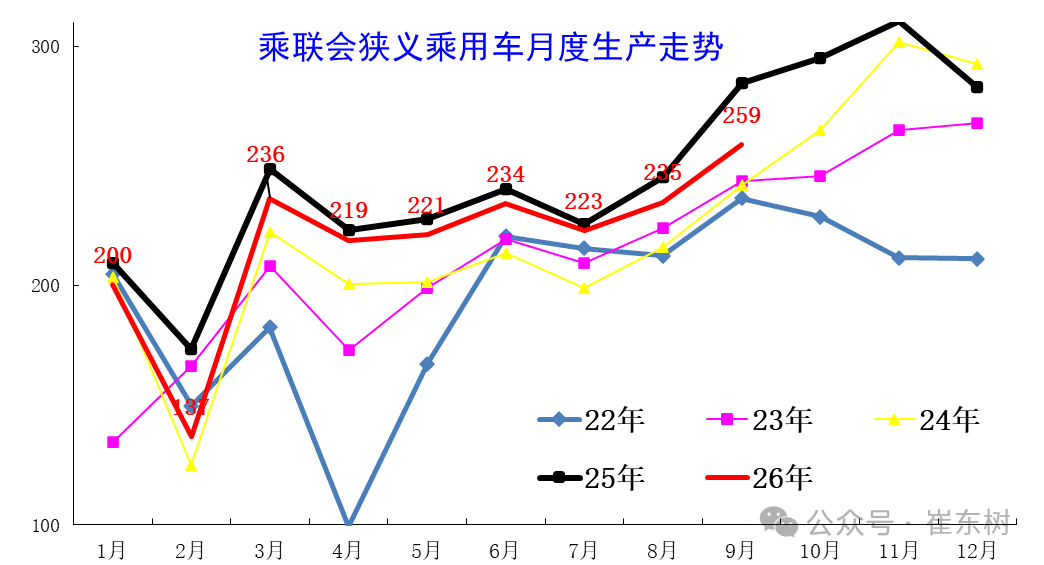
Passenger car production will be drastically reduced in 2026. The month-on-month increase in September was 10.3%, and the trend was strong. Exports continued to strengthen, leading to a relatively high in September production during the year, but the year-on-year trend declined significantly.
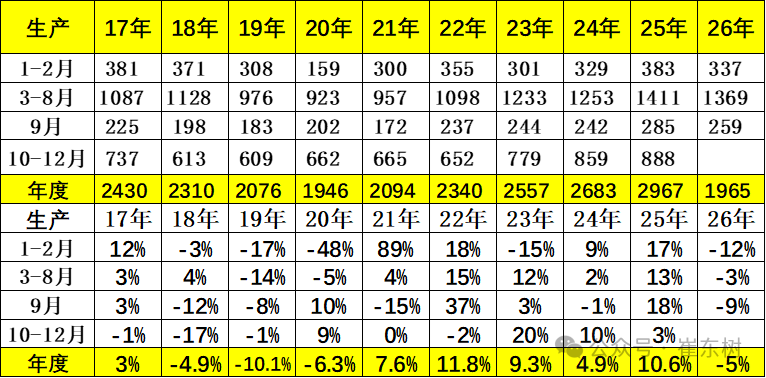
Passenger car production in September was 2.59 million units, down 9.1% year on year, with a cumulative decline of 5% in 2026, with a significant impact on domestic demand.
4. Recent passenger car export trends in the narrow sense
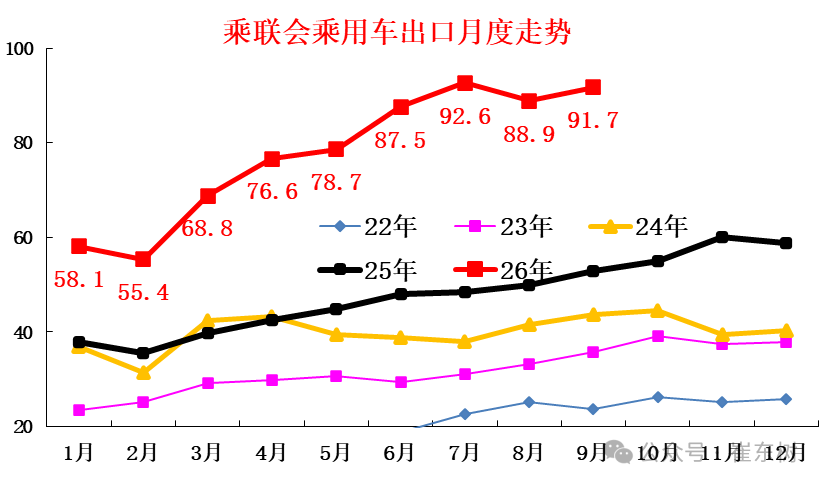
Exports rebounded slightly in September compared to August, but did not break through the July peak for two consecutive months. The rapid month-on-month upward trend changed, and the market gradually entered a stable period.
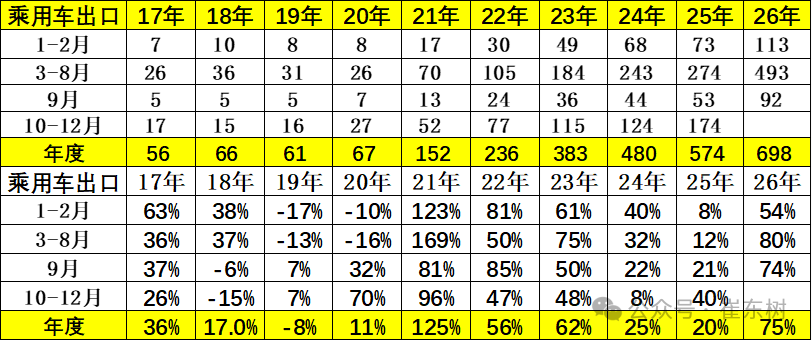
Passenger car exports (including complete vehicles and CKD) were 917,000 units in September, up 73.7% year on year and 3.2% month on month, accounting for 36% of passenger car manufacturers' sales volume (38% last month, 19% in the same period in 2025). New energy vehicles accounted for 60.8% of total exports in September, a sharp increase of 21 percentage points over the same period.
5. National passenger car industry inventory tracking
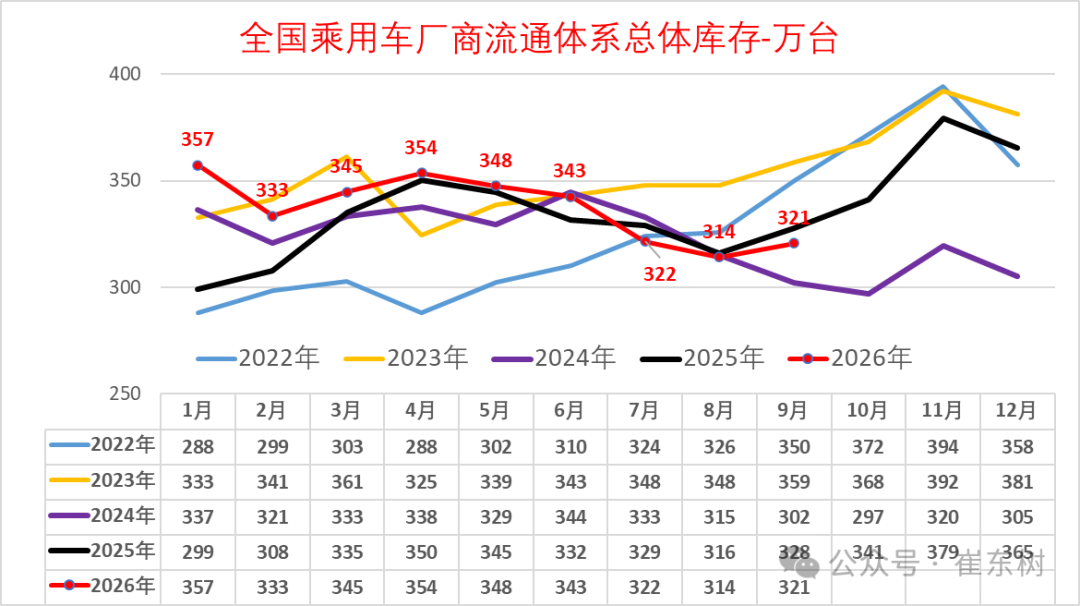
At the end of September 2026, the national passenger car industry had an inventory of 3.21 million units, an increase of 70,000 units over the previous month and a decrease of 70,000 units from September 2025, which is characterized by continuous inventory fluctuation in the 3rd quarter. The launch of the trade-in policy in 2025 brought about overall optimism among manufacturers. The sales volume driven by trade-in was high, and manufacturers were relatively cautious in production, resulting in continuous inventory removal from May to September. Since the market has seriously fallen short of expectations since November last year, inventories hit a new high of nearly two years in November. Since then, the decline in production has been strong, but the decline in retail sales in the first half of the year also exceeded expectations. As a result, inventories were high in the first half of the year. Production cuts in July-September were strong, and inventories dropped significantly compared to the same period. The characteristics of inventory changes this year are quite different from those of the past few years.
6. National passenger car manufacturer inventory tracking
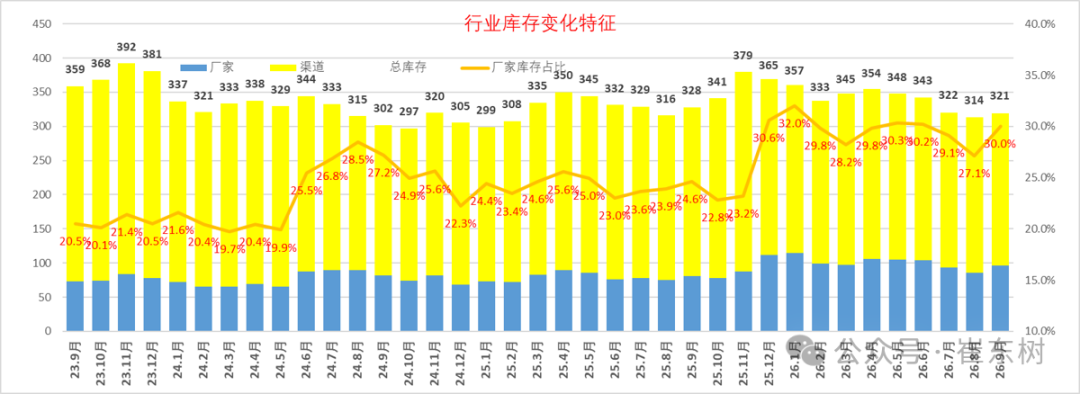
Since 2023, the overall inventory of the passenger car industry has remained relatively stable. It fell back to 2.97 million units in October 2024, rebounded to 3.79 million units in November 2025, then declined. Inventory in September 2026 fell to 3.21 million units, of which the manufacturer's inventory accounted for 30%, and the inventory from manufacturer vacations in August was made up in September.
Due to good market expectations in the early stages, manufacturers are enthusiastic about production, and overall industry inventory pressure is relatively uncontrollable. Currently, the share of manufacturers' inventory is gradually increasing, the market is seriously sluggish, manufacturers are cutting production, and the inventory pressure to absorb strong sales in the next few months is generally manageable.
7. National Passenger Vehicle Market Forecast Index and Satisfaction Index
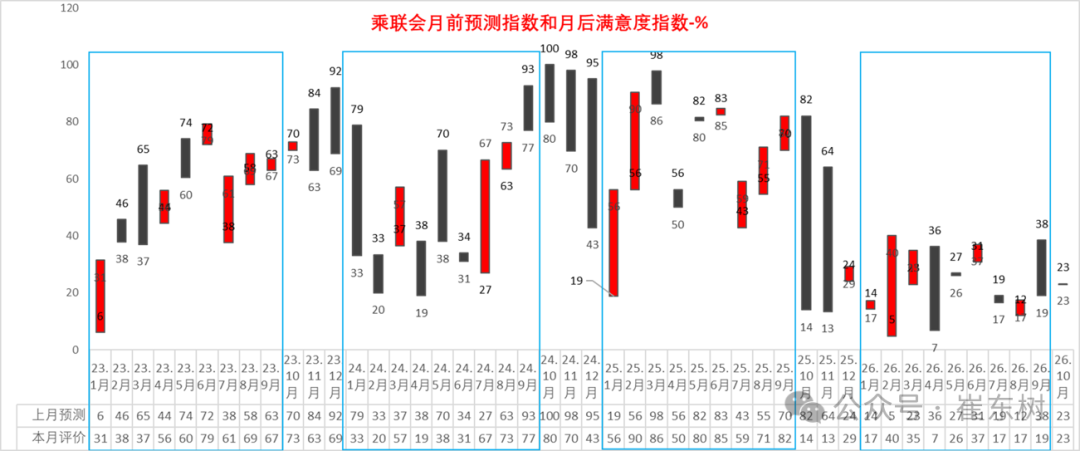
Monthly market performance is evaluated according to how the PMI index is set and evaluation results. According to the forecast summary estimates of the manufacturer's insiders, the prediction team of the Chengdu Branch has been very optimistic and gradually pessimistic since the beginning of 2025. The forecasting team was very optimistic about the market forecast from January to September 2025, and satisfaction continued to plummet to a low level starting in October 2025. Optimism in September 2026 was 38%, and satisfaction was 19% after September in early October. Expectations were low but satisfaction was poor, mainly because the impact of high oil prices was too great.
As the market continued to fall short of expectations, and everyone's acceptance was adjusted, the team's optimism about the October market dropped to 23%. This is a neutral forecast index for judging market optimism for the past 3 months, but it is lower than 38% in September, which shows that everyone is more cautious. From the current inventory level of 3.21 million vehicles and expectations to judging market growth in the next few months, the pressure on the industry to absorb inventory is still strong. In view of the current situation where sales continue to fall short of expectations, car companies need to promptly track changes in the policy environment and market, carefully set the pace of production and sales, carefully increase inventory according to the dealer inventory structure, and clean up historical inventory in a timely manner.
8. Overall inventory characteristics of the national passenger car market
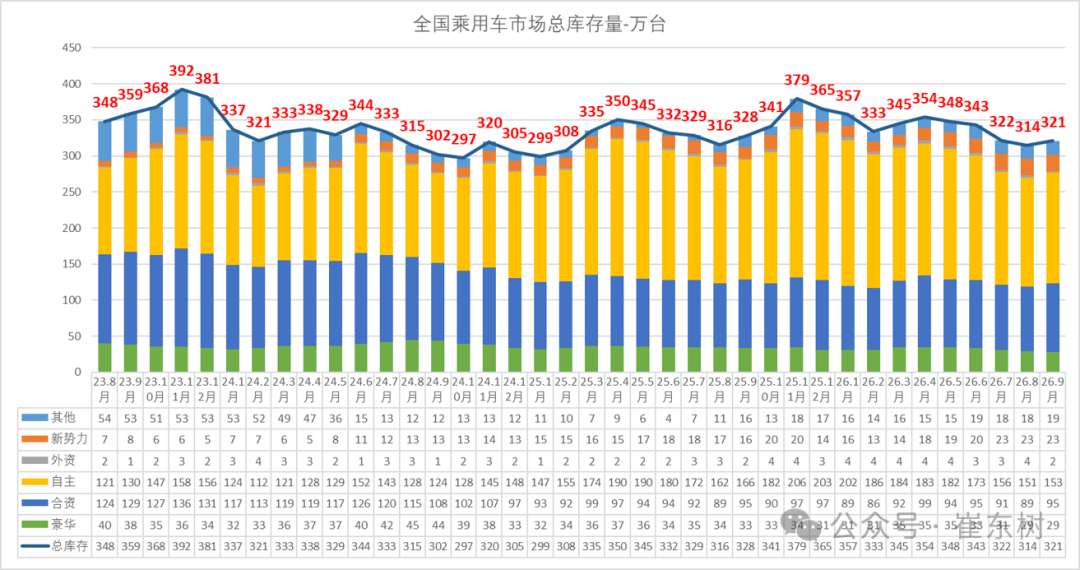
As the share of new energy vehicles increased, fuel vehicle sales declined, and the corresponding inventory pressure gradually decreased. Looking at the inventory cycle, from 3.25 million units in April 2023, then rebounded to 3.92 million units in November 2023, then declined to a low inventory level of 2.97 million units in October 2024.
The period from 2025 to early 2026 is still an inventory increase cycle, and the pressure on the industry continues to increase, reaching a recent high of 3.79 million in November 2025. The car market declined significantly in 2026. Due to the severe contraction of fuel vehicles, although inventories declined, the pressure on inventories was not effectively relieved.
9. US passenger car industry inventory comparison
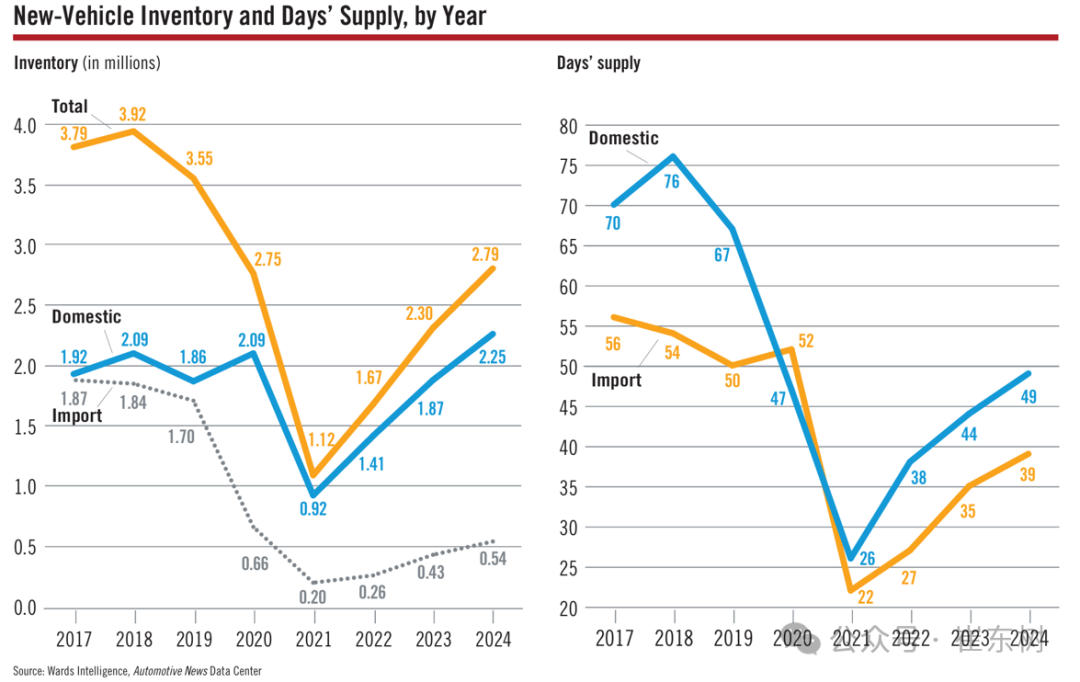
The US inventory is currently in 40-50 days, and the overall inventory pressure is low. This is also a reference target for the Chinese car market.
10. The number of inventory days in the national passenger car market declined slightly
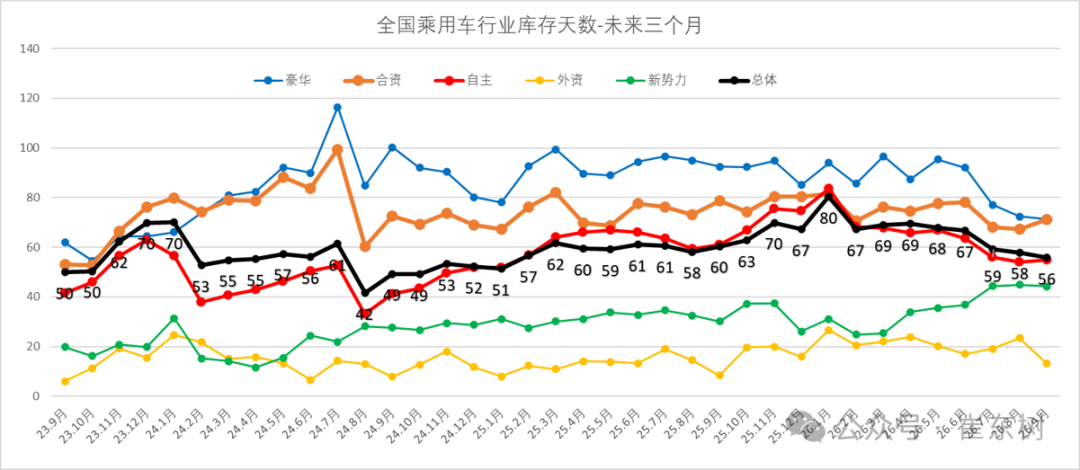
The estimated number of inventory days is based on the sales volume for the next 3 months, but since retail sales in September are lower than expected, the corresponding number of inventory days for July will also change as a result, that is, how much inventory will be at the end of September, mainly depending on sales expectations for the next 3 months. As the market recovery arrived as scheduled in 2025, the production trend was strong. The characteristics of inventory removal in the early stages changed, and the reverse internal volume brought about inventory control in the industry, and inventory growth was relatively moderate. In the fourth quarter of 2025, although the expiration of the tax exemption policy was promoted, the trend actually fell short of expectations. The peak number of days in industry inventory rebounded to 80 days, and production cuts were strong in 2026. Therefore, based on inventory at the end of September 2026 and the current inventory based on a comprehensive estimate of domestic retail sales volume for the next 3 months, the number of future sales days is 56 days. Compared with 50 days in September 2023, 49 days in September 2024, and 60 days in September 2025, the overall inventory days in September this year are still relatively under pressure.
11. The national inventory of new energy passenger vehicles continues to rise
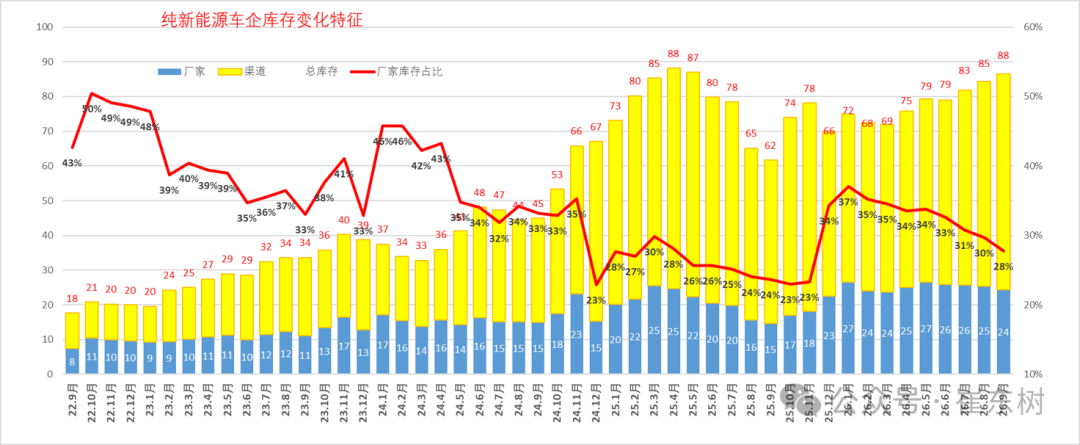
Judging from the analysis of inventory change characteristics of companies that only produce new energy vehicles, the inventory of 200,000 units was in early 2023, and then entered a period of rapid inventory growth. In April 2025, the inventory of companies that only produce new energy vehicles reached 880,000 units. This is a recent peak. With the push of internal scrutiny, industry inventories fell to 620,000 units in September 2025, and the total inventory of companies that only produce new energy vehicles rose to 880,000 units in September 2026, an increase of 30,000 units over the previous month, an increase of 100,000 units from the peak of 780,000 units in November 2025, but remained the same as the 880,000 units in April 2025. Recently, the manufacturer and channel inventories of new energy dealers faced lower than expected retail sales in the market, and the overall pressure on industry inventories was high.