


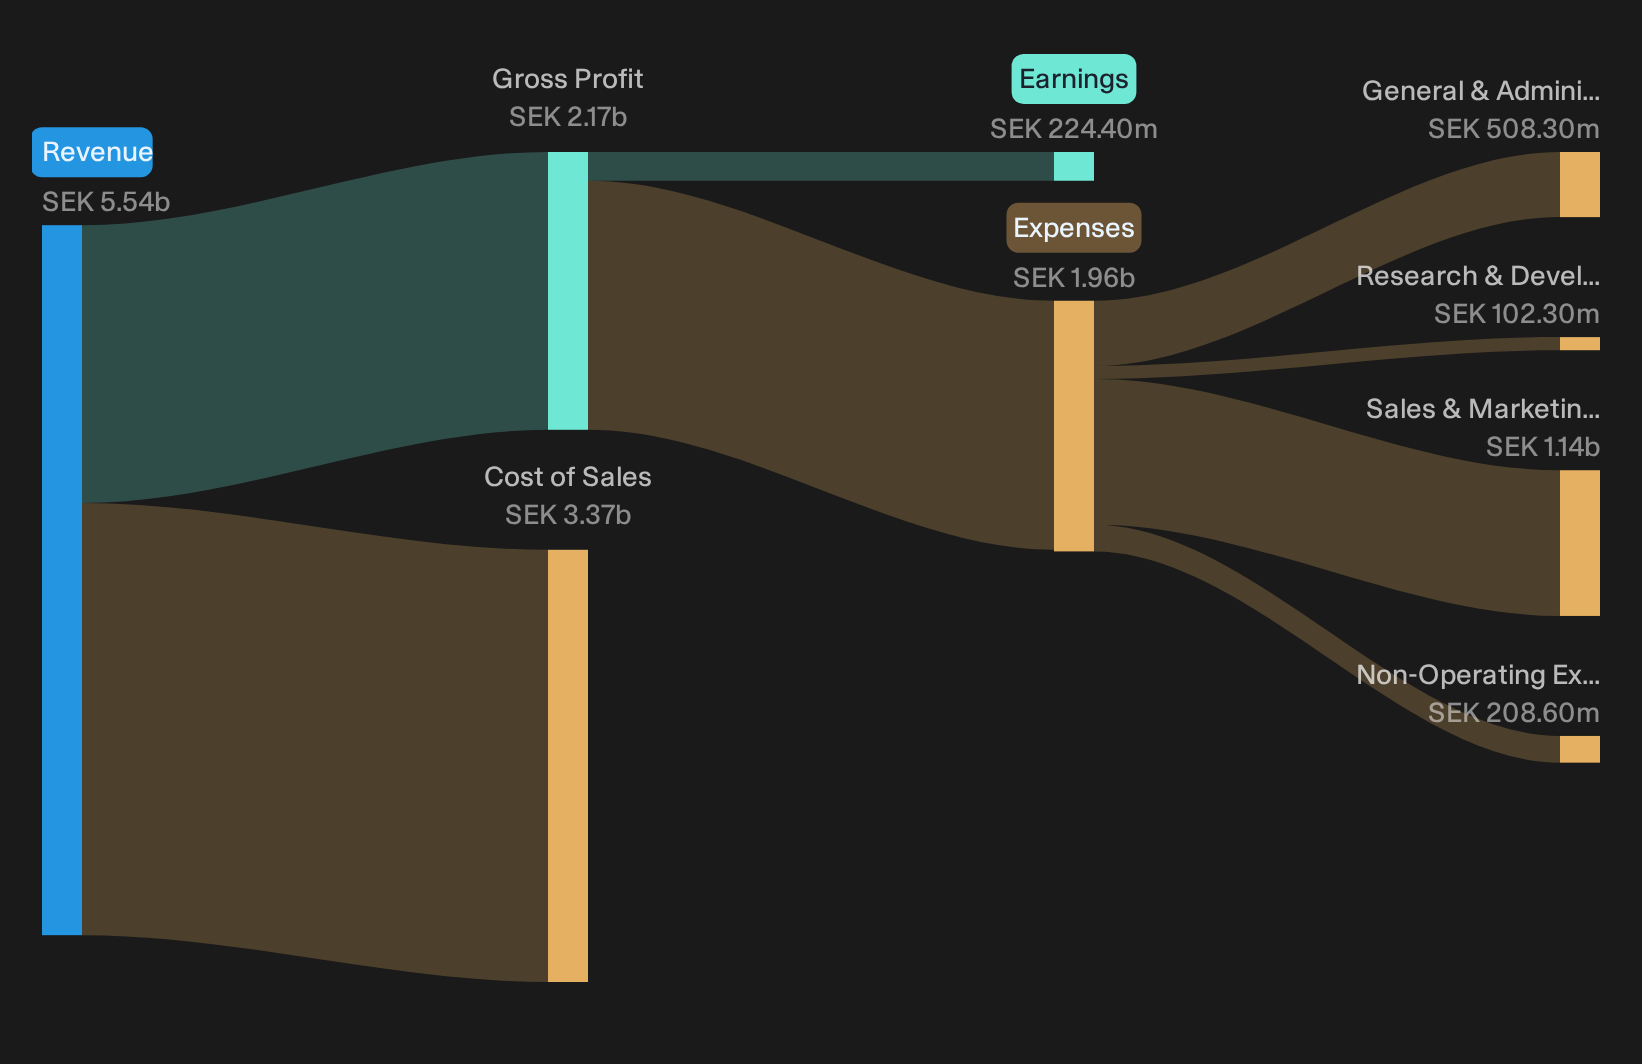
Nederman Holding came into yesterday’s Q3 2026 release with the stock at SEK143.6, carrying a reputation as a high quality industrial cleaner of factory air but with questions over earnings power. The headline this quarter is clear: sales reached SEK1,420m while basic earnings per share printed at SEK1.68, and that profit figure still reflects pressure on group margins versus last year.
For a business on a P/E of 22.4x and trading well below one published fair value estimate, the tension for you as an investor is simple. The share price reaction now has to reconcile that valuation gap with a quarter where cash generation improved yet profitability stayed under strain.
Love Nederman Holding’s cash generation but concerned about the pressure on profitability at a 22.4x P/E? Compare it with industrial peers that combine earnings quality with stronger balance sheets in our list of solid balance sheet and fundamentals stocks (203 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): SEK 1,420m vs. SEK 1,434.3m (down 1.0%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): SEK 59m vs. SEK 79.6m (down 25.9%)
- Basic EPS (Q3 2026 vs. Q3 2025): SEK 1.68 vs. SEK 2.27 (down 26.0%)
- Trailing 12-Month Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): SEK 224.4m vs. SEK 296.1m (down 24.2%)
Skip the headline backlog optimism. Ask Charlie what Nederman’s Q4 margin setup really is.
Nederman Holding: Orders, Cash And ESG Tailwinds
Bulls in Nederman Holding will point straight to the order book and cash. Organic order intake grew double digit and management reports seven months of improving intake, which supports the ESG anchored industrial narrative rather than contradicting it. Q3 delivered the strongest operating cash flow and the best sales quarter year to date. Service and aftermarket now sit at roughly 23% of turnover, giving more recurring revenue around the filtration and monitoring installed base.
Margin Pressure, Mix And Cyclical Concerns
The cautious view gets support from earnings quality. Group adjusted EBITA dropped from SEK166m to SEK131m and the margin moved to around 9.2%. Revenue was essentially flat while basic EPS fell, which flags weaker profitability even as projects ramp. Process Technology suffered from softer mix and lower volume and management still calls out macro, China competition and APAC investment drag. For a cyclical industrial supplier that sells into capex budgets, this keeps the bear case about earnings risk very much alive.
After margin compression, dividend volatility and earnings drifting lower over time, it is fair to ask whether Nederman Holding’s challenges are temporary or structural. Review our risk analysis for Nederman Holding which shows 3 important warning signsHunt For Disconnected Fundamentals
Nederman Holding shows how solid cash flow can coincide with questions about margins and execution. The real opportunity sits with stocks that may be undervalued before sentiment adjusts to revised expectations.
- Company 1 - 29% below our estimate - focuses on complex manufacturing programs that move from design wins into sustained production across regulated sectors.
- Company 2 - 37% below our estimate - concentrates resources on core fans to manage costs while timing new content and merchandise launches later in the year.
- Company 3 - 23% below our estimate - pushes higher margin packaged foods and branded drinks while using cost control to support earnings across related consumer categories.
Three companies from the same screener. Open all 190 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com