


- Eaton is reporting strong demand for electrical equipment tied to data centers and grid projects, with a 43% year-over-year electrical backlog increase, 14% organic sales growth, and more than US$1b committed to expanding Electrical Americas capacity.
- The business is leaning into this demand with larger bets on data center and grid solutions, including the Boyd Thermal and COL Group deals, along with a raised 2026 organic growth outlook of 11% to 13%.
- We will now look at how Eaton's expanding electrical backlog and capacity buildout could reshape the investment narrative around the business.
Scan the power grid theme beyond Eaton by lining up opportunities in data-center and infrastructure beneficiaries using our hand-picked 42 power grid technology and infrastructure stocks.
Eaton Investment Narrative Recap
To own Eaton, you need to believe the long run story in electrification, data centers and grid investment will keep feeding its electrical backlog and justify the current premium P/E multiple. The recent update, with 43% electrical backlog growth and 14% organic sales growth, reinforces that demand is currently there rather than changing the narrative.
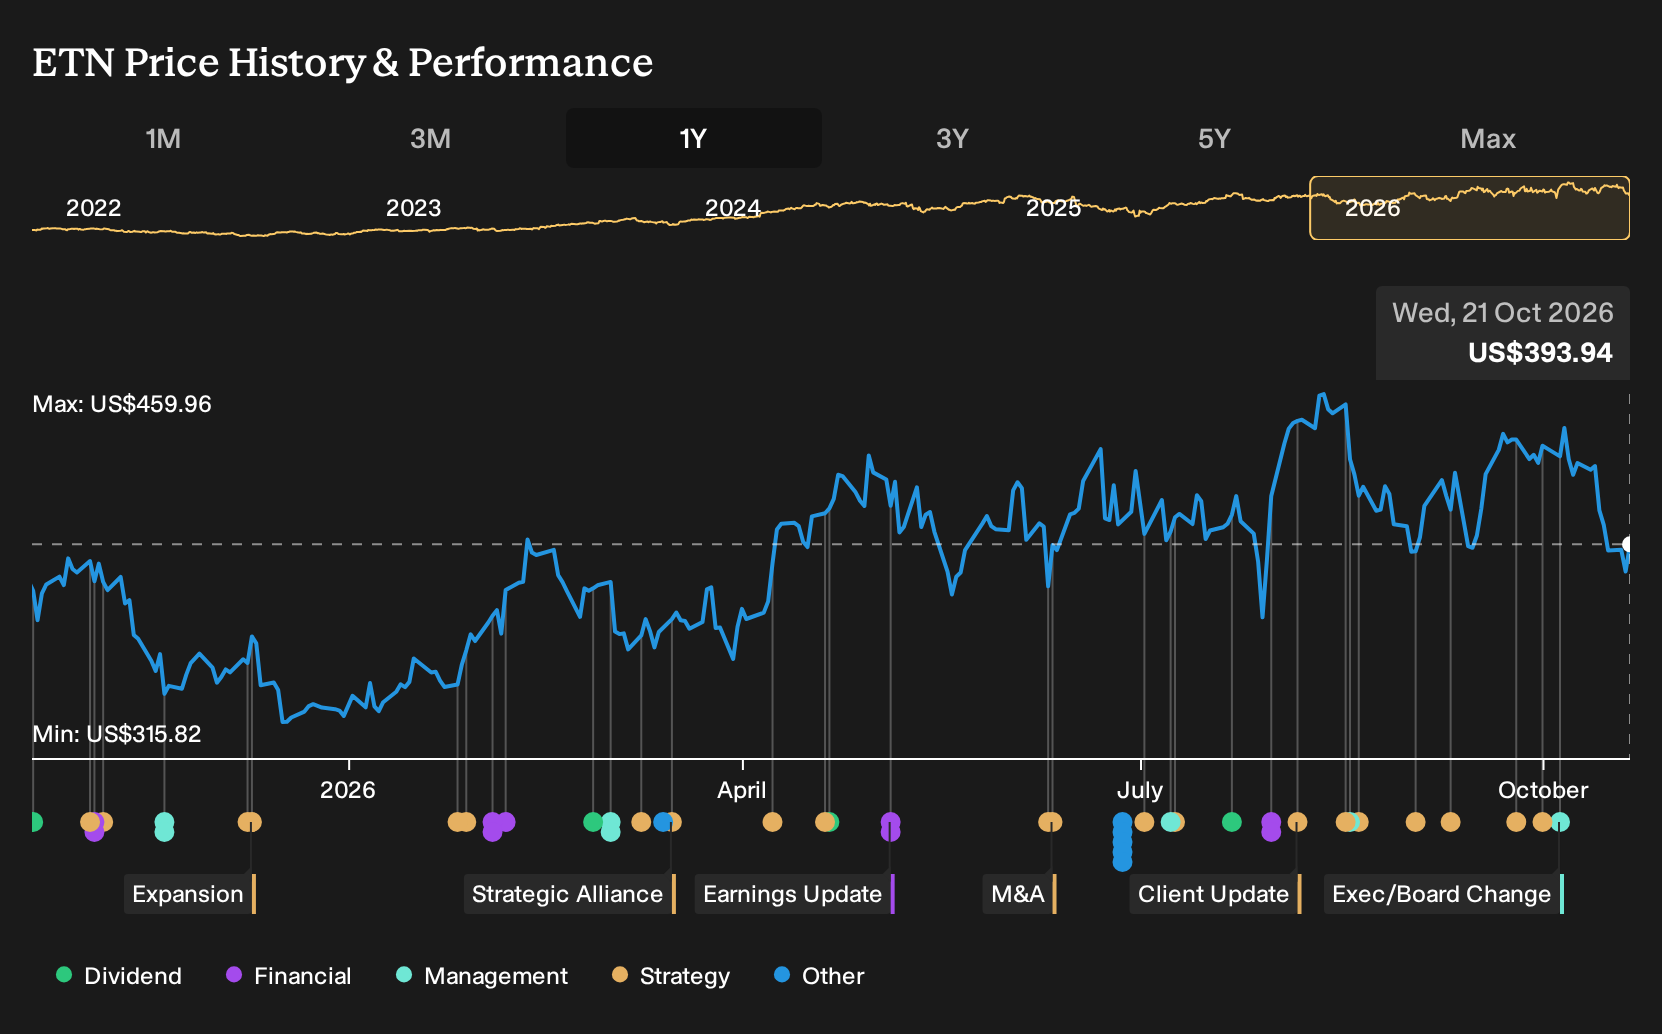
In the near term, the key catalyst is Eaton converting that larger backlog into higher Electrical Americas output and margins as more than US$1b of new capacity ramps. The main risk is that high expectations meet any miss on revenue, earnings or integration progress, given valuation sensitivity and prior sharp share price reactions.
The clearest news item linked to this theme is management lifting its 2026 organic growth outlook to a range of 11% to 13%, supported by the heavier electrical backlog and new capacity in the Americas. That guidance sits on top of the existing expansion program of more than US$1b, data center strength and grid oriented orders already in hand.
For you as an investor, that higher growth range ties directly into the near term catalyst. Execution on projects such as the Electrical Americas buildout and the COL Group and Boyd Thermal integrations will influence whether Eaton converts backlog and AI data center demand into sustained margins, or whether cost, debt and integration complexity start to dominate the story.
Eaton's current analyst narrative points to revenues of US$43.4b and earnings of US$7.5b by 2029. This outlook is built on an assumed 13.0% yearly revenue growth rate and an earnings increase of US$3.7b from US$3.8b today.
Uncover how Eaton's fair value indicates a 22% potential upside to its current price, which could narrow quickly if Eaton keeps executing on this backlog.
Exploring Other Perspectives
One alternate view on Eaton focuses on the risk that today’s AI heavy data center pipeline proves front loaded rather than lasting. The lowest analysts were penciling in 2029 revenue of about US$40.9b and earnings of US$6.9b before this backlog news. That is meaningfully below consensus, so use it as a prompt to compare different scenarios.
Explore 7 other Eaton fair value estimates, including one that suggests as much as 11% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider your own analysis.
- A great starting point for your Eaton research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eaton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eaton's overall financial health at a glance.
Looking For More Ideas Beyond Eaton?
If the Eaton story has sharpened your thinking on electrification and infrastructure, it can help to line it up against a wider watchlist. Use the Simply Wall St Screener to spot other companies that match your preferred mix of quality, income and resilience.
- For investors who care most about financial resilience and balance sheet strength, scan a list of solid balance sheet and fundamentals (25 results) that already clears rigorous debt and liquidity checks.
- If you want income on top of potential capital returns, filter for reliable payers through our curated set of 7 dividend fortresses that aim to match higher yields with staying power.
- Those hunting for overlooked opportunities can start with a 21 high quality undiscovered gems that pair strong fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com