


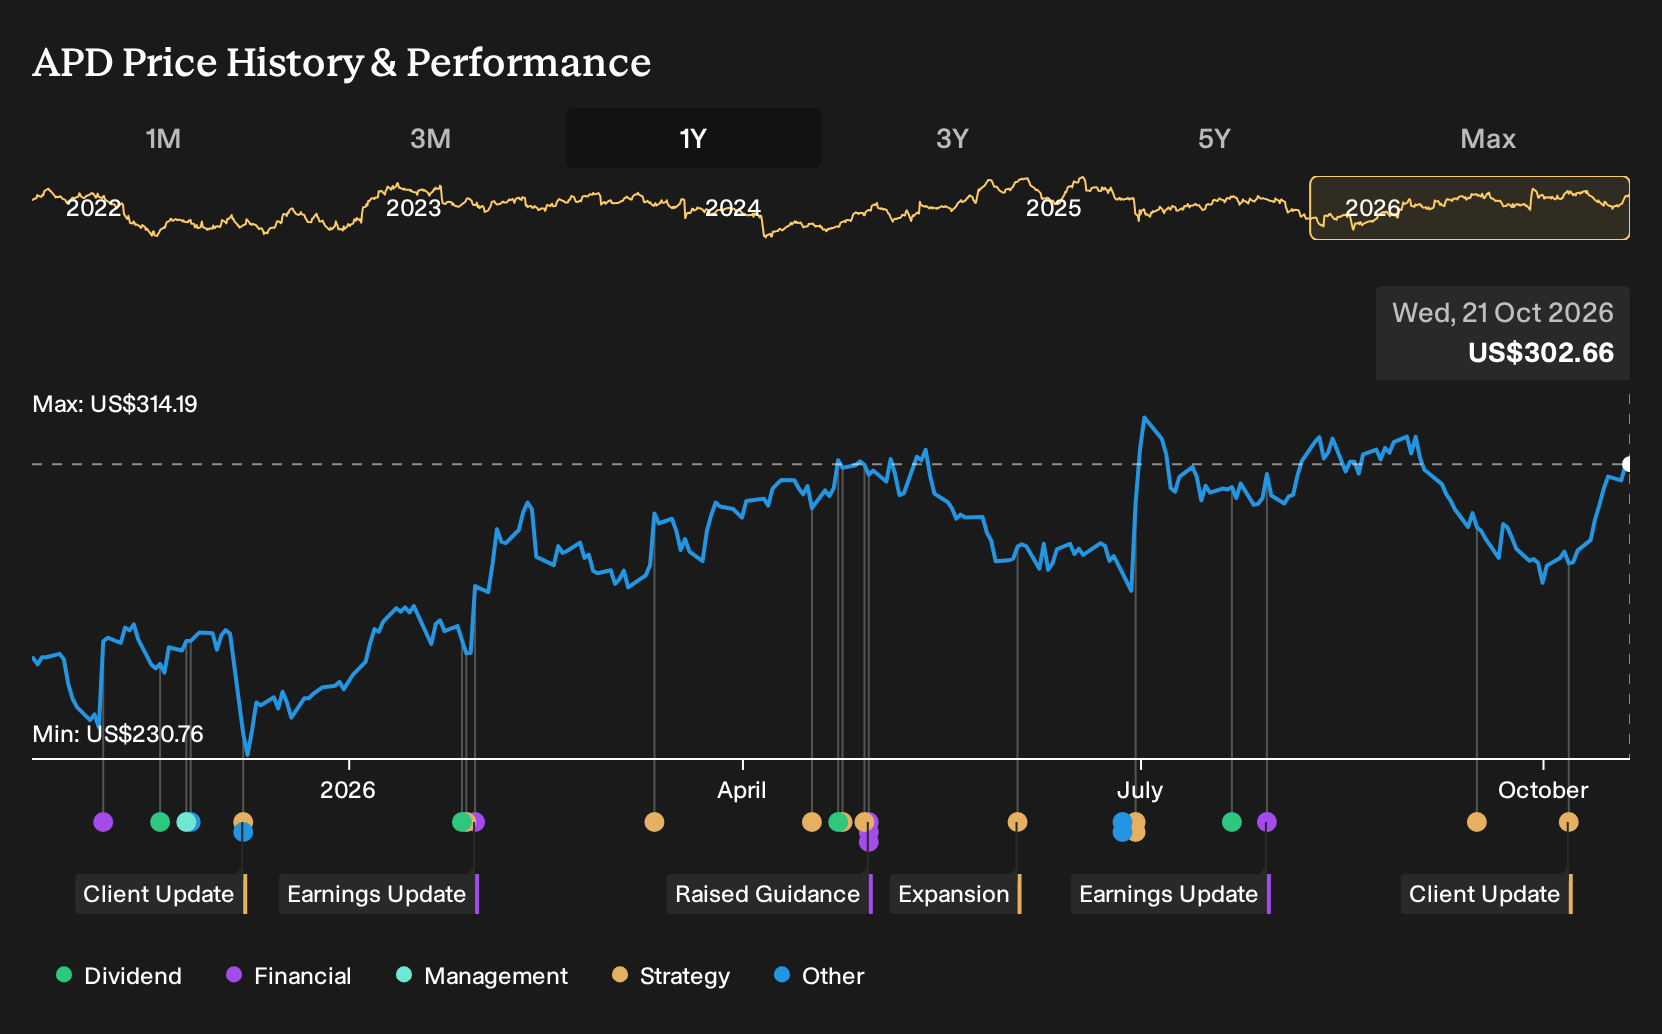
- Air Products and Chemicals raised its fiscal 2026 adjusted earnings guidance and recently presented at FABTECH 2026 in Las Vegas, where it highlighted its industrial gas and clean energy offerings to metals and manufacturing customers.
- The upgraded earnings outlook reflects management’s current view of cost control, productivity progress, and project execution across core gases and energy transition projects as central to Air Products and Chemicals’ operating story.
- Investors can now evaluate how Air Products and Chemicals’ higher 2026 adjusted earnings guidance could influence its investment narrative and overall risk profile.
Scan beyond Air Products and Chemicals and assess how other industrial and clean energy players stack up using our hand picked 33 high quality undervalued stocks.
Air Products and Chemicals Investment Narrative Recap
To own Air Products and Chemicals, you need to buy into a simple idea. The business is trying to turn a large industrial gas platform and big ticket hydrogen and ammonia projects into steadier earnings over time, while keeping capital spending and debt in check. The higher 2026 adjusted earnings guidance leans on cost control and productivity, so it matters most if you believe those programs are truly repeatable.
Right now, the key short term swing factor is whether large projects move from construction to cash generation without fresh cost overruns or delays that strain free cash flow. The biggest risk is a renewed step up in capex or weaker helium and electronics economics that leaves returns on all this invested capital looking thin.
The fresh fiscal 2026 earnings guidance upgrade is the clearest recent announcement to focus on, because it directly ties back to Air Products and Chemicals’ near term execution story. Management is signalling confidence in cost discipline, productivity savings and project performance across both core gases and energy transition assets. For investors, that sets a higher bar for how efficiently new capacity needs to run.
This guidance also intersects with older concerns around heavy spending, dividend coverage and unproductive capital. If earnings progress toward the new target, it helps support the case that high capex and debt are being managed against real operating cash generation. If the higher guidance proves hard to meet, those same balance sheet and return on capital worries move back to the foreground quickly.
What The Long Range Analyst Case Implies For Air Products and Chemicals
Air Products and Chemicals' narrative projects US$15.7b revenue and US$3.9b earnings by 2029. This assumes 7.7% yearly revenue growth and a swing in earnings of about US$4.0b from a loss of US$47.3m today to the forecast profit.
Uncover why Air Products and Chemicals' fair value indicates a 14% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Fair value estimates for Air Products and Chemicals from three Simply Wall St Community members cluster tightly between US$342.35 and US$354.62, yet they still reflect differing conviction levels. You have that spread before factoring in the FABTECH 2026 update, capital discipline decisions, helium contract exposure, and the large clean energy project pipeline. Opinions clearly diverge, so it is worth exploring several of these alternative viewpoints before leaning too hard on any single fair value line.
Explore 2 other Air Products and Chemicals fair value estimates, including one that suggests it could be worth just $342.35.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Air Products and Chemicals research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Air Products and Chemicals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Air Products and Chemicals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Air Products and Chemicals?
Once you have formed a view on Air Products and Chemicals, it can help to line that up against a wider watchlist so you are not relying on a single story. Use the Simply Wall St Screener to build a broader bench of candidates that match the kind of risk, income, or balance sheet profile you want in your portfolio.
- If you want potential upside with a margin of safety, start with our hand picked 33 high quality undervalued stocks that already clear a basic quality and valuation bar.
- For investors who care most about getting paid to wait, filter for income opportunities using this focused set of 7 dividend fortresses with yields above 5%.
- When capital preservation is the priority, narrow your search to a 31 resilient stocks with low risk scores so you can focus on businesses with steadier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com