


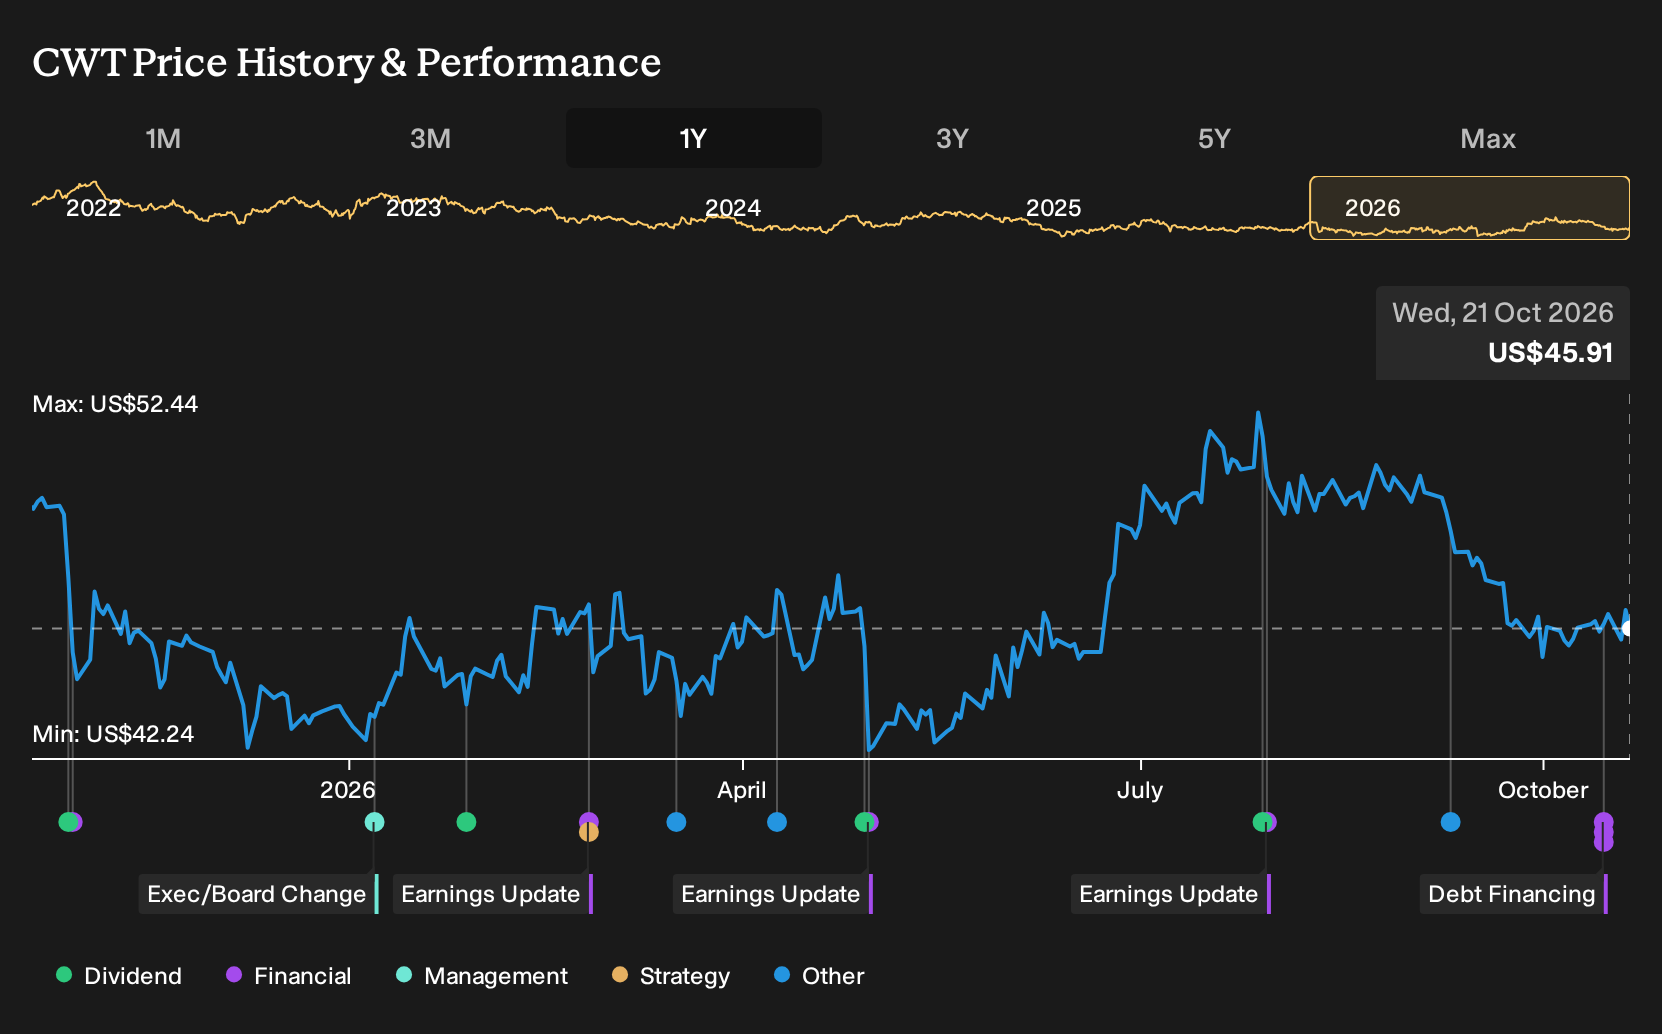
- California Water Service Group recently priced US$125,000,000 of senior unsecured notes and US$150,000,000 of first mortgage bonds, and obtained approval for new regulated water and wastewater rates for its Hawaii Water Service unit to recover infrastructure spending and higher operating costs.
- The Hawaii rate decision gives California Water Service Group clearer cost recovery on recent capital investment in Kapalua systems, which directly links to the long term plan to grow regulated earnings capacity through infrastructure upgrades, PFAS treatment projects, and multi state expansion.
- We will now look at how California Water Service Group's investment narrative may shift as new Hawaii rates support regulated cash flows.
Scan beyond California Water Service Group and compare its regulated-utility profile with 31 resilient stocks with low risk scores that could offer similar balance-sheet resilience and steadier cash flow potential.
California Water Service Group Investment Narrative Recap
To own California Water Service Group, you need to believe that heavy capital spending on pipes, treatment and PFAS projects can translate into steadier regulated earnings over time, not just higher depreciation and interest. The Hawaii rate case supports that thesis by giving clearer recovery on those outlays, although the near term earnings drag from financing and tax costs still matters.
The most important short term swing factor remains how quickly new and existing regulators convert this spending into cash flow, especially in newer states. The biggest risk stays the same: higher capex, rising interest expense and only partial cost recovery could keep pressure on profitability and on dividend and interest coverage.
The recent US$275m in senior unsecured notes and first mortgage bonds sits right at the center of that trade off. California Water Service Group is leaning on debt markets to refinance existing borrowings and fund general corporate needs, which includes a large, multi year capital plan and PFAS work across several jurisdictions.
Those securities bring fixed coupons in the low to mid 6% range and add to an already meaningful interest bill, flagged by analysts as not well covered by earnings. That makes execution on approved projects and timely rate recovery a key catalyst. Stronger cash generation would help support both interest payments and a dividend that is not fully backed by free cash flow today.
California Water Service Group's outlook links analyst expectations for US$1.3b of revenue and US$200.4m of earnings by 2029 to a 6.9% yearly revenue growth rate, which implies earnings rising by about US$67.2m from US$133.2m today to that 2029 consensus level.
Uncover why California Water Service Group's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates from three members of the Simply Wall St Community span roughly US$41 to US$53.75 per share, which already shows how far opinions on California Water Service Group can stretch. When you add the fresh US$275m of fixed rate debt, you can see why views on future cash coverage and equity performance may diverge even more. Readers should treat these contrasting takes as a prompt to explore several alternative viewpoints rather than anchor on any single fair value line.
Explore 2 other California Water Service Group fair value estimates, including one that suggests as much as 17% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your California Water Service Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for California Water Service Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate California Water Service Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond California Water Service Group?
Once you have formed a view on California Water Service Group, it can help to compare that thesis with other opportunities that share similar qualities in income, value, or balance sheet strength. The Simply Wall St Screener lets you scan for these kinds of stocks in minutes, without getting buried in raw data.
- If your priority is stability and capital preservation, focus on companies with lower risk profiles and steadier fundamentals by reviewing a 31 resilient stocks with low risk scores that may suit that brief.
- For readers hunting for quality at a reasonable price, highlight potential value opportunities by checking a 33 high quality undervalued stocks that meet your return and risk expectations.
- If reliable income is higher on your checklist, compare yields and coverage ratios using a 7 dividend fortresses that may support a more dependable payout stream.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com