


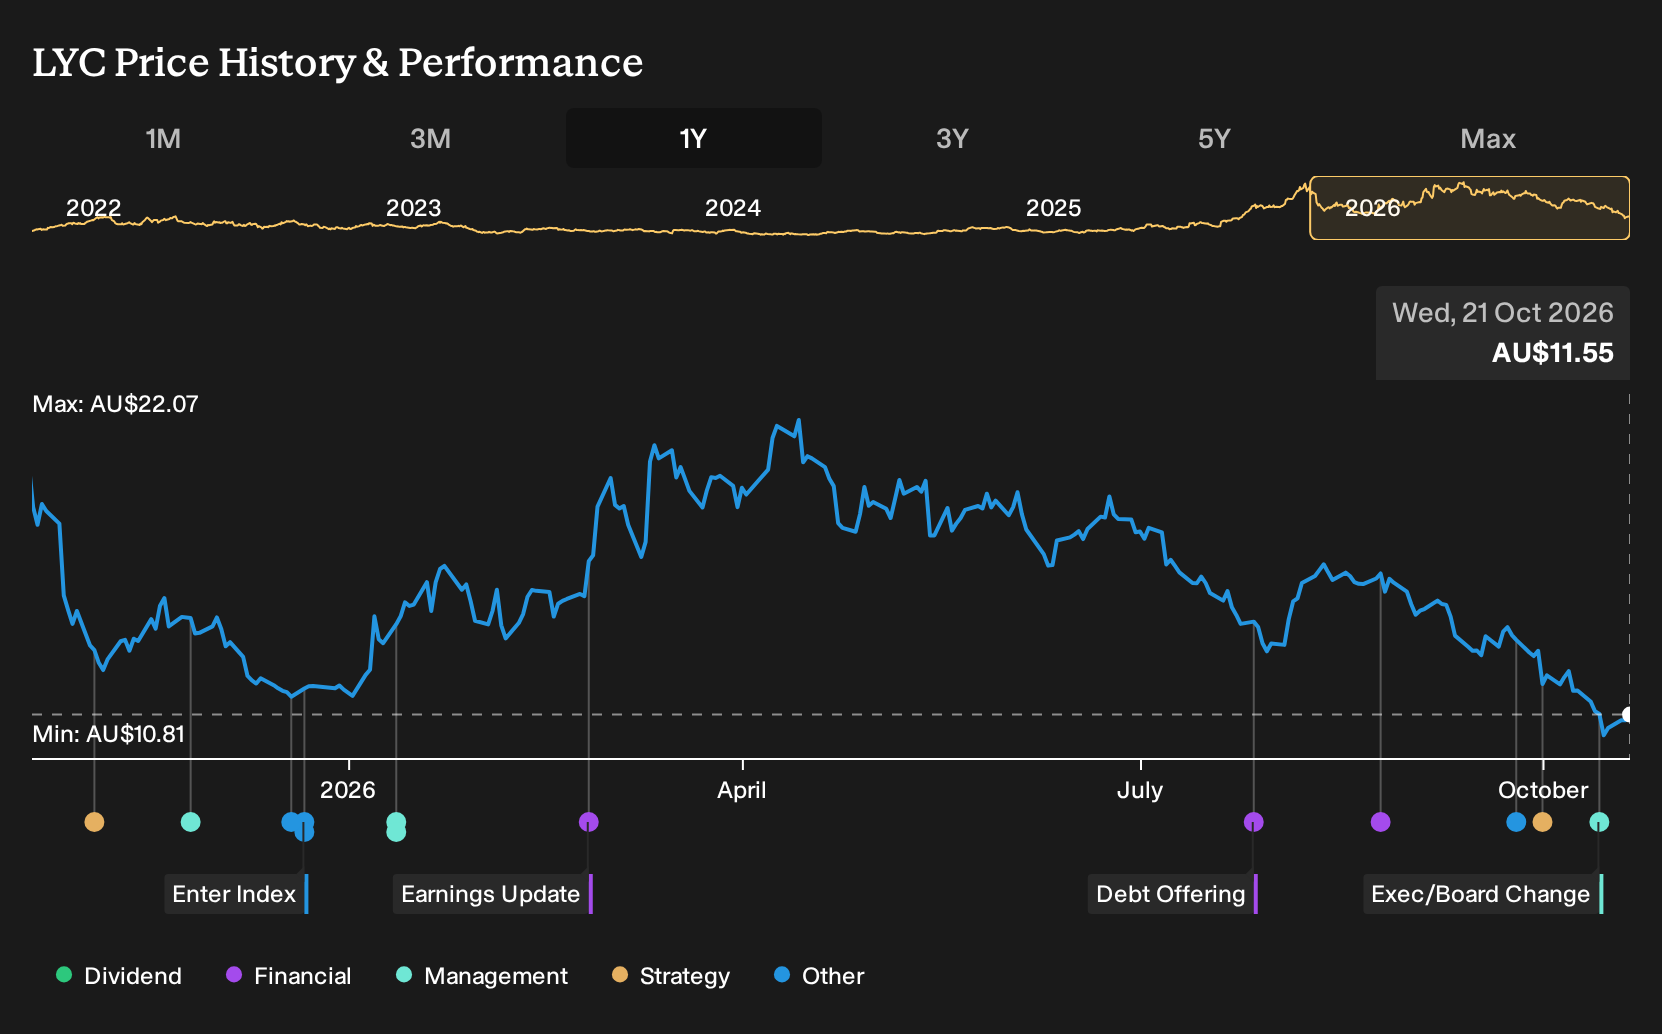
- Capital Group, which manages over A$3.6t in assets, disclosed that it had crossed the 5% substantial shareholding threshold in Lynas Rare Earths on 16 October 2026, holding 52.41 million shares across its affiliates on behalf of clients.
- This higher institutional presence reinforces Lynas Rare Earths' position as a key rare earth supplier outside China, and it supports the group's separation capability, heavier rare earth exposure and expanding downstream processing plans.
- We will now look at how Lynas Rare Earths' investment narrative could be influenced by Capital Group becoming a substantial shareholder.
Scan how institutions are positioning around rare earth supply security by comparing Lynas Rare Earths with the hand-picked 33 best rare earth metal stocks that are now shaping this critical materials theme.
Lynas Rare Earths Investment Narrative Recap
For Lynas Rare Earths, you need to believe the rare earth supply chain outside China remains important and that the Mt Weld, Kalgoorlie and Malaysia assets keep running reliably as heavier rare earth exposure and downstream processing build out. The key near term swing factor is execution on expansions without letting operating costs such as sulfuric acid and transport erode margins.
Capital Group moving above 5% and Grant Murdoch’s planned retirement both sit around that core thesis rather than changing it. The biggest near term risk still looks like regulatory or environmental approval timing in Malaysia and returns on the A$294 million heavy rare earth separation spend if commissioning or utilisation fall short.
Murdoch’s decision to step down after the November 25, 2026 AGM matters because he chaired the Audit, Risk and ESG Committee for years and sat on nominations and remuneration. That committee oversaw key topics investors watch closely in Lynas Rare Earths, including project spend discipline, environmental obligations and community impact settings across Australia and Malaysia.
With a large institutional holder now on the register, investors will likely want to see the board refresh keep those oversight muscles intact. The next phase of heavy rare earth separation and any ramp up linked to Kalgoorlie and Malaysia increases execution risk. As a result, the mix of audit, ESG and capital allocation experience on the board will remain tightly linked to how catalysts such as expansion milestones or new downstream contracts play out.
What The Current Lynas Rare Earths Forecasts Assume
Lynas Rare Earths' narrative projects A$2.5 billion revenue and A$1.1 billion earnings by 2029. This is based on analysts using a 37.5% yearly revenue growth rate and an earnings increase of about A$877.6 million from A$222.4 million today.
Uncover why Lynas Rare Earths' fair value indicates a 50% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You can look at Lynas Rare Earths through a different lens by focusing on ore quality risk rather than expansion upside. The most cautious analysts, who were expecting about A$2.2b revenue and A$950.0m earnings by 2029 before this news, paint a much tougher path. Their numbers show how sharply opinions can diverge, so it can help to compare several narratives before deciding what this fresh board change and Capital Group’s stake might mean for you.
Explore 14 other Lynas Rare Earths fair value estimates, including one that suggests as much as 18% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Lynas Rare Earths research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Lynas Rare Earths. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lynas Rare Earths' overall financial health at a glance.
Looking for more Lynas Rare Earths investment ideas?
If this Lynas Rare Earths story has sharpened your thinking and you want to cast the net wider, the Simply Wall St Screener can help you quickly scan for other opportunities that fit your preferences on risk, quality and income.
- For investors who want resilient businesses with calmer drawdowns, filter for 6 resilient stocks with low risk scores and see which candidates line up with your risk profile.
- If balance sheet strength is non negotiable for you, focus on companies in the list of solid balance sheet and fundamentals (12 results) and compare their financial footing with Lynas Rare Earths.
- When you want to broaden your watchlist beyond the usual tickers, cast a wider net across the 15 high quality undiscovered gems that pair quality fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com