


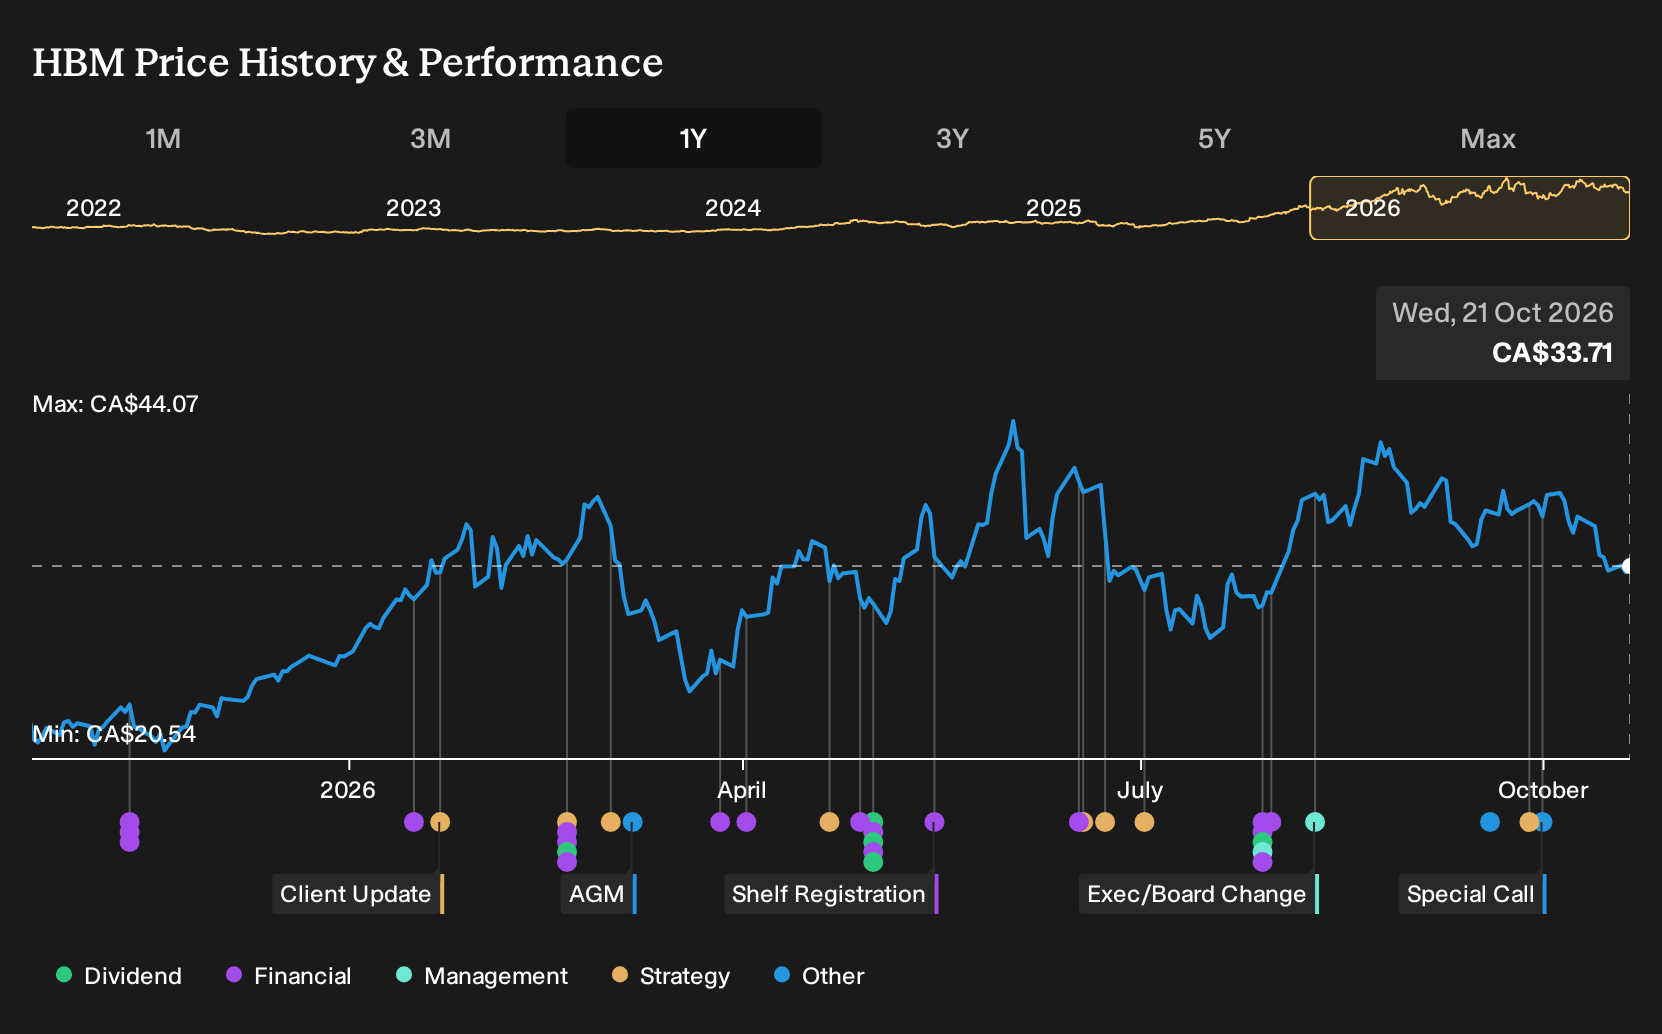
- Hudbay Minerals and Mitsubishi Corporation have approved construction of the Copper World copper project in Arizona, committing an initial US$2.07b of growth capital and targeting first production in the second half of 2029.
- The decision greatly increases Hudbay Minerals' planned capital contribution to about US$500 million, reshaping its future copper mix and long term project execution risk profile.
- We will now look at how Hudbay Minerals' investment narrative could shift with the Copper World final investment decision.
Hudbay Minerals Investment Narrative Recap
To hold Hudbay Minerals, you need to be comfortable with a mining group that leans heavily on a few big copper assets while trying to keep costs and balance sheet strength in check. The Copper World approval raises growth capital commitments, so the near term story hinges on existing operations in Manitoba, Peru, and British Columbia continuing to throw off cash.
The key short term catalyst is execution against current production and cost guidance, supported by recent positive operating and free cash flow and an improved net debt position. The largest risk remains project execution and inflation driven cost pressure at Copper World if construction spending outpaces internally generated cash and available funding.
The final investment decision on Copper World is the announcement that really matters here. It locks in a US$2.07 billion initial capital plan, with Hudbay Minerals targeting about US$500 million of its own capital into a long life US open pit that is expected to materially reshape its copper output mix and jurisdictional footprint.
For catalysts, Copper World is now directly tied to timelines, permitting progress, project level debt, and Mitsubishi funding actually arriving as planned. Execution slippage, cost creep, or permitting setbacks would feed straight back into free cash flow, leverage, and the room Hudbay has to keep investing in its existing mines while funding this large project.
Hudbay Minerals' narrative projects $3.6b revenue and $907.3m earnings by 2029. That path assumes 12.9% yearly revenue growth and an earnings increase of about $229m from $678.2m today.
Uncover why Hudbay Minerals' fair value indicates a 35% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts Copper World execution risk front and center for Hudbay Minerals. Those lowest analysts expected slower revenue progress to about $3.0b and earnings of roughly $456.8 million by 2029, far below consensus. They built in more permitting and cost setbacks. Use this new approval and conference commentary to test which story you find more convincing.
Explore 3 other Hudbay Minerals fair value estimates, including one that suggests it could be worth just CA$45.29.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Hudbay Minerals research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hudbay Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hudbay Minerals' overall financial health at a glance.
Looking for more investment ideas beyond Hudbay Minerals?
Once you have a view on Hudbay Minerals and Copper World, it can help to set it alongside a wider watchlist so you can compare risk, balance sheet strength, and income potential across a range of businesses.
- If you want potential mispriced opportunities with quality fundamentals, scan a focused 4 high quality undervalued stocks that may deserve a place on your radar.
- If capital preservation sits high on your list, filter for steadier profiles through a 8 resilient stocks with low risk scores that emphasizes resilience over excitement.
- If you care about financial strength first, build a shortlist from a list of solid balance sheet and fundamentals (7 results) to see which businesses carry less balance sheet strain.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com