


Tesla’s sharp 43% Q3 profit drop, mixed with stronger than expected free cash flow and rising paid Full Self-Driving adoption, has thrown a spotlight on companies that quietly power vehicle software and subscriptions. This tension between profit pressure and software potential creates both openings and traps for investors who move late. This article walks through 3 stocks exposed to the Tesla news and explains where the market may be mispricing that link.
The three stocks covered below are just a sample, and the full screen surfaced 36 more companies with equally compelling vehicle and mobility software narratives that are not discussed in this article. To go straight to the source and identify your own highest conviction ideas, analyze the Vehicle & Mobility Subscription Software Platforms screener.
SmartDrive (TSE:5137)
SmartDrive is a Japan-based mobility software player that builds cloud tools for fleet management, connected-vehicle data and subscription-style mobility services, using hardware such as dashcams and GPS trackers to feed its platforms. The business has no segment breakdown disclosed and carries a market value of about ¥11.7b.
SmartDrive aligns with the Tesla-driven focus on paid car software because its core products are cloud telematics and mobility data services that can underpin recurring subscriptions for fleets in Japan. The combination of strong earnings and revenue forecasts, together with a lower P/E than many software peers, supports that theme and will likely depend on how one unseen pressure plays out.
That unseen pressure is exactly what you are weighing, so review the 2 key rewards and 2 important warning signs to see what might accelerate or stall the SmartDrive subscription story.

Xperi (XPER)
Xperi brings the Vehicle & Mobility Subscription Software Platforms theme into the cabin, supplying software that runs in-car infotainment, Pay TV style guides and connected media services that can be licensed as recurring deals to automakers and entertainment providers.
Xperi generates about US$456.8 million from its Internet Telephone segment, covering Pay TV, streaming, audio and connected-car platforms, on a business valued at roughly US$252.2 million.
While Xperi is growing Media Platform exposure and reporting advertising and related revenue at more than 10% of total revenue, the advertising gross margin remains about 8% negative and management does not expect this to turn positive until entering 2027.
What happens when the balance between newer connected-car software and older media contracts shifts a little faster or slower than this plan assumes?
If that timing question matters to you, read the full narrative for Xperi to see how Xperi’s media mix could accelerate or delay value recognition.

Neusoft (SHSE:600718)
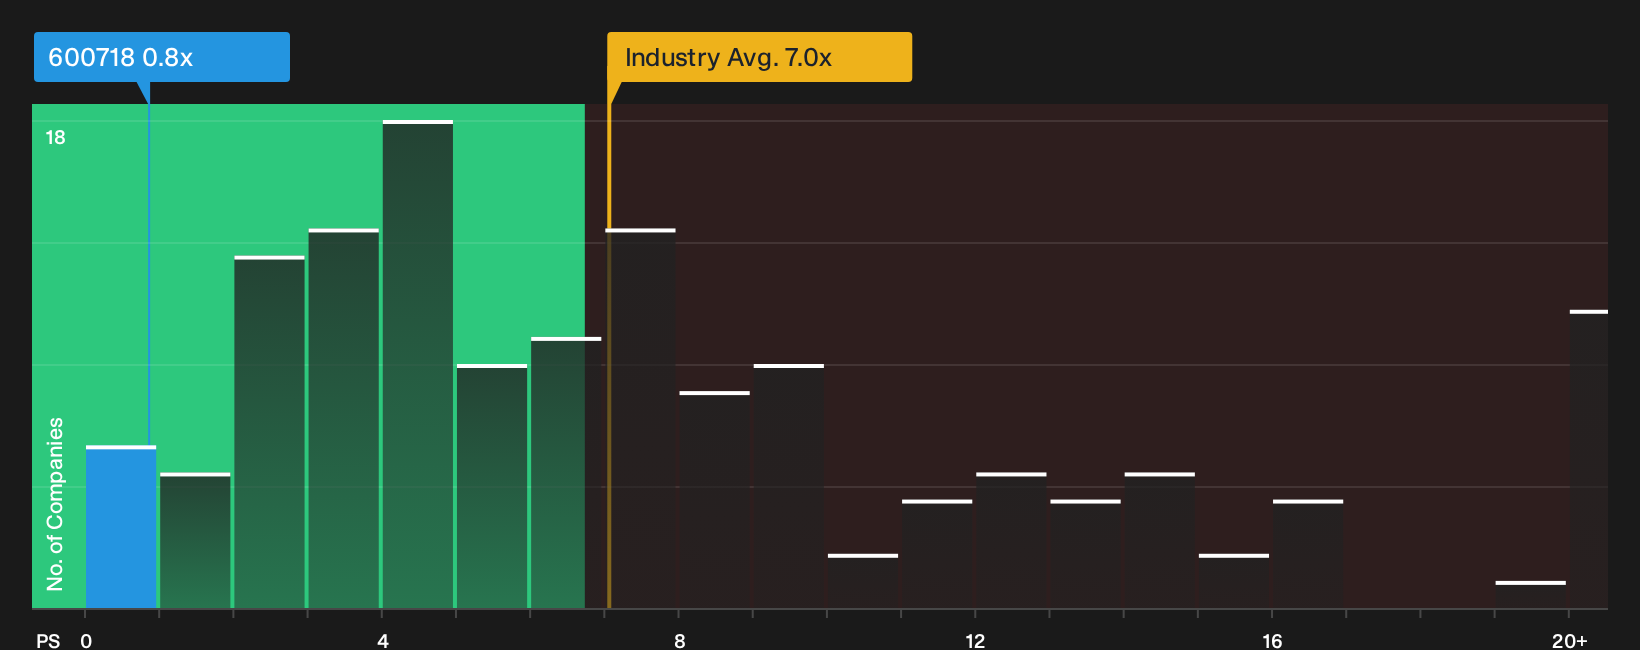
Neusoft is a broad software and IT services group that builds healthcare, enterprise and cloud tools alongside automotive platforms such as cockpit systems, navigation and intelligent vehicle clouds that fit this vehicle subscription software theme. The business is valued at about CN¥10b.
Neusoft ties into the Tesla-linked software story through its connected-car, telematics and smart mobility platforms that can be sold on recurring contracts, all inside a wider IT solutions group. The stock trades around a 0.9x P/S ratio compared with a much higher China software average. The key issue is how sensitive this picture could be to even a small shift in assumptions about the timing of future profitability.
That sensitivity is exactly the point, so review the analysis report for Neusoft and see how Neusoft’s valuation could react if the timing of profitability shifts even slightly.
Seeking Fresh Alternatives Before They Fly
Fresh ideas tend to move first, and slow movers can end up paying higher entry prices. Review these curated shortlists while the momentum is still relatively unnoticed.
- Identify cash-generating underdogs before they reach widespread attention by reviewing the 14 high quality undervalued stocks that currently combine strong balance sheets with healthy cash flows.
- Explore fast-evolving automation opportunities by tracking the 93 robotics and automation stocks quietly building momentum in factories, warehouses and next-generation hardware ecosystems.
- Review the 42 power grid technology and infrastructure stocks that may be exposed to grid upgrades, capacity expansions and reliability projects in various regions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com