


In recent weeks, global markets have experienced volatility as concerns over AI spending and inflation pressures have influenced investor sentiment, leading to a rotation from growth to more value-oriented stocks. Amid these shifting dynamics, insider ownership can be an important indicator of confidence in a company's long-term prospects, especially for growth companies navigating uncertain economic landscapes.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.8% |
| OSE Immunotherapeutics (ENXTPA:OSE) | 23% | 73.3% |
| Meitu (SEHK:1357) | 23.1% | 26.7% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Gold Road International (OB:GOLDR) | 36.7% | 89.8% |
| Fulin Precision (SZSE:300432) | 11.7% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's review some notable picks from our screened stocks.
VINA TECHLtd (KOSDAQ:A126340)
Simply Wall St Growth Rating: ★★★★★★
Overview: VINA TECH Co., Ltd. engages in the research, development, and production of supercapacitors and fuel cell materials both in South Korea and internationally, with a market cap of ₩679.57 billion.
Operations: The company's revenue is derived from its Fuel Cell segment, which generated ₩7.10 billion, and its Energy Storage Device segment, contributing ₩99.45 billion.
Insider Ownership: 31.7%
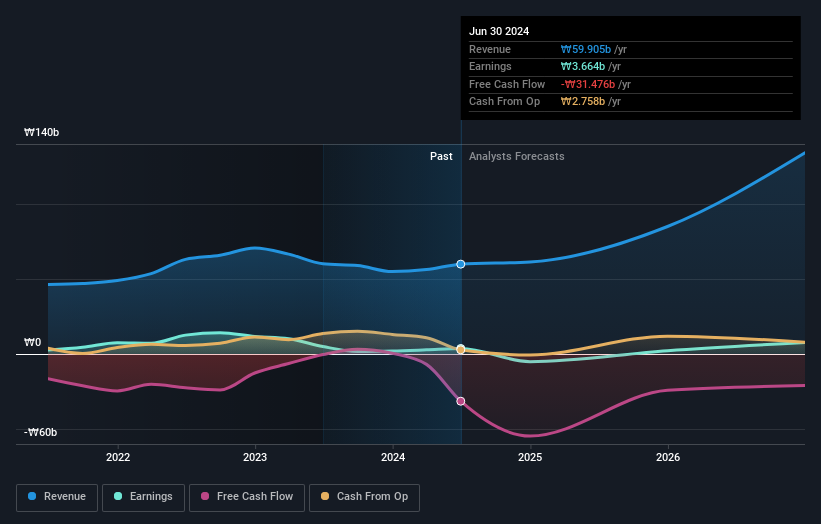
VINA TECH Ltd. is positioned for significant growth, with revenue expected to increase by 49% annually, outpacing the KR market's 13.6%. Despite high share price volatility and interest payments not being well-covered by earnings, the company trades at a substantial discount of 40.1% below its estimated fair value. Recent private placements raised KRW 29 billion through convertible bonds, indicating strong investor confidence despite no recent insider trading activity. Profitability is anticipated within three years, with projected earnings growth of 96.78% per year and a high future return on equity of 22.7%.
- Click to explore a detailed breakdown of our findings in VINA TECHLtd's earnings growth report.
- According our valuation report, there's an indication that VINA TECHLtd's share price might be on the expensive side.
Hyosung Heavy Industries (KOSE:A298040)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Hyosung Heavy Industries Corporation manufactures and sells heavy electrical equipment in South Korea, with a market cap of ₩18.15 trillion.
Operations: The company's revenue is primarily derived from its Heavy Industry segment, which generated ₩5.91 billion, and its Construction segment, which contributed ₩2.07 billion.
Insider Ownership: 11.5%
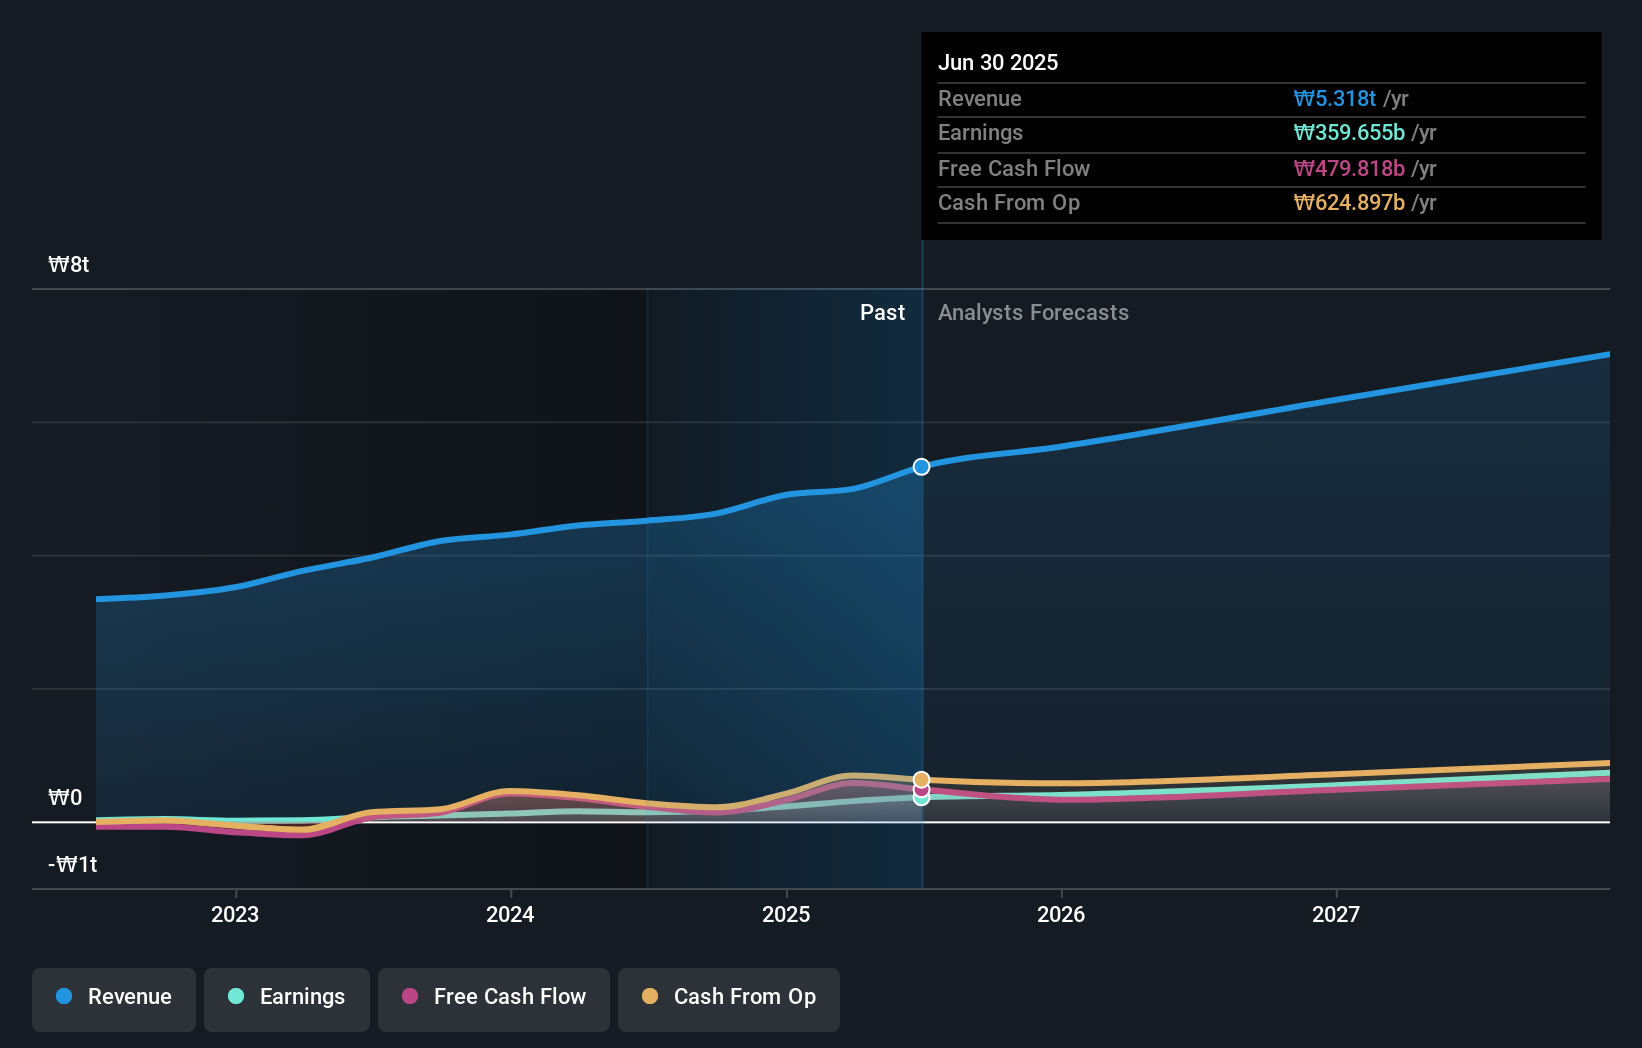
Hyosung Heavy Industries is strategically positioned in the U.S. power infrastructure market, securing recent contracts worth US$287 million for ultra-high-voltage transformers with major tech firms. This reinforces its leadership in the 765kV transformer sector and supports its expansion into AI data center markets. Despite share price volatility, earnings are forecast to grow significantly at 32% annually, surpassing market averages. Trading slightly below fair value, it shows robust growth potential without substantial recent insider trading activity.
- Dive into the specifics of Hyosung Heavy Industries here with our thorough growth forecast report.
- Our valuation report unveils the possibility Hyosung Heavy Industries' shares may be trading at a premium.
Phison Electronics (TPEX:8299)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Phison Electronics Corp. designs, manufactures, and sells flash memory controllers and peripheral system applications globally, with a market cap of NT$426.85 billion.
Operations: The company's revenue primarily comes from its Flash Memory Control Chip Design segment, which generated NT$149.79 billion.
Insider Ownership: 10.2%
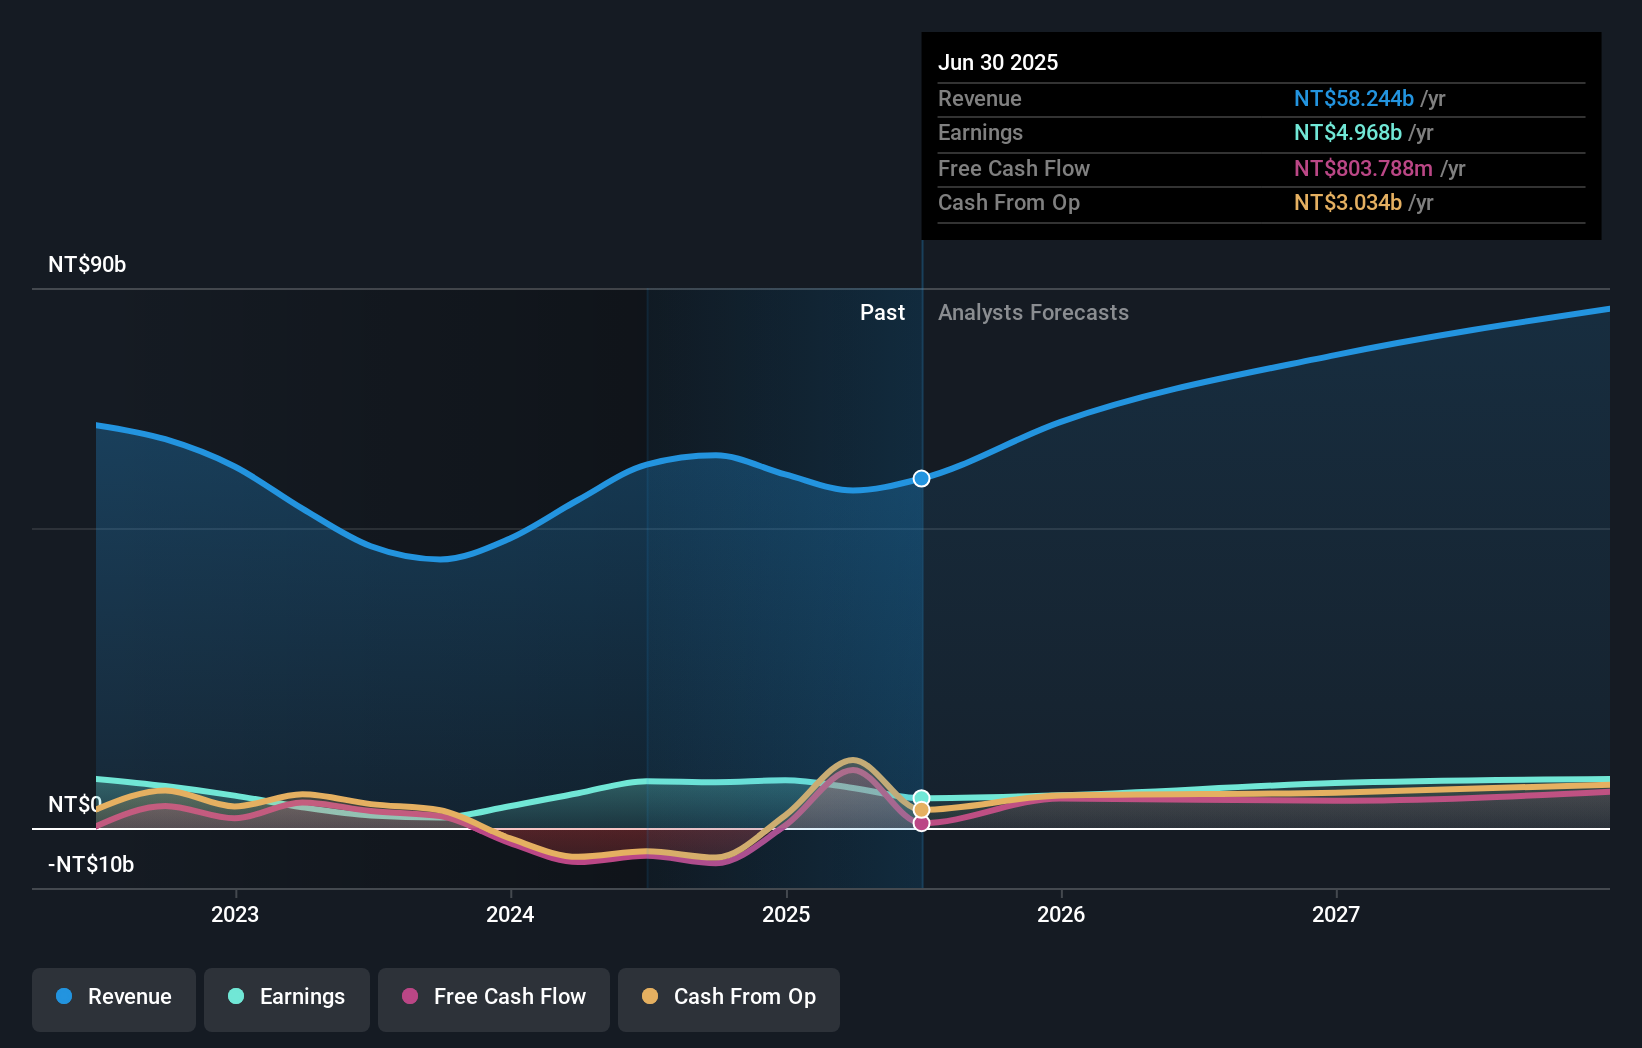
Phison Electronics is expanding its European operations, appointing seasoned leaders to drive regional growth and enhance market presence. Despite recent share price volatility, the company demonstrates high-quality earnings with a significant past year profit increase. Trading at a good relative value, Phison's revenue is forecast to grow robustly at 29.4% annually, outpacing the market. While insider trading activity is minimal recently, strong leadership and strategic expansion highlight its growth potential.
- Take a closer look at Phison Electronics' potential here in our earnings growth report.
- Our comprehensive valuation report raises the possibility that Phison Electronics is priced lower than what may be justified by its financials.
Taking Advantage
- Unlock more gems! Our Fast Growing Global Companies With High Insider Ownership screener has unearthed 725 more companies for you to explore.Click here to unveil our expertly curated list of 728 Fast Growing Global Companies With High Insider Ownership.
- Seeking Other Investments? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com