


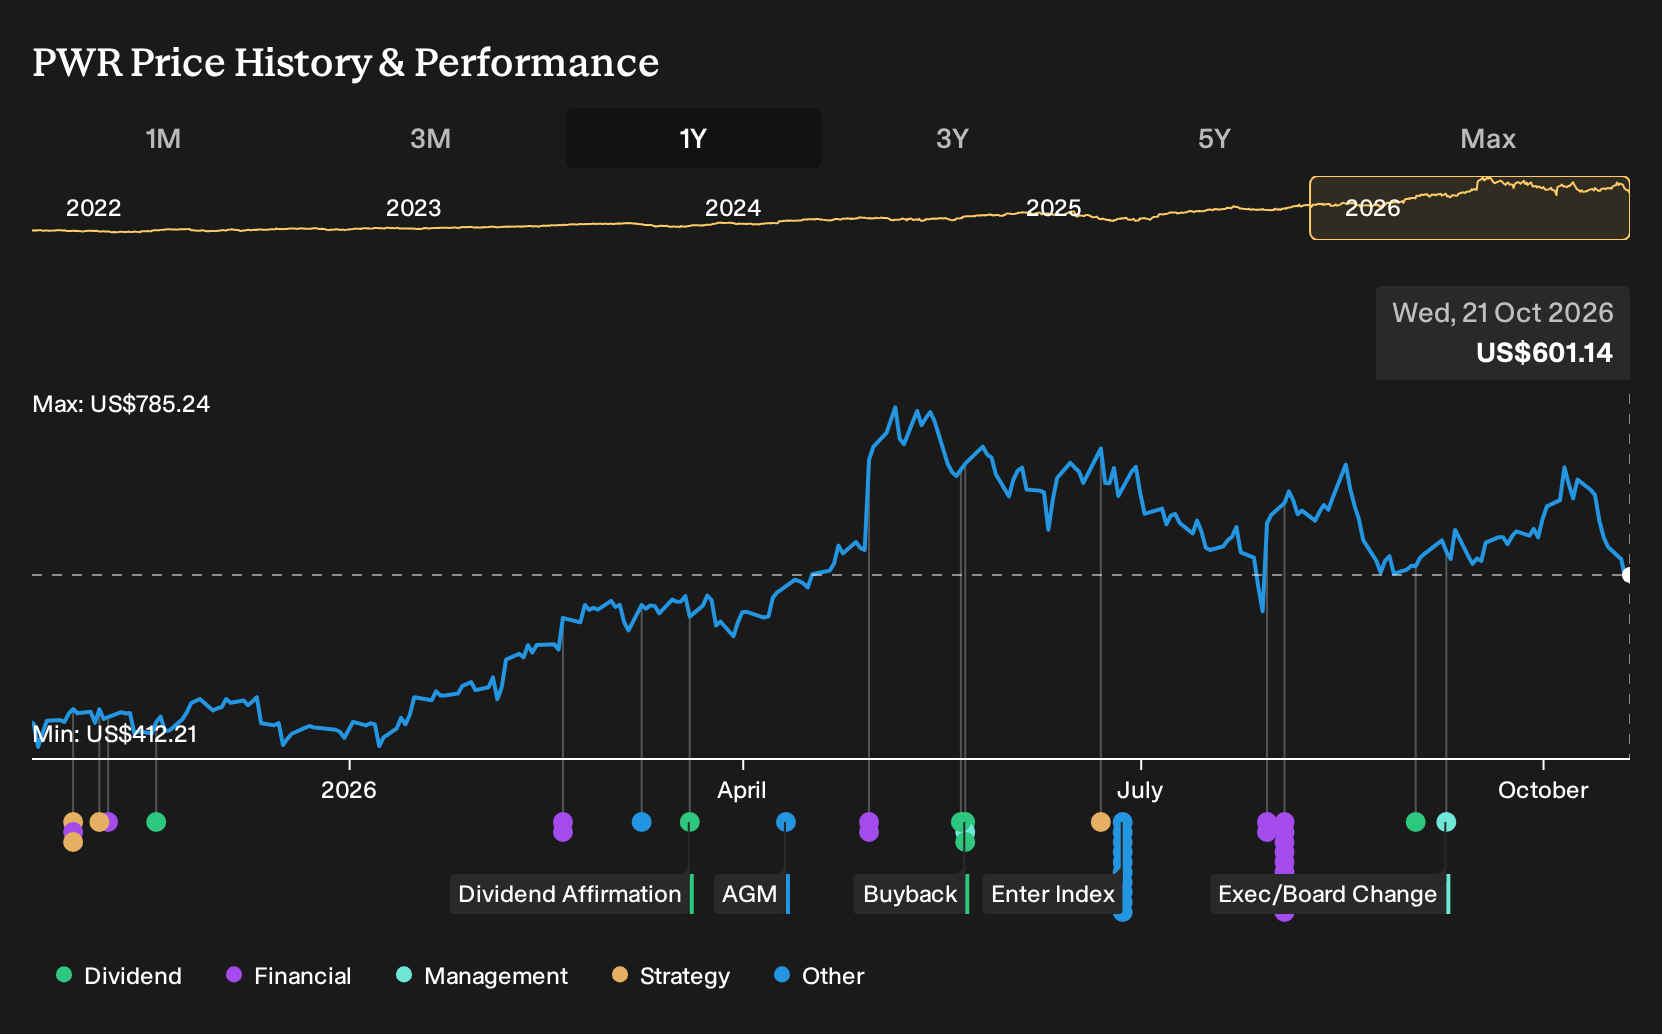
If you had bought Quanta Services on 21 October 2025 and simply held on, the outcome would look very different today. Holding Quanta Services over the past year would have returned 45.9%, including dividends. That result invites a tougher question. At the time, should an investor have leaned into the bullish grid modernization and renewables story, or given more weight to warnings about rising competition, labor strain and project concentration risk?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Quanta Services has already moved. Pinpoint other ways to investigate the theme among 42 power grid technology and infrastructure stocks.
The Argument You Would Have Been Weighing Up On Quanta Services
The shares cost US$437 at the start of the period, so any investor in Quanta Services first had to decide which story about the future felt more realistic.
The bullish narrative put fair value at US$490, which is 12% above the start price. It leaned on a long grid and renewables buildout, with Quanta expected to capture multi year projects that supported higher margins and larger backlogs.
The bearish view set fair value at US$248, which is 43% below the start price. It focused on rising competition, labor shortages and project concentration that could compress profitability and increase earnings volatility.
What The Results Changed In The Quanta Services Story
Record Q2 2026 figures gave Quanta Services investors fresh data. Revenue reached US$9.56b versus US$6.77b a year earlier, and net income rose from US$229.25m to US$451.38m. Net margin moved from 3.4% to 4.7%, lining up more with the bullish view on scale and profitability. Heavy insider selling and recurring valuation worries pulled in the opposite direction, so the evidence cut both ways.
The decision back in October 2025 really hinged on whether higher grid and AI demand would show up in backlog, revenue and margin together. When you assess another infrastructure stock, track that trio across several reports and test any upbeat story against the actual net margin line.
What Today's Quanta Services Price Already Assumes
Quanta Services now trades at US$601. The selected Narrative’s Fair Value sits below that level, so its author sees the recent one year 45.9% gain as already baking in a lot of execution success.
The crux is whether you think Quanta can turn a record backlog, acquisitions and new manufacturing capacity into durable earnings. A buyer today has to weigh that assumption against the risk that rising fixed costs, rapid hiring and complex projects blunt the payoff.
"The numbers imply the share price already embeds strong execution on multi decade power and data center demand, successful integration of over $1.2b of recent deals, and delivery on management’s 15 to 20% adjusted EPS growth framework, so there is limited room for disappointment if any of these pillars weaken."
One Narrative disagrees with today's price. → See where this Narrative says Quanta Services should trade
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 23% below our estimate - sells grid diagnostic tools utilities adopt to harden networks during electrification upgrades.
- Company 2 - 40% below our estimate - expands a premium tea chain as membership data nudges customers toward higher margin drink choices.
- Company 3 - 30% below our estimate - supplies full-stack AI computing platforms as large cloud clients commit to long-term accelerator capacity.
Those are three of them. See all 33 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com