


Salesforce has ridden a mix of AI deals and large customer wins into the spotlight again, yet the real question for investors is whether its current share price lines up with the earnings power behind it.
- Over the past 3 years the stock has returned about 25%, which puts real weight on the idea that Salesforce’s profit engine can justify where the valuation now sits.
- Recent moves to buy Braze for about US$5.66b and fold AI analytics from Loops into Tableau can reshape expectations for future earnings, margins, and the timing of cash flows as Salesforce leans harder into AI driven customer engagement.
- Your read on Salesforce is one view; the desks covering it have another. See what analysts think Salesforce's shares could be worth.
The stock’s next move may depend on whether Salesforce’s current earnings are strong enough to support today’s share price.
If you want to stress test this same earnings question beyond Salesforce, scan a wider field of AI focused software stocks using the 38 AI small caps.
Is Salesforce Still Cheap on Earnings?
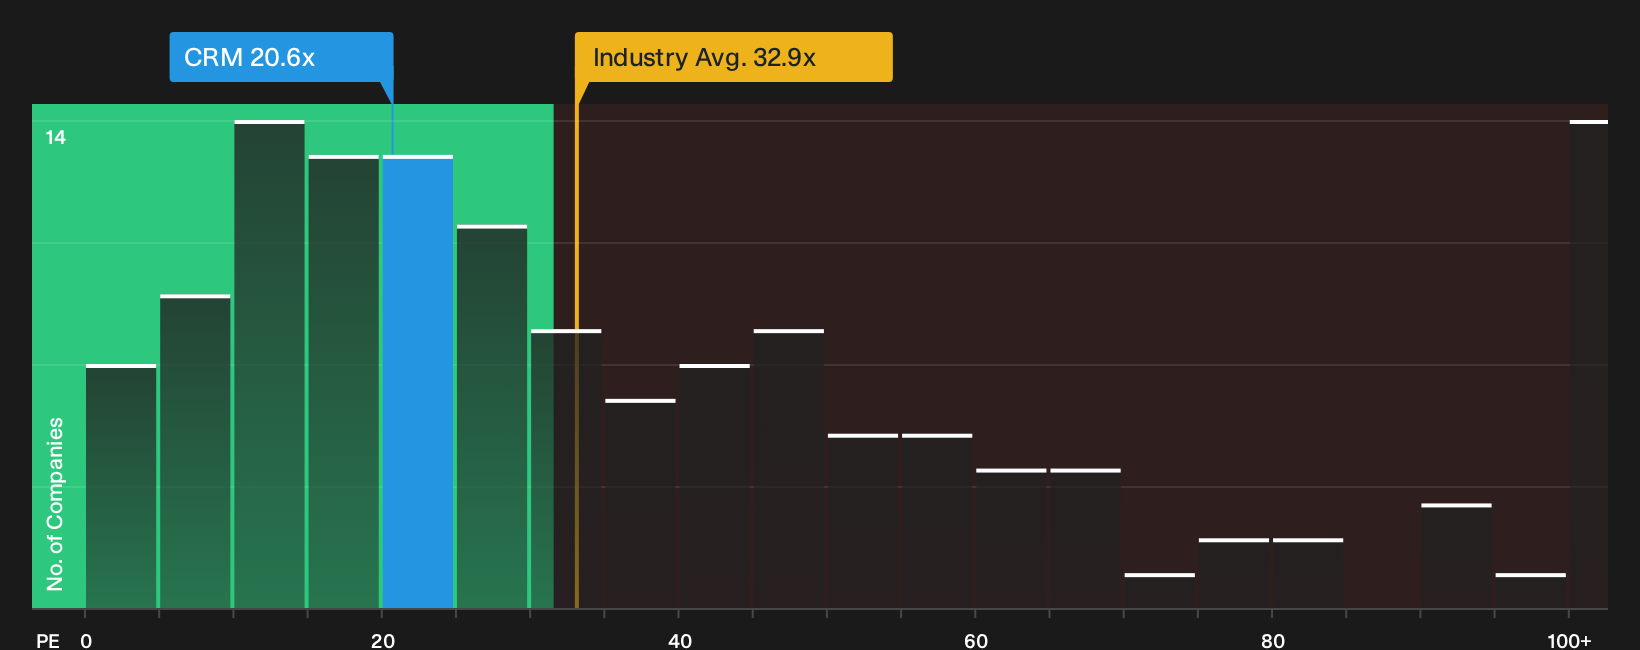
P/E is a clean yardstick here because Salesforce is generating earnings and most investors still anchor expectations to what they pay for each dollar of profit. On that score, the stock trades at about 20.6x trailing earnings, which is below the broader software industry on roughly 32.9x and also under a peer set closer to 44.7x.
The in house fair multiple estimate, which folds in Salesforce’s margins, growth profile, scale and risks, points to a higher ratio than where the shares change hands today. On that framework, the current P/E screens as undervalued. Despite the Braze deal and other AI news keeping attention on the story, the market price still implies a discount to what similar software groups command on earnings. Explore the numbers behind Salesforce's P/E valuation.
The Salesforce Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Salesforce’s P/E puzzle leaves off and outline potential future paths for growth, margins and earnings that would need to occur for the stock to be worth materially more or less than it is today on the market. Each scenario links its figures to a concrete view of where Salesforce’s expansion, profitability and risks may go next, which you can then revisit as fresh information becomes available.
Salesforce attracts two very different storylines, with some community members seeing meaningful upside and others warning about AI driven risks.
Bull case: 18% undervalued
"The new thesis is more interesting: Salesforce may sell governed work."
Discover why this Narrative puts Salesforce at 18% undervalued.
Bear case: 24% overvalued
"The current numbers around revenue guidance, free cash flow, AI adoption, and long term targets imply that Salesforce's share price already reflects a successful AI agent platform..."
Explore why this Narrative puts Salesforce at 24% overvalued.
Salesforce’s price tag raises one more crucial question
All the work on earnings and scenarios still leaves one loose end, because Simply Wall St’s broader checks have picked up specific areas of concern that investors may want to weigh before leaning on the current valuation. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com