


James Hardie Industries (ASX:JHX) has rolled out its new masterbrand platform, The Home of Resilient Beauty™, which unites its exterior and outdoor living labels around durable, fire-resistant building products and disaster-focused storytelling.
Recent trading has been mixed for James Hardie Industries, with the share price at A$36.85 after a 1-day share price decline of 1.47% and a 7-day share price return of 3.86%. The year-to-date share price return of 19.68% contrasts with a 1-year total shareholder return of 10.30% and a 5-year total shareholder return that has fallen 27.38%, suggesting near term momentum alongside longer term disappointment for many holders.
Scan resilient building and materials opportunities like James Hardie Industries by reviewing our hand picked 6 resilient stocks with low risk scores that focus on durable businesses with steadier risk profiles.
After a near term rebound but weaker longer term record, the question around James Hardie Industries now is simple: does the current valuation still leave enough upside to justify the risk buyers take from here?
Most Popular Narrative: 17% Undervalued
On Simply Wall St, the most followed narrative pegs James Hardie Industries' fair value at A$44.43, above the A$36.85 last close. This frames the current price as a discount that still needs strong execution to close.
The recent acquisition and integration of AZEK has more than doubled James Hardie's addressable market and expanded its product offering into high-growth outdoor living categories, setting the stage for sustained top-line acceleration and double-digit revenue growth across North America over the coming years.
The combined company is aggressively targeting large-scale material conversion, with initiatives to capture market share from traditional materials (brick, stucco, wood) and underpenetrated regions, enhanced by exclusive homebuilder partnerships and loyalty programs, all of which are likely to boost both sales volumes and improved product mix.
See why 40 investors see James Hardie Industries as 17% undervalued.
Result: Fair Value of A$44.43 (UNDERVALUED)
Still, softer siding demand checks and the execution risk around integrating AZEK could quickly challenge the bullish James Hardie Industries valuation story.
Find out about the key risks to this James Hardie Industries narrative.
Another View On James Hardie Industries Valuation
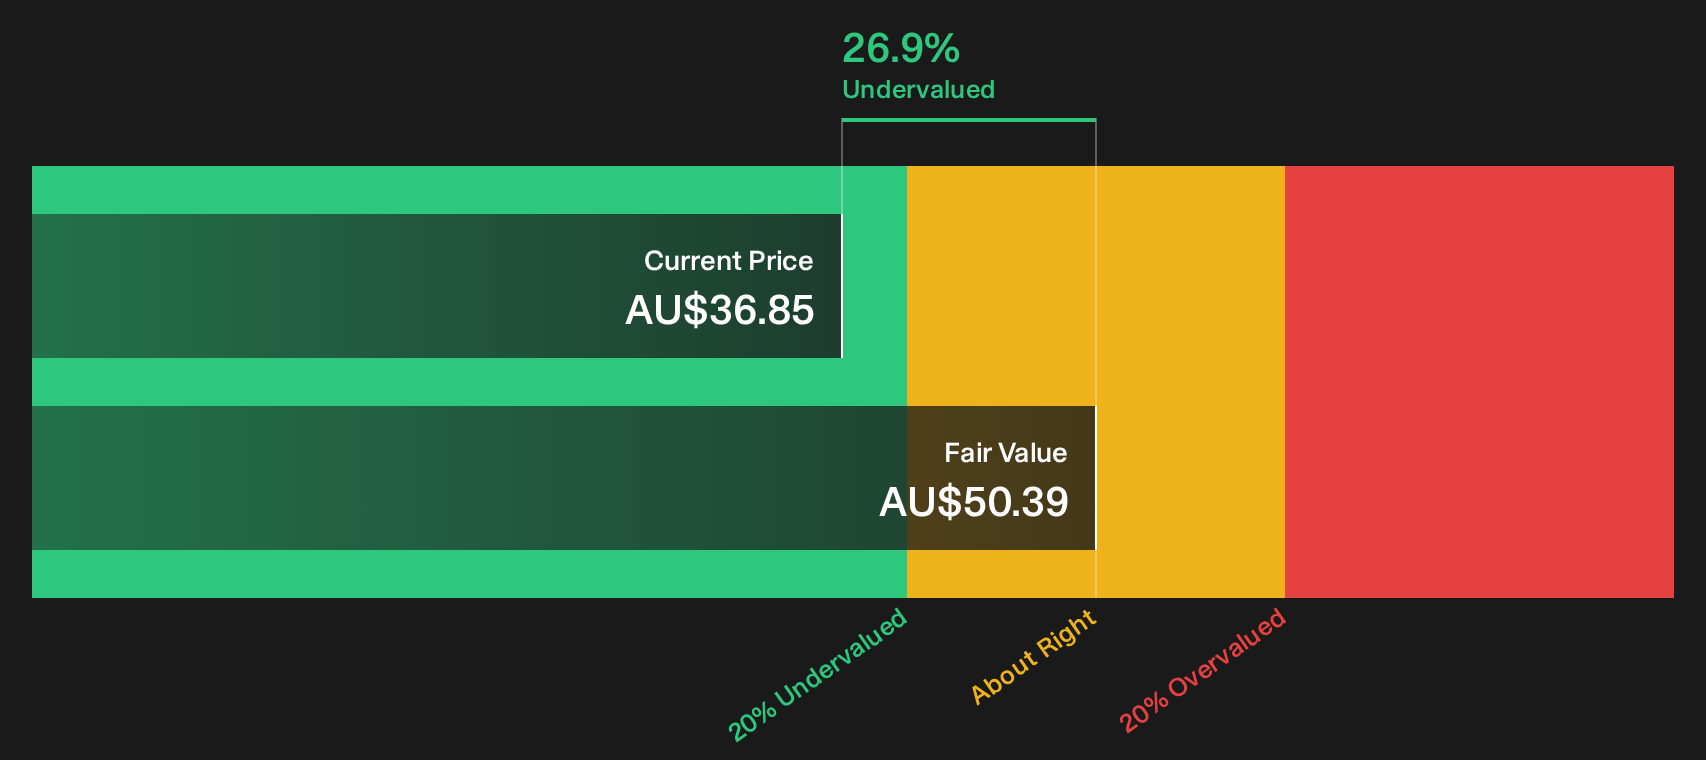
The first takeaway for James Hardie Industries is that it screens as undervalued on fair value work, with the shares trading 26.9% below an estimated A$50.39 future cash flow value on the Simply Wall St DCF model. That is a wide gap. The real question is how much weight you want to give that single framework.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on James Hardie Industries so far. If you want to move quickly and make your own call, start by weighing its 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond James Hardie Industries?
If James Hardie Industries is already on your radar, do not stop there. Broaden your watchlist now so you are not scrambling when the next move appears.
- Target potential mispricing by scanning a curated 4 high quality undervalued stocks that zero in on companies where fundamentals and share prices do not fully line up.
- Strengthen your income focus by reviewing a hand picked 5 dividend fortresses built around businesses offering higher yields with an eye on stability.
- Prioritise resilience by checking a list of solid balance sheet and fundamentals (12 results) built to spotlight companies with sturdier financial footing and cleaner fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com