


- BancFirst reported third quarter 2026 net income of US$67.25 million, up from US$62.65 million a year earlier, with basic EPS from continuing operations at US$2.
- Year to date, BancFirst's net income reached US$196.94 million with diluted EPS from continuing operations at US$5.78, which highlights how earnings power across the first nine months is tracking above the prior year.
- This article examines how BancFirst's investment narrative aligns with higher third quarter earnings and considers potential implications for long term returns.
Compare BancFirst's latest earnings momentum with other regional financials by screening for peers that pair resilient profitability with balance sheet strength using our curated list of solid balance sheet and fundamentals (25 results)
BancFirst Investment Narrative Recap
BancFirst appeals to shareholders who back a steady regional banking model with strong capital and a sizeable fee income stream. To stay comfortable, you need confidence that Tulsa acquisitions, non interest revenue and underwriting discipline can offset slowing net interest income and efficiency headwinds. The latest quarter shows earnings power holding up, but it does not fundamentally change that thesis.
The near term swing factor is whether management can keep costs contained while integrating acquired branches and protecting credit quality. The main risk is that revenue growth and efficiency drift below expectations, which would pressure margins and make the current premium P/E harder for the market to justify.
The fresh earnings release for the September 2026 quarter is the key update. BancFirst reported net income of US$67.25 million for the quarter and US$196.94 million for the first nine months, with diluted EPS from continuing operations at US$1.97 and US$5.78 respectively. Those figures mark another period where profitability remains solid against prior results.
This matters for your catalyst checklist because the whole story around Tulsa consolidation, fee income breadth and strong capital relies on earnings staying resilient while growth is described as moderate. Consistent EPS from continuing operations gives management room to keep investing in integrations and technology. Any loss of that earnings cushion would make efficiency pressures and valuation risk far more visible.
BancFirst's narrative projects US$874.9 million revenue and US$286.7 million earnings by 2029. This assumes 7.0% yearly revenue growth and an earnings increase of about US$34.9 million from US$251.8 million today.
Discover how BancFirst's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
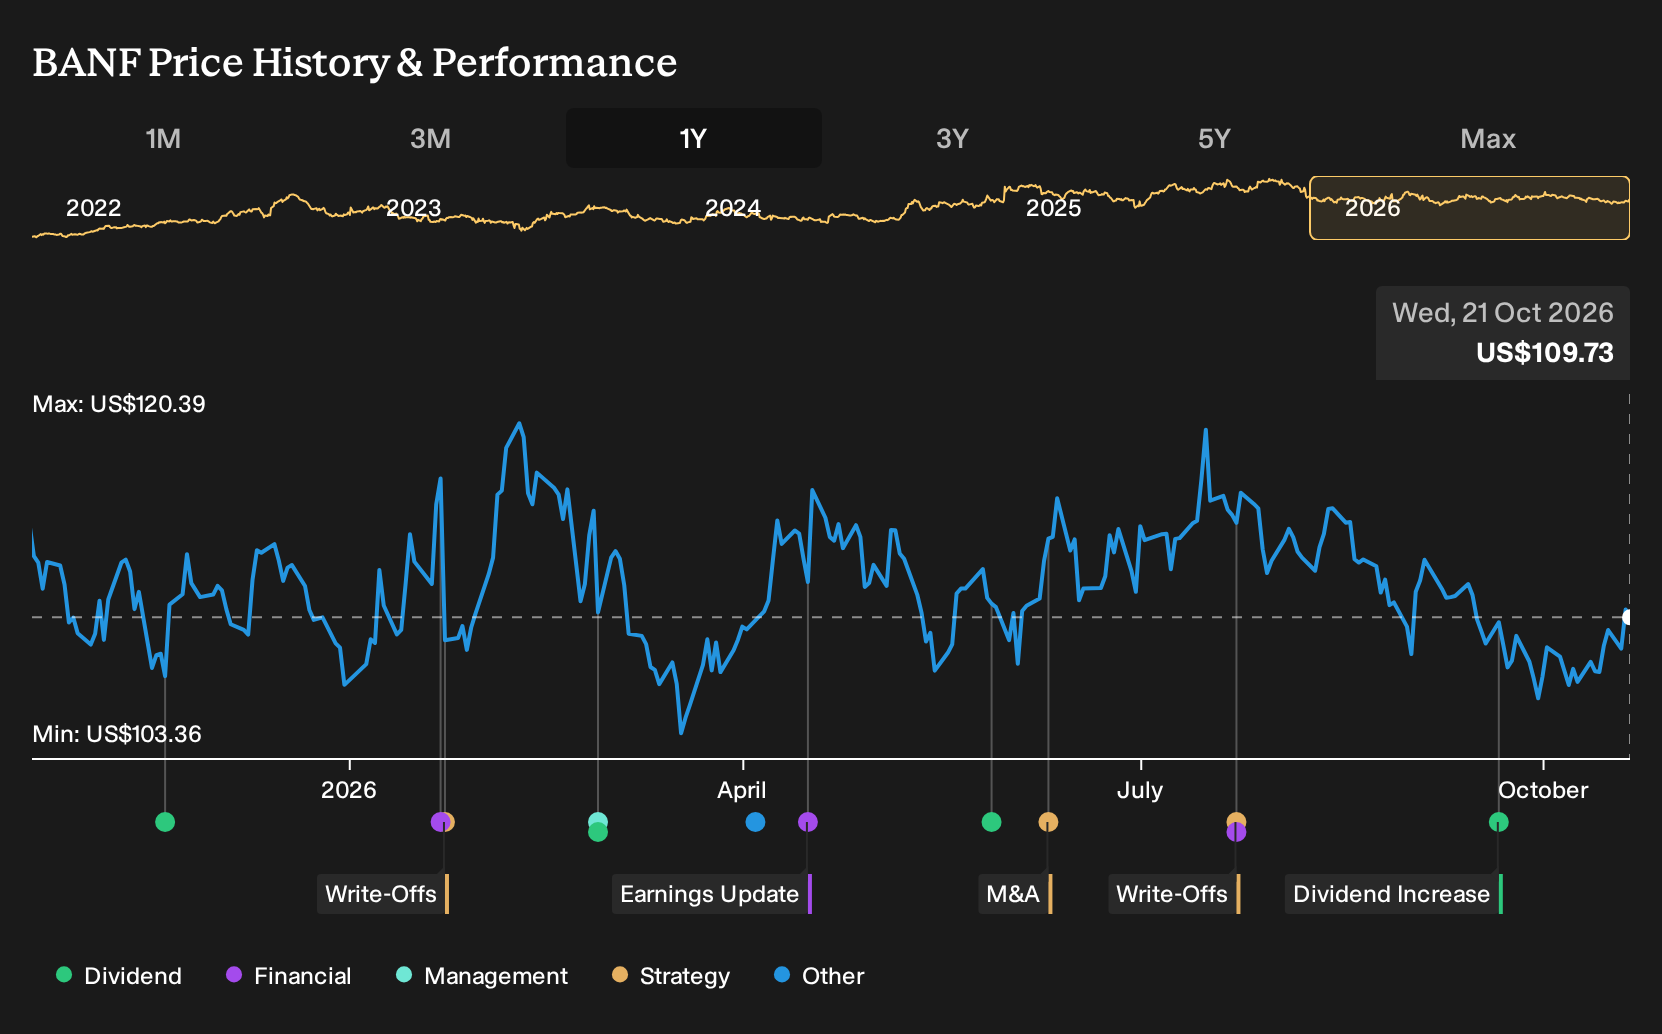
Only two fair value estimates from the Simply Wall St Community cluster tightly between US$124 and about US$124.33, so even a small gap feels meaningful. You are seeing just a couple of retail opinions, not a full market poll. Set that against BancFirst’s muted revenue growth commentary and recent share price pullback, and it becomes clear that wider community views could differ sharply. This is exactly why it helps to compare several alternative angles before leaning on any single figure.
Explore another BancFirst fair value estimate, including one that suggests it could be worth just $124.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your BancFirst research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BancFirst. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BancFirst's overall financial health at a glance.
Looking For More BancFirst Investment Ideas?
Once you have a view on BancFirst, it often helps to widen the lens and compare it with other opportunities that fit different portfolio roles. The Simply Wall St Screener lets you scan for shares that match clear financial traits, then filter down to a shortlist that fits your own return and risk goals.
- For investors who care most about quality at a sensible entry point, start with companies flagged as having a potential value gap through our 33 high quality undervalued stocks.
- If your priority is resilience through the cycle, focus on businesses that pair sturdy finances with measured risk profiles using the 31 resilient stocks with low risk scores.
- When you want to hunt for under-followed opportunities rather than widely discussed blue chips, search through the 21 high quality undiscovered gems and see which fundamentals catch your eye.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com