


Over the last 7 days, the United States market has remained flat, yet over the past 12 months, it has risen by an impressive 13%, with earnings forecasted to grow by 17% annually. In this environment of steady growth and optimism, identifying stocks that are estimated to be trading below their intrinsic value can offer potential opportunities for investors looking to capitalize on future gains.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| MYR Group (MYRG) | $275.21 | $530.08 | 48.1% |
| Jones Lang LaSalle (JLL) | $306.05 | $610.20 | 49.8% |
| Halliburton (HAL) | $33.99 | $65.64 | 48.2% |
| Futu Holdings (FUTU) | $105.03 | $207.05 | 49.3% |
| FB Financial (FBK) | $52.10 | $103.32 | 49.6% |
| Civista Bancshares (CIVB) | $26.75 | $53.30 | 49.8% |
| Bread Financial Holdings (BFH) | $108.63 | $214.94 | 49.5% |
| Best Buy (BBY) | $94.12 | $187.18 | 49.7% |
| Artisan Partners Asset Management (APAM) | $33.13 | $64.78 | 48.9% |
| Addus HomeCare (ADUS) | $117.95 | $226.18 | 47.9% |
Here's a peek at a few of the choices from the screener.
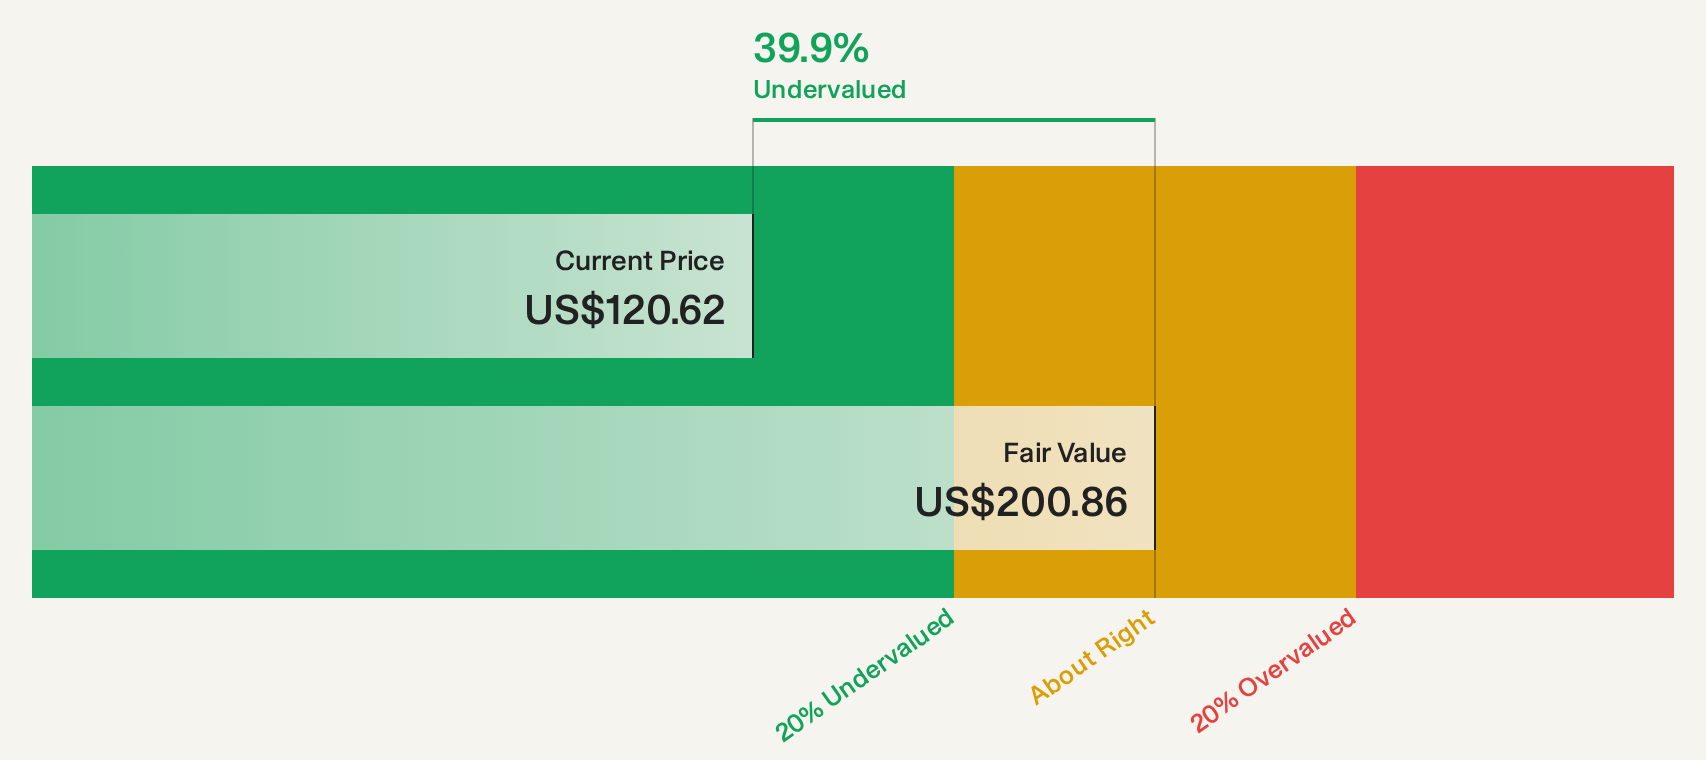
Citigroup (C)
Overview: Citigroup Inc. is a diversified financial services holding company offering a range of financial products and services to consumers, corporations, governments, and institutions, with a market cap of approximately $202.78 billion.
Operations: Citigroup's revenue is primarily derived from its Wealth segment ($9.47 billion), Banking ($8.38 billion), Markets ($24.43 billion), and Services ($23.52 billion).
Estimated Discount To Fair Value: 38.3%
Citigroup is trading at a significant discount to its estimated future cash flow value, with the stock price 38.3% below fair value estimates. Despite slower revenue growth forecasts compared to the broader US market, Citigroup's recent earnings report showed substantial profit growth, with net income reaching US$5.25 billion in Q3 2026. The company maintains a reliable dividend and continues expanding its fixed-income offerings and digital initiatives, potentially enhancing long-term cash flow stability.
- Our expertly prepared growth report on Citigroup implies its future financial outlook may be stronger than recent results.
- Click to explore a detailed breakdown of our findings in Citigroup's balance sheet health report.
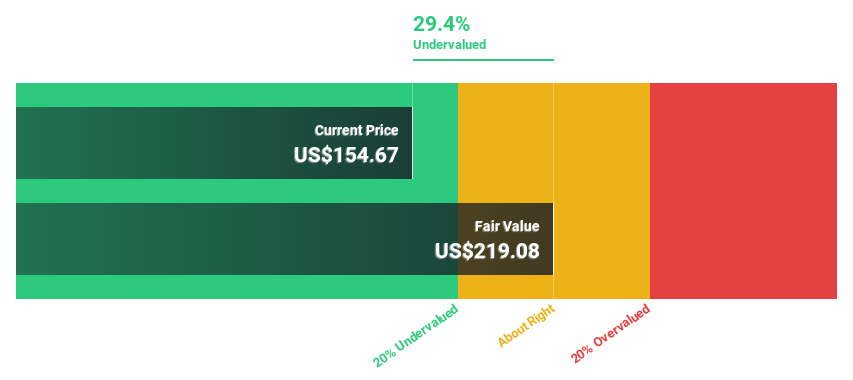
Capital One Financial (COF)
Overview: Capital One Financial Corporation is a financial services holding company that provides a range of financial products and services in the United States, Canada, and the United Kingdom, with a market cap of approximately $123.65 billion.
Operations: Capital One Financial Corporation generates revenue through a diverse array of financial products and services offered across the United States, Canada, and the United Kingdom.
Estimated Discount To Fair Value: 37.5%
Capital One Financial is trading at a significant discount to its estimated future cash flow value, with the stock price 37.5% below fair value estimates. Despite slower revenue growth forecasts compared to the broader US market, recent earnings showed strong profit growth, with net income reaching US$3.54 billion in Q3 2026. The company has no substantial insider selling and continues expanding its fixed-income offerings, potentially enhancing long-term cash flow stability despite an unstable dividend track record.
- Our earnings growth report unveils the potential for significant increases in Capital One Financial's future results.
- Delve into the full analysis health report here for a deeper understanding of Capital One Financial.
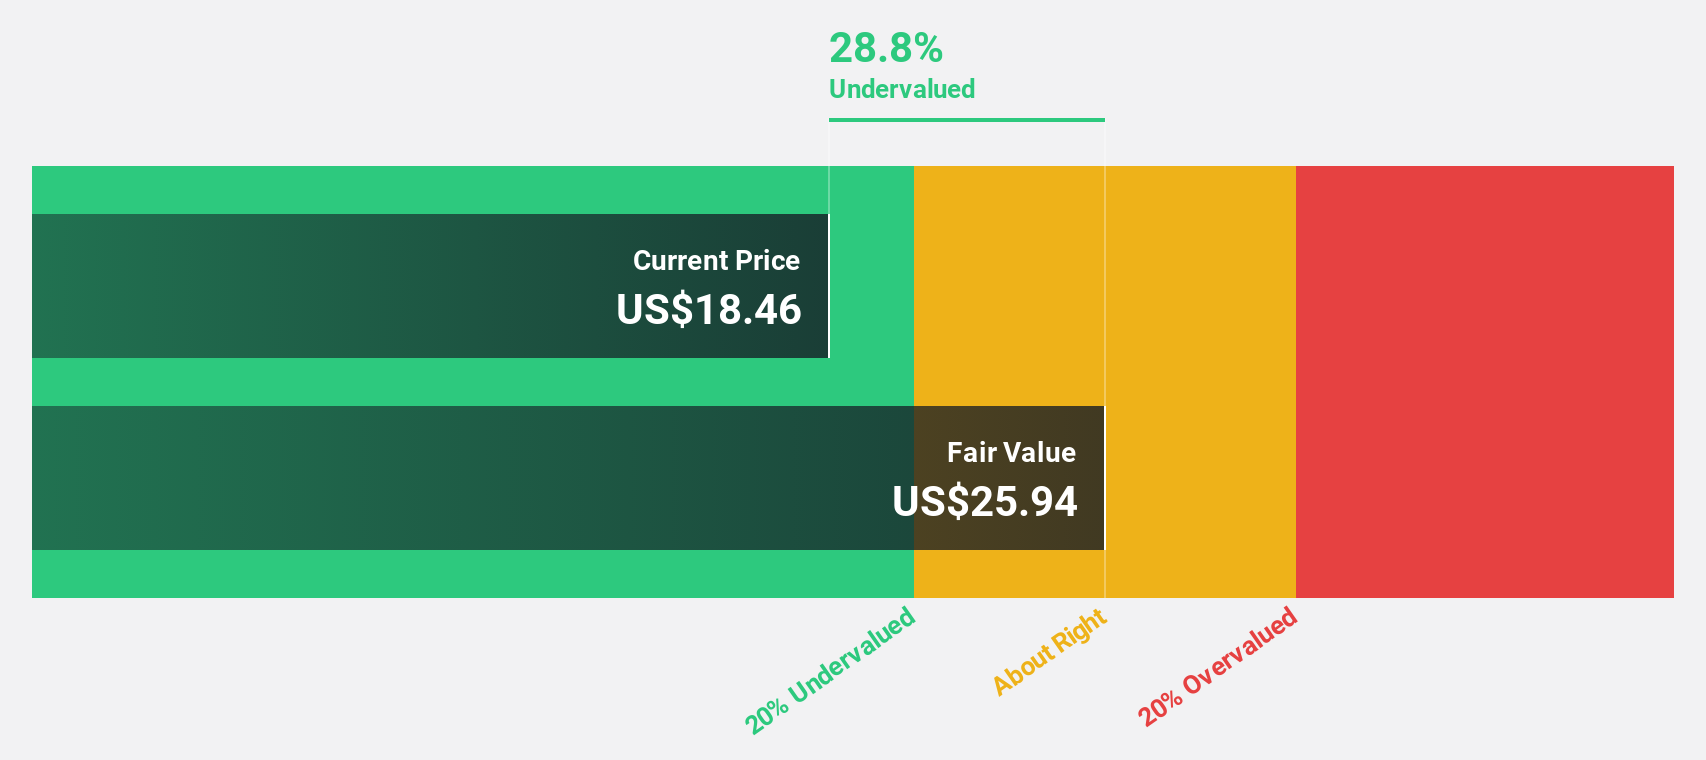
KeyCorp (KEY)
Overview: KeyCorp, with a market cap of approximately $22.21 billion, operates as the holding company for KeyBank National Association, offering a range of retail and commercial banking products and services in the United States.
Operations: KeyBank National Association generates revenue through diverse retail and commercial banking products and services across the United States.
Estimated Discount To Fair Value: 46.1%
KeyCorp is trading at a substantial discount to its estimated future cash flow value, with the stock price 46.1% below fair value estimates. The company reported strong Q3 2026 earnings, with net income rising to US$579 million from US$489 million a year ago. Despite slightly slower revenue growth forecasts than the broader market, KeyCorp's consistent dividend and recent share buybacks underscore its commitment to shareholder returns while optimizing capital structure.
- The growth report we've compiled suggests that KeyCorp's future prospects could be on the up.
- Get an in-depth perspective on KeyCorp's balance sheet by reading our health report here.
Summing It All Up
- Dive into all 95 of the Undervalued US Stocks Based On Cash Flows we have identified here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com