


GE Vernova (GEV) will release its third-quarter 2026 financial results on Wednesday, Oct. 28. Robust worldwide demand for its Power and Electrification offerings, coupled with a supportive pricing environment, could drive strong year-over-year growth. Additionally, GEV’s substantial backlog provides visibility into its future business prospects.
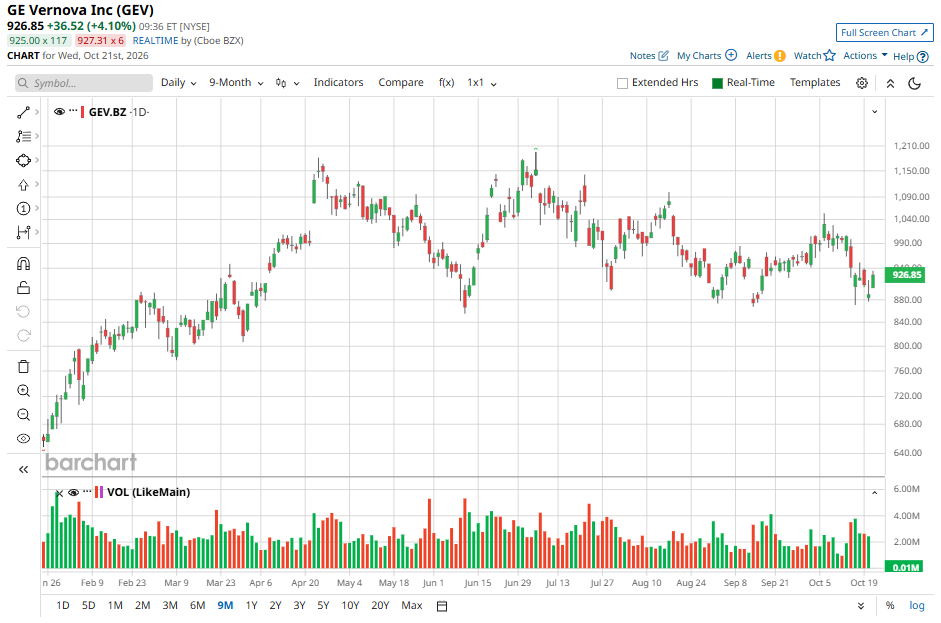
Meanwhile, GEV stock has retreated after a significant rally, falling approximately 26% from its 52-week high. This pullback has helped ease valuation concerns ahead of the Q3 earnings release.
GEV’s Q3 Outlook Remains Solid
GE Vernova is positioned to maintain its growth momentum in the third quarter of 2026, supported by strong performance in its Power and Electrification businesses. In Q2, equipment orders more than doubled, while service orders rose 15%. The company’s total backlog climbed to $176 billion, and profitability improved.
GE Vernova’s Q2 reflected healthy order growth, rising revenue, backlog expansion, improved margins, and strong free cash flow. These trends will continue in Q3, driven by continued robust global demand for its equipment and services.
GEV’s Power business delivered substantial growth in Q2, with total orders more than doubling year over year. Gas Power equipment orders increased approximately fourfold, reflecting higher shipment volumes and favorable pricing across heavy-duty HA and aeroderivative turbines. Service orders rose 12%, supported by Nuclear Power and Gas Power. Segment revenue rose 14%, driven primarily by higher gas turbine shipments and increased service activity. Moreover, EBITDA margin expanded by 320 basis points to 18.8%, driven by improved pricing and greater volumes.
Demand for the Power segment’s contracted gigawatt capacity remains geographically and commercially diversified. The customer base includes approximately 100 customers across 26 countries, with traditional customers accounting for roughly 80% and data centers representing the remaining 20%.
For Q3 2026, GE Vernova expects continued strength in Gas Power equipment orders, alongside revenue growth of 17%–19%. Higher equipment shipments and sustained demand for services are expected to support performance. GEV projects an EBITDA margin of about 17%–18%, up from 13.3% in the year-ago quarter, reflecting volume growth, pricing improvements, and productivity gains.
Electrification continued to deliver strong results, with orders increasing 66% year over year to approximately $6.3 billion in Q2. Demand for grid infrastructure, particularly substations, switchgear, and transformers, contributed to this performance, with North American equipment orders rising roughly fourfold.
The equipment backlog reached $41 billion, up 69% from Q2 2025, reflecting sustained demand across North America and Europe. Revenue increased 68% on a reported basis, including Prolec, and 29% organically.
Segment EBITDA more than doubled year over year, while the EBITDA margin increased 700 basis points to 18.4%, supported by stronger volumes, productivity improvements, and favorable pricing.
For Q3 2026, the company expects segment revenue of $3.8 billion–$4.0 billion, led by continued equipment order growth. Moreover, margins are expected to improve.
Strong revenue growth and margin expansion across Power and Electrification are expected to support GE Vernova’s earnings. Analysts forecast earnings of $4.03 per share, representing more than 145% year-over-year growth.
GEV Stock Is a “Strong Buy” Ahead of Q3 Earnings
GE Vernova is expected to report strong Q3 2026 growth, supported by robust demand across its Power and Electrification businesses, a substantial backlog, and improving margins.
Continued revenue expansion and margin improvements across the Power and Electrification businesses are forecast to support GE Vernova’s earnings growth in the third quarter. Strong demand for gas turbines, grid equipment, and related services, combined with better pricing and operational efficiencies, provides a favorable foundation for the company’s near-term performance.
While its fundamentals remain solid, the stock’s recent pullback eases some of the valuation concerns.
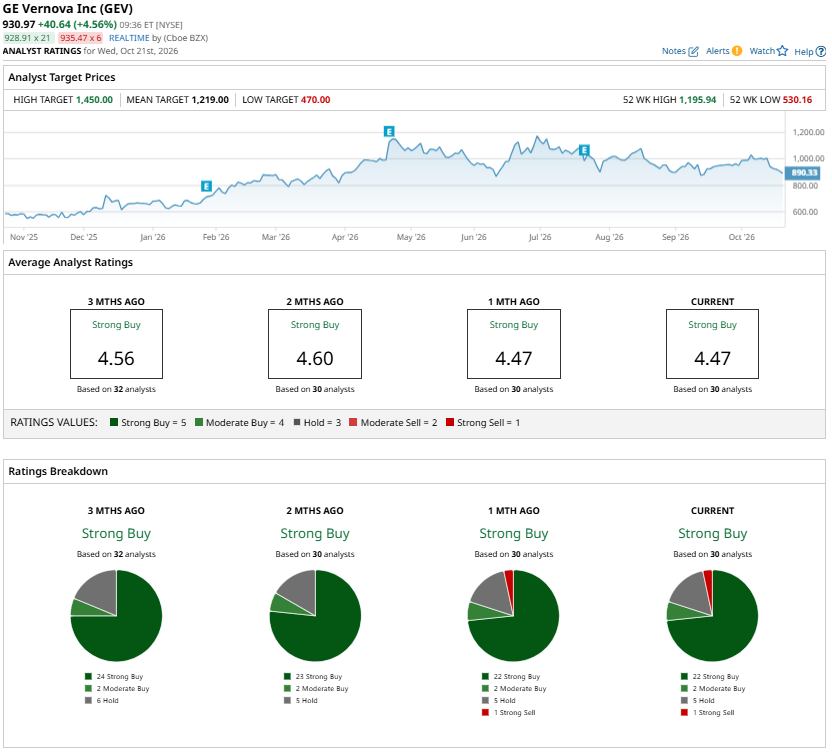
Heading into the Q3 earnings announcement, most analysts covering GE Vernova maintain a “Strong Buy” consensus rating, reflecting continued optimism about the company’s growth prospects.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.