


W.W. Grainger, Inc. (GWW) is a prominent industrial distributor of maintenance, repair, and operating (MRO) products with a $63.7 billion market cap. The Lake Forest, Illinois-based company’s offerings span safety equipment, electrical components, HVAC parts, and facility maintenance products, making it a critical procurement partner for industries such as manufacturing, healthcare, construction, and government.
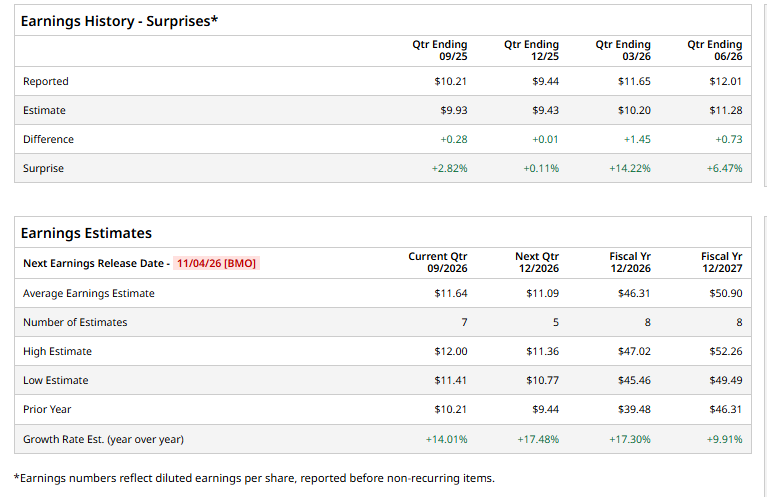
The MRO leader is expected to announce its fiscal 2026 third-quarter earnings before the market opens on Wednesday, Nov. 4. Ahead of the event, analysts expect GWW to report a profit of $11.64 per share on a diluted basis, up 14% from $10.21 per share in the year-ago quarter. The company has surpassed consensus estimates in each of the last four quarters.
For the current year, analysts expect GWW to report EPS of $46.31, up 17.3% from $39.48 in fiscal 2025. Its EPS is further expected to rise 9.9% year over year to $50.90 in fiscal 2027.
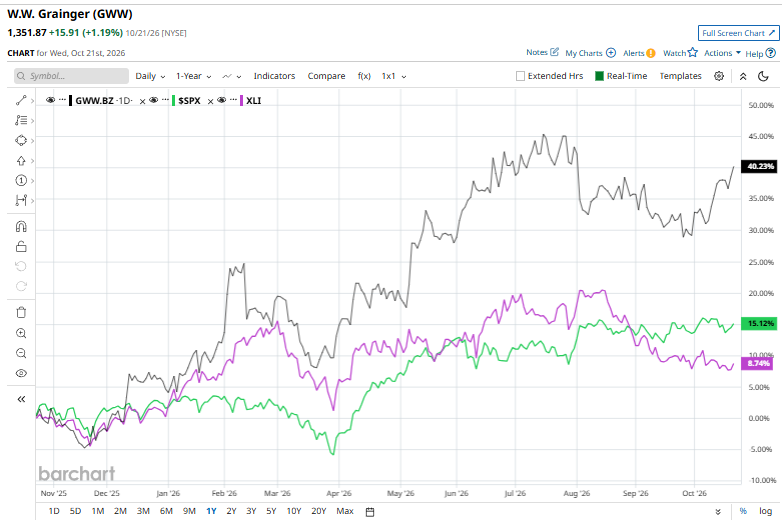
GWW shares rose 39.2% over the past year, outperforming the S&P 500 Index’s ($SPX) 15.2% gains and the State Street Industrial Select Sector SPDR Fund’s (XLI) 8.7% gains over the same time frame.
W.W. Grainger shares’ solid gains over the past year reflect its efficient business model, with a strong 14.8% operating margin supported by effective cost management and fixed-cost leverage. Share repurchases have helped drive annual earnings-per-share growth of 20.7% over the past five years, outpacing revenue growth. Additionally, the company’s market-beating returns on capital highlight management’s ability to deploy resources into profitable growth opportunities.
Analysts’ consensus opinion on GWW stock is cautious, with a “Hold” rating overall. Of 18 analysts covering the stock, three rate it a “Strong Buy,” 13 a “Hold,” one a “Moderate Sell,” and one a “Strong Sell.” While GWW currently trades above its average analyst price target of $1,320.08, its Street-high price target of $1,300 indicates a potential upside of 11% from current price levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.