


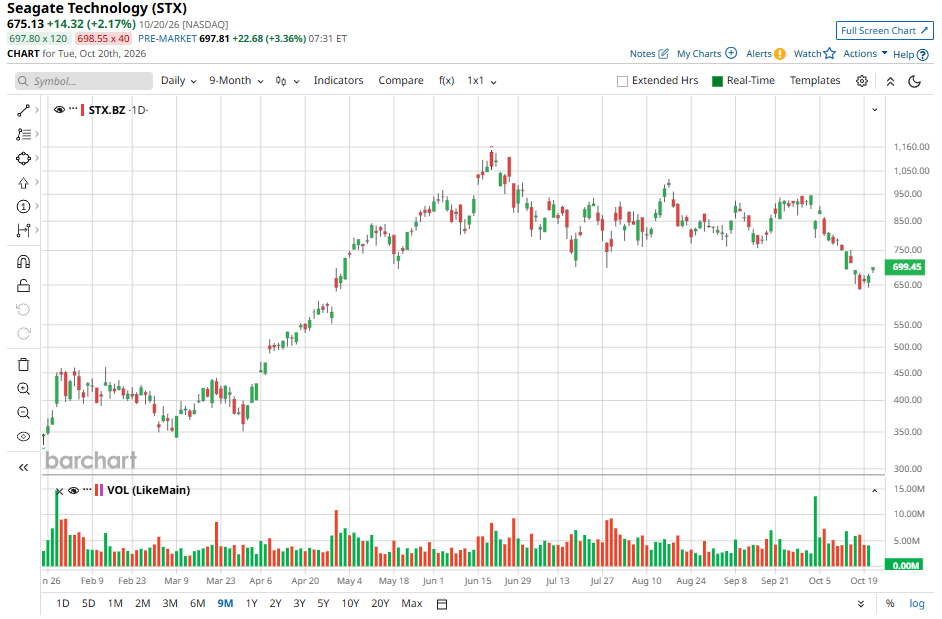
Seagate Technology (STX) will release its fiscal 2027 first-quarter earnings on Tuesday, October 27. Notably, profit-taking after a sharp rally and growing concerns about the sustainability of artificial intelligence (AI) infrastructure spending have pulled back STX ahead of Q1.
While Seagate stock is trading over 41% below its 52-week high, its fiscal 2027 prospects remain solid, supported by robust demand. Seagate continues to benefit from the growing need for high-capacity storage solutions, driven by the rapid expansion of AI infrastructure.
Additionally, a stronger pricing environment is helping support revenue growth and profitability. These favorable industry dynamics are expected to remain key drivers for Seagate’s performance in the first quarter and throughout fiscal 2027.
Seagate’s Q1 Outlook
Despite concerns about the sustainability of AI infrastructure spending, Seagate is likely to deliver solid earnings growth in Q1 and throughout fiscal 2027.
Seagate’s top line rose 34% in fiscal 2026, supported by strong demand for its mass-capacity storage solutions. The growing use of AI-powered applications is increasing cloud providers’ need for data storage, supporting the momentum in Seagate’s business. Seagate’s revenue growth rate is forecast to accelerate in fiscal 2027, reflecting strong demand and a favorable pricing environment.
Seagate projects sequential improvements in margins and cash flow during fiscal 2027. Long-term commitments from data center customers support its outlook amid rising demand. These customers account for approximately 90% of Seagate’s exabyte shipments, while long-term supply agreements have secured allocations for most of its nearline storage capacity through calendar 2028.
Notably, its customers are also exploring longer planning horizons extending into 2029 and beyond. This trend highlights confidence in future infrastructure requirements and provides greater visibility into Seagate’s potential demand.
Industry supply constraints are further strengthening Seagate’s pricing outlook. Management noted that the gap between storage supply and demand has widened in recent quarters. While additional production capacity is expected to become available in the first quarter, Seagate anticipates selling incremental output at favorable prices. Strong pricing conditions could support sequential growth in revenue, gross margins, and profitability throughout the year.
In addition to its revenue growth, Seagate is growing its bottom line at a solid pace and generating cash. During fiscal 2026, adjusted gross margin expanded by 10 percentage points, while adjusted earnings per share (EPS) climbed by more than 90%. Seagate generated $3.1 billion in free cash flow. This momentum will continue in Q1 and fiscal 2027.
Management expects further sequential improvements in margins and cash generation throughout fiscal 2027.
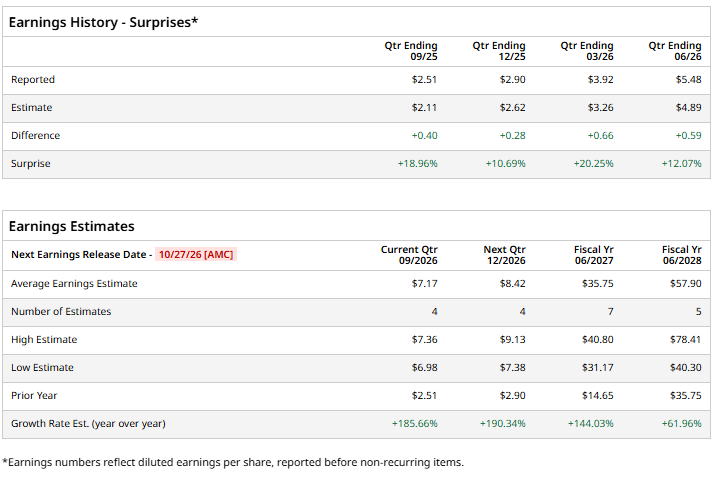
Thanks to its accelerating top-line growth rate and strong margins, Wall Street analysts currently project Seagate to report EPS of $7.17, up 185.7% from the year-ago period. Seagate has exceeded consensus EPS estimates in each of the past four consecutive quarters, including a beat of more than 12% in fiscal Q4. This track record of earnings outperformance indicates that Q1 could be no different.
Seagate Stock Looks Attractive on Valuation Ahead of Q1
Seagate’s valuation looks attractive ahead of its first-quarter earnings report. After the recent share price decline, STX is trading at 17.9 times forward earnings, suggesting it is undervalued.
Analysts anticipate Seagate’s fiscal 2027 EPS to climb 144%, supported by sustained demand for high-capacity storage drives and favorable pricing trends. Expectations remain strong for the following year, with consensus estimates pointing to an additional 62% increase in EPS in fiscal 2028.
Taken together, Seagate’s relatively modest forward valuation, robust projected earnings growth, and supportive storage industry fundamentals suggest the stock has meaningful upside potential.
Seagate Stock a “Strong Buy” Ahead of Q1
Seagate’s Q1 outlook remains strong, supported by favorable storage demand and pricing. Its forward valuation also appears low relative to its robust earnings growth prospects. Seagate is set to deliver strong growth in Q1 and beyond, and most analysts rate the stock a “Strong Buy.”
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.